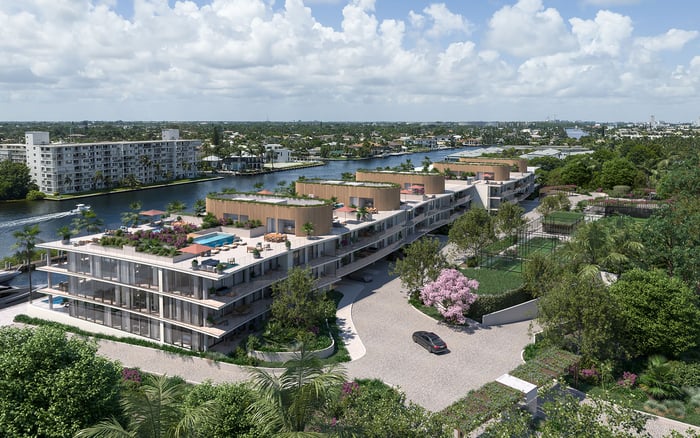
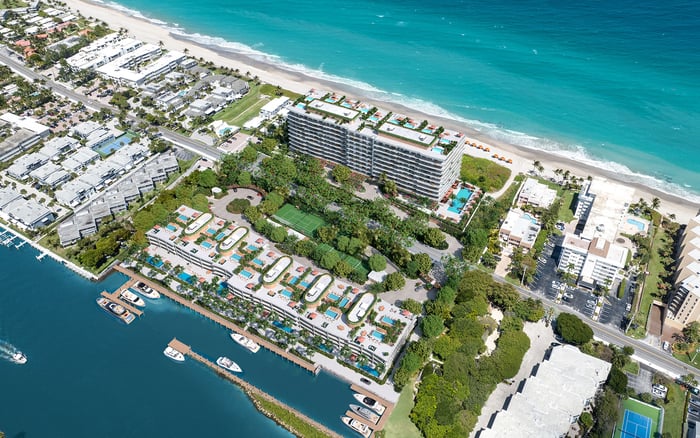
A discreet Hillsboro Beach acquisition begins with disciplined financial preparation. Review currency exposure, deposit protections, proposed securities-backed borrowing, and appraisal contingencies before committing capital, while keeping sensitive documentation under controlled distribution.
For a Hillsboro Beach buyer, discretion should extend beyond the viewing appointment. It belongs in the handling of financial statements, the coordination of advisers, and the certainty surrounding each payment. A polished acquisition begins with a less visible discipline: knowing which funds must arrive, in which currency, on which date, and under which contractual protections.
When considering Rosewood Residences Hillsboro Beach, begin with the current purchase agreement and escrow disclosures, not a regional payment example. The question is not simply how much capital is available, but how much is ready for each obligation-and what could change before closing.
Organize the review around four distinct subjects: foreign-exchange timing, staged deposits, proposed securities-backed credit, and appraisal gaps. Each requires written answers before the buyer considers the funding plan settled.
International purchases commonly involve U.S.-dollar purchase and deposit obligations, though the agreement should confirm the permitted payment currency. A fixed dollar price does not fix the cost in the buyer’s home currency. That cost can change between signing, subsequent deposits, and the final closing wire.
Distinguish exposure before contracting from exposure after a payment obligation exists. For a multiyear pre-construction purchase, review each installment separately rather than applying today’s exchange rate to the entire acquisition and considering the matter closed. Staging capital deployment also stages currency decisions.
An FX forward can lock an agreed exchange rate for specified future payments, reducing uncertainty over their home-currency cost. Ask the currency provider to explain the terms and what happens if the anticipated payment date changes. The objective is not to predict exchange rates, but to understand the obligations being accepted.
Maintain one written schedule covering conversion dates, outbound wires, bank cutoffs, compliance checks, and escrow receipt timing. Have the appropriate parties confirm their responsibilities against the contractual deadlines.
Do not use a regional pre-construction payment example as a verified schedule for a particular Hillsboro Beach development. Confirm the percentages, triggers, and deadlines in the buyer’s current agreement.
For each installment, identify the dollar amount, due date or contractual trigger, intended funding source, and any currency conversion still required. Ask counsel to explain the payment-timing provisions and the consequences of failing to meet them.
Apply the same discipline when a search extends across Broward to The Ritz-Carlton Residences® Pompano Beach. Compare the agreements on offer, not assumptions carried from another residence. Brand identity is no substitute for transaction-specific deposit terms.
Staged payments spread capital deployment across construction, but buyers funding from another currency face repeated FX exposure. Review the payment and currency schedules together, while treating the legal status of each deposit as a separate question.
For a Hillsboro Beach condominium purchase, have counsel confirm which escrow protections apply to each installment and whether any funds may become available for construction before closing. Review the applicable statutory and contractual conditions rather than assuming every deposit receives identical treatment.
Before signing, obtain written confirmation of the escrow holder, account arrangements, release conditions, and any developer construction-draw rights. Ask counsel to distinguish funds held in escrow from funds that may be released, and to explain the relevant agreement provisions.
Escrow does not make a deposit automatically refundable. Recovery depends on the agreement, applicable cancellation rights, and whether the buyer properly terminates or defaults. Keep condominium rules separate from provisions governing one- and two-family dwellings; do not assume a waiver rule transfers between them.
Distinguish delivery deadlines from disbursement conditions as well. If the agreement uses “subject to collection” language, ask counsel what it governs rather than assuming every uncleared deposit necessarily misses its contractual deadline.
If a securities-backed line of credit, or SBLOC, is proposed as part of the funding plan, the next step is a written review with the private bank. A discussion of possible borrowing capacity is not committed closing liquidity.
Ask the bank to document permitted uses, available capacity, interest terms, collateral requirements, draw timing, and repayment obligations. Request a clear explanation of the conditions for drawing funds and whether availability could change before a deposit or closing deadline.
Keep those answers separate from the currency analysis. Ask whether the facility’s currency and draw arrangements match the purchase obligations; do not assume the borrowing provides an FX benefit.
If the search also includes Glass House Boca Raton, apply the same bank-documentation standard. A consistent review tests the proposed funding source against each transaction’s actual payment obligations. It does not presume that a financing arrangement is available for any particular property.
An appraisal gap is the amount by which the agreed purchase price exceeds the lender’s appraised value. It is a valuation difference-not, by itself, a transaction-specific calculation of additional cash required.
Ask the lender to show how a lower valuation would affect the proposed loan and closing funds. Have counsel review the agreement’s financing and appraisal provisions before assuming a disappointing valuation creates a cancellation right.
Potential responses include contributing additional cash, negotiating with the seller, requesting reconsideration supported by stronger comparables, or exploring another lender or loan product. Evaluate each possibility against the contract and remaining time; none should be treated as assured.
For buyers also considering Four Seasons Hotel & Private Residences Fort Lauderdale, carry over the diligence framework, not a presumed valuation outcome. Each property requires its own lender assessment and contractual review.
Discretion rests on current proof of liquid funds, careful redaction, and controlled distribution of sensitive financial information. Agree with advisers which documents each participant needs, without allowing privacy preferences to displace required documentation.
Ownership planning belongs alongside that review. An LLC or trust analysis should consider privacy, FIRPTA withholding at resale, U.S. estate-tax exposure, and annual administrative requirements together. Ask legal and tax advisers to evaluate the complete structure rather than choosing it solely for perceived privacy.
Before committing, bring the payment calendar, escrow review, bank documentation, and appraisal contingency planning into one discussion. The standard is clear: each funding assumption has an identified decision-maker, each deadline has a responsible party, and each unresolved legal or financial question receives specialist attention.
For a considered approach to your Hillsboro Beach property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The buyer’s home-currency cost can change with exchange rates at each deposit and closing, even when the dollar price remains fixed.
Review exposure before contracting, at every deposit deadline, and before the final closing wire. A multiyear payment schedule calls for installment-by-installment planning.
An FX forward can lock an agreed exchange rate for specified future payments, reducing uncertainty over their home-currency cost. Review its terms with the currency provider before committing.
Use the current purchase agreement to confirm each installment’s percentage, trigger, and deadline. A regional payment example is not a verified schedule for a particular development.
Do not assume so. Ask counsel to confirm which escrow protections apply to each installment and whether statutory and contractual conditions permit construction use before closing.
No. Recovery depends on the agreement, applicable cancellation rights, and whether the buyer properly terminates or defaults.
Request permitted uses, available capacity, interest terms, collateral requirements, draw timing, and repayment obligations. Obtain those answers before treating the facility as committed closing liquidity.
Not necessarily. The gap is the difference between purchase price and appraised value; ask the lender to calculate its effect on the proposed loan and required closing funds.
Options include additional cash, seller negotiation, reconsideration supported by stronger comparables, or another lender or loan product. Their suitability depends on the transaction and contractual timing.
Use current proof of liquid funds, careful redaction, and controlled document distribution. Evaluate LLC or trust ownership with advisers across privacy, FIRPTA withholding at resale, U.S. estate-tax exposure, and annual administration.