For a Glass House Boca Raton buyer using an LLC or trust, the court-vacated FinCEN rule currently removes one filing obligation, not the broader need for financial documentation. Here is what the September 13, 2026 legal snapshot means for purchase planning and a future closing.
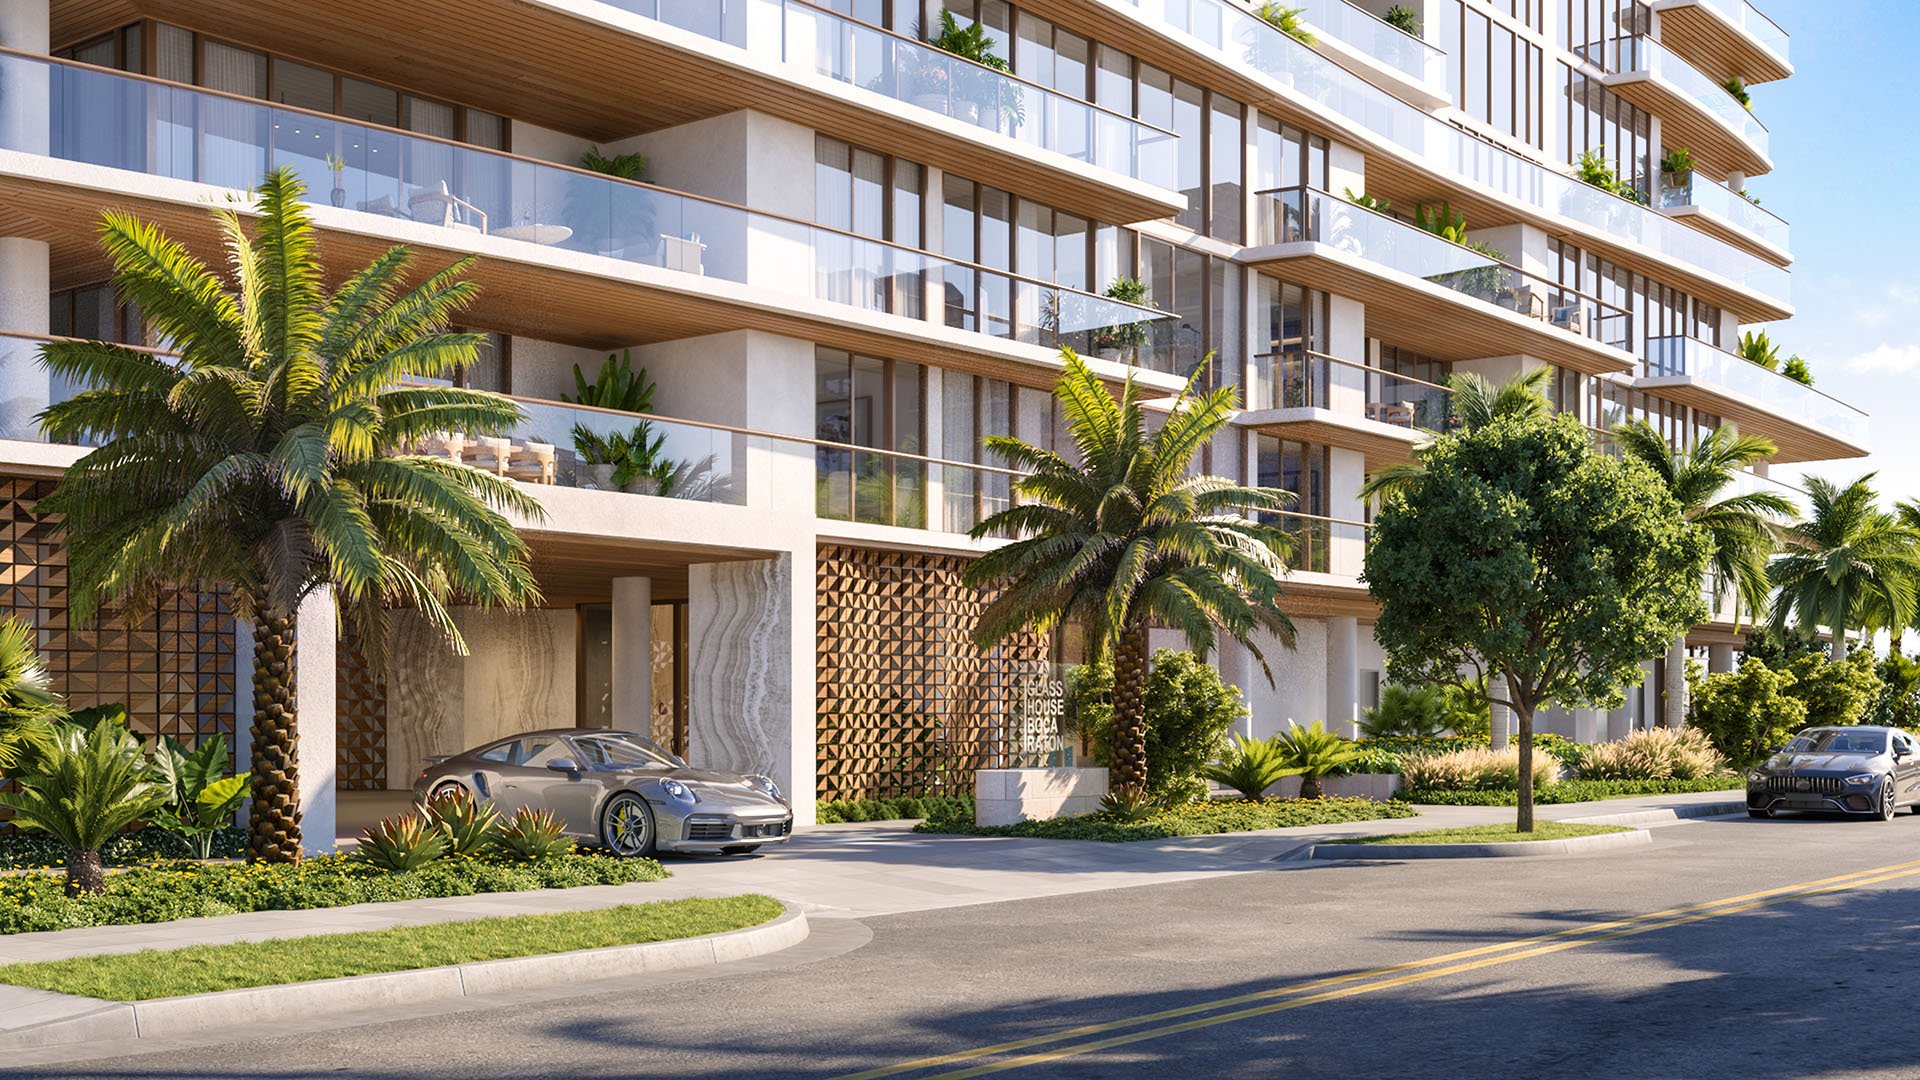
For a buyer considering Glass House Boca Raton through an LLC or trust, the immediate FinCEN question is narrower than whether a cash purchase can remain private. The question is whether this particular residential real estate reporting obligation applies at closing.
As of September 13, 2026, reporting persons need not file Real Estate Reports under the court-vacated Residential Real Estate Rule and face no liability for failing to file while the order remains in force. That position does not create a blanket exemption from financial-compliance requirements.
The distinction matters for buyers who value discretion. A transaction can fall outside this filing obligation while still requiring ownership information and funds documentation for a bank. The prudent approach is to maintain an orderly purchase file, not interpret the vacatur as permission to dispense with documentation.
“Paused” is useful shorthand, but the legal event was a nationwide vacatur. Mandatory reporting had first been postponed from December 1, 2025, to March 1, 2026. On March 19, 2026, the U.S. District Court for the Eastern District of Texas vacated the rule, finding that FinCEN exceeded its statutory authority.
FinCEN, working with the Department of Justice, has appealed. The September 13 position is therefore a dated legal snapshot, not an assurance about every future Glass House closing.
For purchase planning, distinguish the rule's former requirements from obligations actually in force. Understanding the former framework can help organize information if it returns, but its requirements should not be presented as currently mandatory under the vacated rule. Counsel should recheck the operative legal position before closing, including any developments affecting implementation or timing.
Glass House is a luxury condominium development in downtown Boca Raton. Its residential setting is the property decision; the acquiring party's identity and funding structure are separate transaction decisions.
That distinction is useful when considering Glass House alongside Alina Residences Boca Raton. A project name does not establish whether an acquisition would meet a federal reporting test. The analysis concerns the transfer itself: its buyer, financing and any applicable exemption.
Under the vacated framework, four conditions had to align: the property was residential real estate, the acquisition was non-financed, the transferee was an entity or trust, and no exemption applied. A proposed LLC or trust purchase therefore calls for transaction-specific review, not an assumption based solely on the residence selected.
Glass House's $70 million construction loan from New York-based Maxim Capital Group was publicly disclosed in March 2026. That financing concerns the development. It does not determine whether an individual residence buyer's acquisition would qualify as non-financed under the vacated framework.
Likewise, the project's legal contact, 280 E PALMETTO PARK ROAD LLC, does not establish a unit purchaser's identity or structure. The developer-side entity and the buyer-side ownership vehicle should remain distinct in any compliance discussion.
The term “non-financed” also required more care than the everyday phrase “all cash.” Under the former framework, an acquisition could be treated as non-financed even when it involved financing from a non-regulated lender. A loan alone did not resolve the question.
If a purchase involves private credit or another funding arrangement, ask counsel to assess its treatment rather than rely on a label in the offer. The financing's relevant characteristics matter more than the buyer's shorthand for it.
Under the vacated rule, a transferee entity's reportable beneficial owners included individuals exercising substantial control or owning or controlling at least 25% of its ownership interests. Those determinations were made as of closing. Beneficial-owner information included names, addresses and identifying numbers, such as Social Security numbers or applicable foreign identifiers.
The substantial-control and 25% tests described here concern entities. They should not automatically be applied to trusts. A trust acquisition warrants a separate review of how its parties and structure would be treated under any operative requirements.
For a buyer also evaluating The Residences at Mandarin Oriental Boca Raton, the planning principle is the same: choose an ownership structure with legal and tax advisers, rather than around the assumed permanent absence of one filing requirement.
An orderly file would explain the intended purchaser and who can act for it. That is a preparation recommendation, not a statement of Glass House's own closing-document requirements.
The former framework assigned filing responsibility to a closing or settlement professional through a seven-tier hierarchy. It did not make the buyer the report filer. Even so, the information it required made buyer preparedness relevant to the closing process.
The filing deadline was the later of 30 days after closing or the last day of the month following closing. That deadline belongs to the vacated framework; it is not a filing clock currently running while the court order remains in force.
Separate bank anti-money-laundering and know-your-customer obligations remain relevant. An entity or trust buyer may still receive requests about ownership and funds even without a Real Estate Report filing under this rule. Those requests should not be mistaken for reinstatement of the vacated requirement.
For discretion, focus on disciplined information handling. Ask the requesting professional what is needed, why it is needed and how sensitive identifiers should be transmitted securely. The absence of a filing obligation under this rule does not mean complete anonymity or the disappearance of other applicable reporting requirements.
Before committing to an ownership vehicle, have advisers review the proposed transferee, the funding arrangement and any exemption that could matter if the framework returns. Ask the closing team to distinguish current requirements from contingency planning for a possible change in law.
Revisit the position as closing approaches. The pending appeal creates uncertainty, and potential reinstatement means today's absence of a filing obligation should not be treated as a permanent feature of the purchase.
For a Glass House buyer, the practical conclusion is measured: there is no filing obligation under this vacated rule while the court order remains in force, but ownership planning and funds documentation still deserve attention. This is general information, not transaction-specific legal or tax advice.
For a discreet perspective on Boca Raton residences and your next purchase, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAs of the September 13, 2026 snapshot, no filing is required under the vacated rule while the court order remains in force. Other applicable compliance requirements are not eliminated.
Reporting was initially postponed to March 1, 2026, but a federal court subsequently vacated the rule nationwide on March 19, 2026. The vacatur is distinct from the earlier postponement.
FinCEN and the Department of Justice have appealed the decision. Potential reinstatement makes it important to recheck the legal position before a future closing.
No. Banks retain separate anti-money-laundering and know-your-customer obligations, and buyers may still receive ownership and funds-documentation requests.
It covered residential real property transfers that were non-financed, involved an entity or trust transferee, and had no applicable exemption.
Yes. Under the vacated framework, financing from a non-regulated lender could still fall within the non-financed category.
A closing or settlement professional would have been responsible under a seven-tier hierarchy. The buyer was not designated as the report filer.
No. The substantial-control and 25% ownership tests described in this article concern transferee entities; trusts require separate analysis.
No. The $70 million construction loan concerns the development, not the financing classification of an individual buyer's acquisition.
The deadline was the later of 30 days after closing or the last day of the month following closing. It is not a currently running filing deadline under this rule while the court order remains in force.