
For estates retaining or transferring a Florida residence, title, protected homestead, entity records and bank compliance demand separate attention. A federal beneficial-ownership filing exemption does not resolve the broader ownership and funding questions.
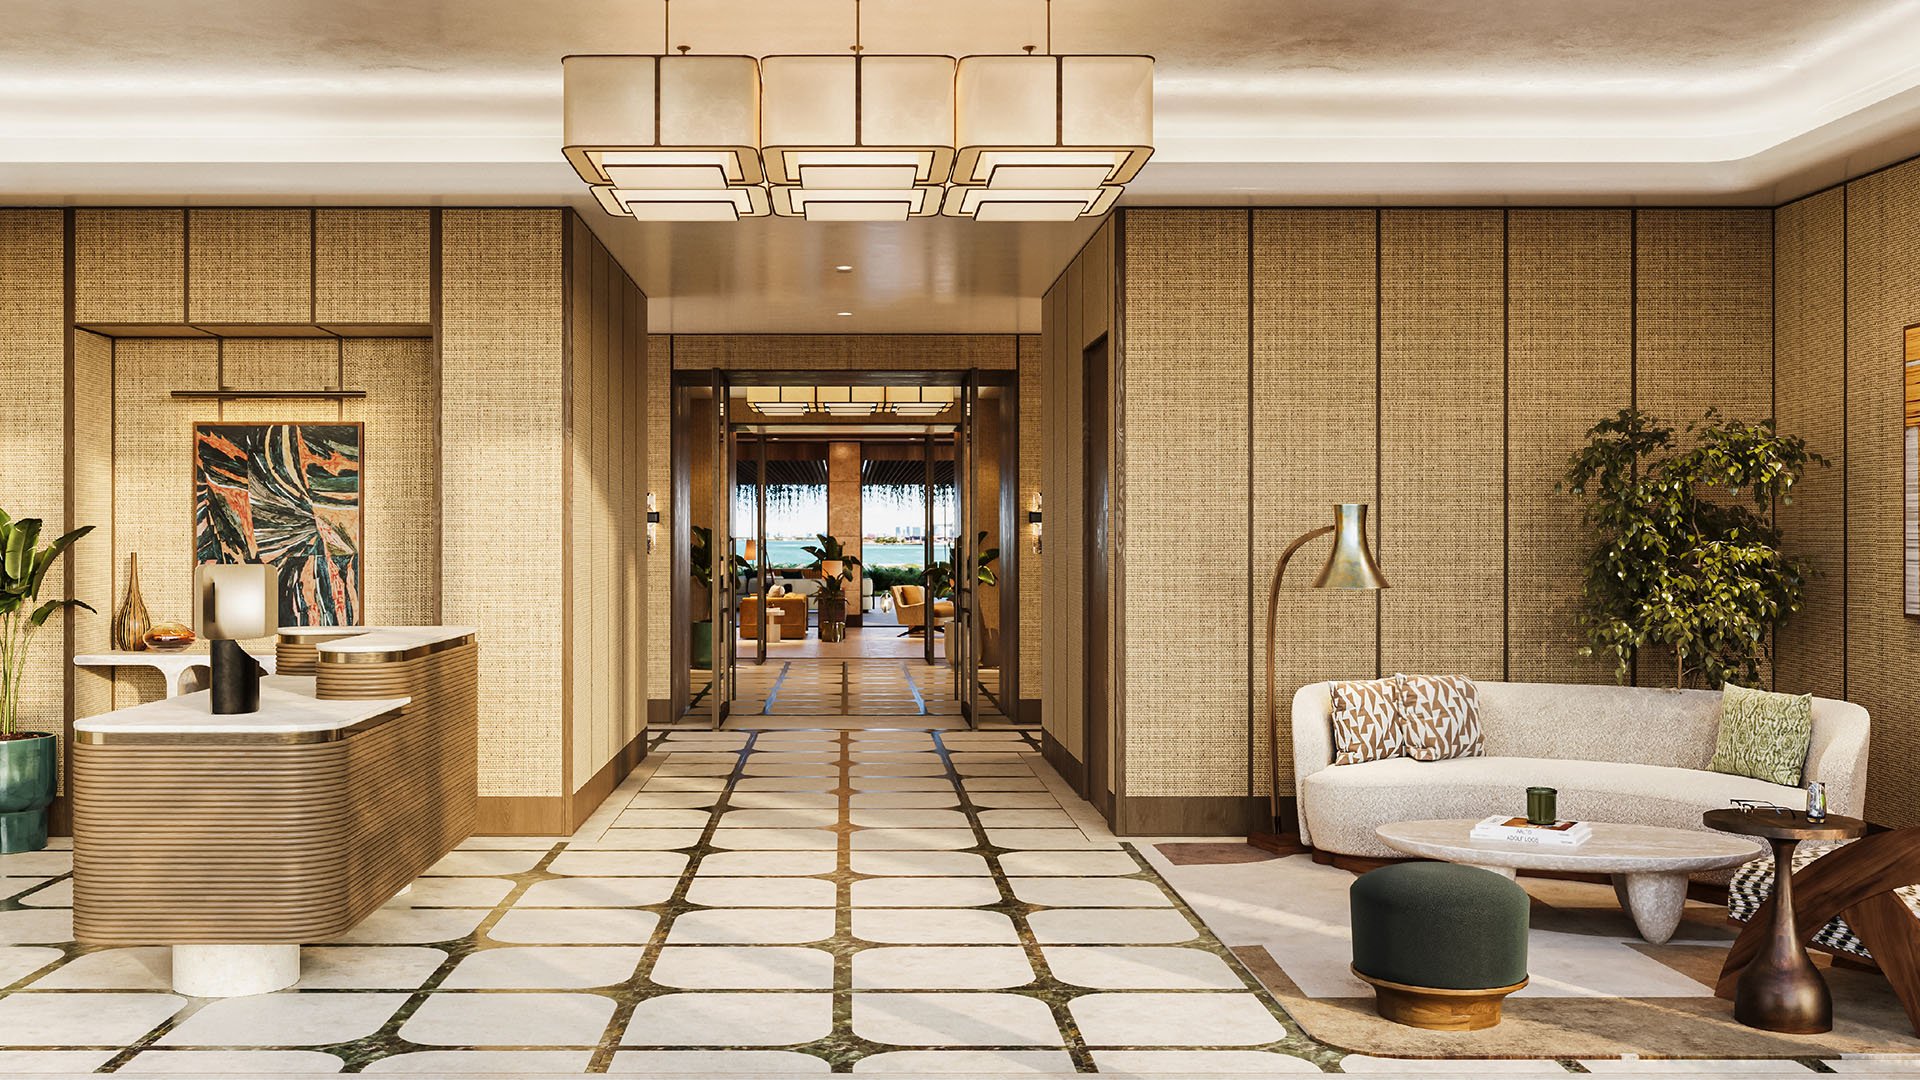
A South Florida residence can be both a deeply personal asset and a consequential part of an estate plan. Whether the intention is to retain a family home, transfer it to a beneficiary or consider a replacement residence, the first conversation should distinguish title, estate authority, funding and compliance. A favorable answer in one category does not settle the others.
For families weighing properties across Surfside, Bal Harbour and the wider coastal market, that distinction deserves as much attention as the address itself. Start with a written ownership map: who holds title, whether an entity or trust is involved, which interests the decedent held and what action the family proposes. Treat this as a planning exercise for counsel, not a substitute for a title determination.
The central principle is simple: exemption from a federal ownership filing is not an exemption from every ownership question.
Under the federal beneficial ownership information framework addressed here, entities created in the United States and their beneficial owners are exempt from BOI reporting requirements. A Florida-formed LLC or corporation generally does not need to submit initial, updated or corrected BOI filings under that domestic-entity exemption.
The key distinction is where the entity was formed-not simply where its owners live or what passports they hold. Foreign ownership alone does not turn a Florida-formed company into a foreign reporting entity.
Certain entities formed under foreign law and registered to do business in the United States generally remain within the federal reporting framework unless another exemption applies. Under that framework, foreign reporting entities do not report BOI for their U.S.-person beneficial owners.
For a family considering The Residences at 1428 Brickell, the planning question is not merely whether ownership will be international. It is which legal structure will hold the residence and how that structure is classified. This illustrates the ownership question; it is not a statement about the project's requirements.
Federal rules can change. Confirm the applicable framework before acting. Do not treat the domestic exemption as permanent or extend it to unrelated obligations.
Federal BOI reporting and bank customer due diligence are separate systems. A bank may still request beneficial-owner information from a domestic company that is exempt from federal BOI filings. The two positions are not contradictory.
For an estate, the funding conversation should begin before the proposed movement of money. Ask the bank what information it requires about the account holder, the ownership structure and the people involved. Do not assume an exemption statement will answer the bank's questions.
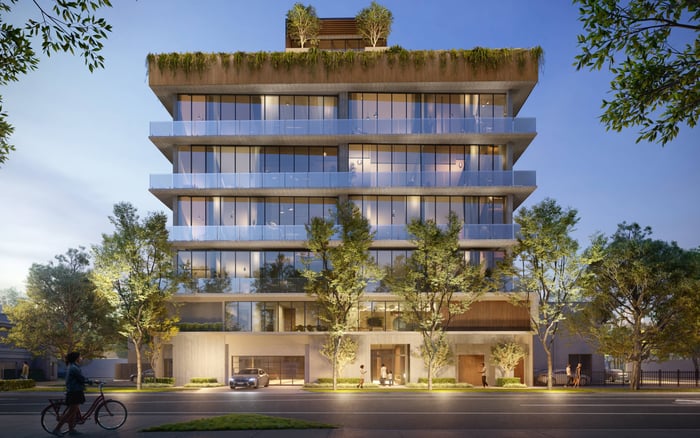
A family evaluating The Perigon Miami Beach as a possible replacement residence should distinguish the property's appeal from the proposed funding arrangement. Ask counsel and the bank to review who would acquire title, who would provide funds and whose authority would support the proposed instructions.
These are coordination questions, not a universal closing checklist. The appropriate information and approvals should be determined for the actual structure and transaction. Federal BOI status alone cannot establish that a funding plan is ready to proceed.
An estate retaining a residence through an entity should keep two questions separate: whether a federal BOI filing is required and what records are useful for administering the ownership structure. The domestic exemption answers the first question within its scope. It does not resolve the second.
As a practical review agenda, ask advisers to reconcile the entity's formation jurisdiction, ownership records and proposed decision-makers. Have counsel identify any applicable entity-maintenance steps and assess who may authorize the contemplated action. Do not infer signing authority from a family relationship or the absence of a BOI filing requirement.
This approach avoids replacing one mistaken assumption with another. An ownership change need not be treated as a federal filing event for an exempt domestic entity. Nor should the exemption be regarded as a complete estate-administration plan.
Keep the exercise proportionate: establish the ownership picture, identify unresolved authority questions and let the relevant advisers specify the next steps.
Florida estate administration gives protected homestead particular significance. A personal representative generally must take possession or control of the decedent's property, except protected homestead and subject to provisions in the will. Protected homestead is also excluded from the decedent's property treated as assets in the personal representative's hands.
Classification is therefore an early issue, not an administrative detail to address after a transfer has been arranged. A residence should not automatically be treated as an ordinary estate asset merely because the decedent lived there or the family expects the personal representative to handle it.
For a family retaining a residence at Park Grove Coconut Grove, the relevant inquiry concerns the particular ownership and homestead circumstances, not the building's identity. Counsel should assess whether protected homestead is involved and what that means for the proposed retention or transfer.
Keep probate homestead analysis distinct from property-tax exemption eligibility. A conclusion about one does not establish the answer to the other, and property-tax guidance does not establish creditor protection.
Placing a Florida home in a trust or life estate does not necessarily eliminate eligibility for the homestead property-tax exemption. For trust-held property, a claimant can have sufficient title when the claimant has legal or beneficial title and the trust grants the right to use and occupy the property. This is not a blanket assurance of eligibility for every trust arrangement.
A move raises a different issue. Florida's homestead property-tax exemption itself is not transferable from one residence to another. A homeowner may nevertheless be able to transfer, or port, all or part of the homestead assessment difference to a new Florida homestead.
When considering Alba West Palm Beach, ask advisers to evaluate exemption eligibility and potential assessment portability separately. Neither should be assumed simply because the previous residence enjoyed favorable homestead treatment.
A disciplined estate review should produce separate answers on title, authority, protected homestead, entity classification, bank information and funding. Keep unresolved points visible rather than compressing them into a single declaration that the residence is ready to transfer.
This is a planning framework, not transaction-specific legal or tax advice. Its value lies in organizing the questions before a family commits to retaining, transferring or replacing a meaningful property.
For a considered view of South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUnder the framework discussed here, a Florida-formed LLC generally does not need to submit initial, updated or corrected BOI filings because of the domestic-entity exemption.
No. Foreign ownership alone does not change a Florida-formed company's classification; formation jurisdiction and U.S. registration status are central to the distinction.
Certain entities formed under foreign law and registered to do business in the United States generally remain subject to reporting unless another exemption applies.
Under the framework discussed here, foreign reporting entities do not report BOI for their U.S.-person beneficial owners.
Yes. Bank customer due diligence is separate from federal BOI reporting, so a bank may still request beneficial-owner information.
No. It addresses federal BOI filing requirements within its scope, not every question about ownership records, entity maintenance or authority.
No. Florida's general duty to take possession or control of a decedent's property excepts protected homestead and is subject to provisions in the will.
Potentially. A claimant can have sufficient title when the claimant has legal or beneficial title and the trust grants the right to use and occupy the property, but eligibility is not automatic.
No. Property-tax exemption eligibility and protected homestead in estate administration are distinct questions; the tax guidance does not establish probate authority or creditor protection.
The exemption itself is nontransferable. A homeowner may nevertheless be able to port all or part of the homestead assessment difference to a new Florida homestead.