For families connecting Seoul and Fort Lauderdale, a residence deserves a coordinated plan for ownership, estate liquidity, title protection, beneficiary decisions, and ongoing expenses.
For a family connecting Seoul and Fort Lauderdale, a residence can be both a private retreat and a long-term family asset. The purchase deserves a strategy that addresses who will own it, who will use it, and how it will remain funded when the original owner can no longer make decisions.
The objective is continuity: a home whose legal arrangements support the family’s intentions. Before signing, bring U.S. estate counsel and Korean tax counsel into the same conversation. Review the proposed ownership structure alongside anticipated use, succession wishes, and funding arrangements. No single structure is the automatic answer.
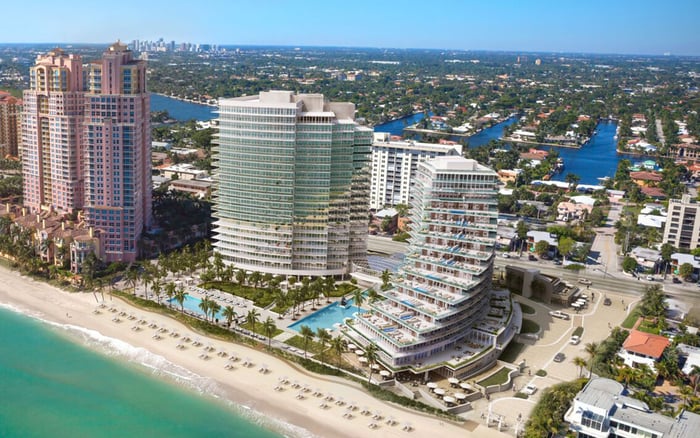
A residence under consideration at Four Seasons Hotel & Private Residences Fort Lauderdale should enter that discussion as a specific purchase, with its own documents and expense estimates-not as an interchangeable entry in a global property portfolio.
An executor for a nonresident, non-U.S. citizen generally must file Form 706-NA when the decedent’s U.S.-situated assets, including U.S. real estate, exceed $60,000 in fair market value at death. This is a filing threshold, not the estate-tax bill. The filing obligation and ultimate tax liability are distinct questions.
That distinction matters before acquisition. Do not use $60,000 as a reserve estimate or assume that the residence’s purchase price alone determines the eventual tax outcome. Ask counsel to assess the owner’s circumstances and proposed holding arrangement before selecting a funding plan.
Nor should a Seoul-based family build its strategy around assumed U.S.-South Korea estate-and-gift-tax treaty relief. Have cross-border counsel confirm the applicable treatment rather than carry over assumptions from other international arrangements.
The practical task is to identify potential obligations and the resources available to meet them. Taxes, debt service, and estate-administration carrying costs belong in that review. Determine which funds would be accessible, who would have authority to use them, and what alternatives exist if a sale is undesirable. The reserve target should follow that analysis, not a generic percentage of property value.
Title insurance protects owners or lenders against covered losses arising from defective or invalid title, liens, and other legal claims affecting title. It is not a substitute for estate planning or beneficiary coordination. Each serves a different purpose.
Florida establishes title-insurance rates. For original owner’s and leasehold coverage, the premium schedule begins at $5.75 per $1,000 for the first $100,000, then $5.00 per $1,000 for the portion above $100,000 through $1 million.
The additional rate is $2.50 per $1,000 above $1 million through $5 million, $2.25 per $1,000 above $5 million through $10 million, and $2.00 per $1,000 above $10 million. The minimum premium for original owner’s and leasehold coverage is $100.
Qualifying reissue coverage has lower rates, including $3.30 per $1,000 for the first $100,000 and $3.00 per $1,000 above $100,000 through $1 million. Eligibility is not automatic. Request an itemized estimate identifying the applicable coverage and separating the title premium from other closing charges.
Retain the deed, owner’s title policy, survey, settlement statement, ownership documents, and lien releases. Arrange access for the appropriate advisers and authorized family representatives rather than leaving the closing record in one person’s inbox.
A family’s shared affection for a residence does not establish who may authorize repairs, occupy it during a holiday, or approve its sale. Create an asset-and-beneficiary inventory, then ask counsel to translate the family’s intentions into appropriate documents.
For a purchase being evaluated at Sixth & Rio Fort Lauderdale, the planning questions should be as specific as the residence itself. Who may occupy the property? Who pays expenses when use is unequal? Who can instruct a manager, authorize urgent work, or approve a major replacement?
Address the less comfortable decisions, too: whether one beneficiary may buy out others, how a proposed sale would be approved, and who coordinates with advisers in each country. A written statement of preferences is useful preparation, but ask counsel what legal implementation is required.
The aim is not to anticipate every disagreement. It is to avoid leaving essential authority and payment responsibilities undefined.
Separate acquisition costs, recurring residence expenses, major replacements, and estate liquidity in the planning worksheet. Distinct categories help the family see what the purchase requires at closing and what continued ownership may require afterward.
Obtain property-specific estimates for taxes, insurance, association charges, utilities, management, routine maintenance, storm preparation, and major replacements. If financing is contemplated, include debt service in the funding discussion. Do not substitute a generalized annual percentage for actual estimates.
When considering St. Regis® Residences Bahia Mar Fort Lauderdale, request the documents and estimates relevant to the contemplated purchase. Review what quoted charges include and what the owner must budget separately. A project name alone does not establish its operating economics.
Assign responsibility for updating the worksheet and approving payments. For an owner spending substantial time in Seoul, the question is not simply what the home costs, but how its obligations will be monitored and funded from a distance.
Florida homestead property-tax relief depends on ownership, permanent-residence status, and applicable eligibility requirements. Purchasing a Florida residence does not, by itself, establish eligibility. Applications and supporting documentation go to the county property appraiser, who determines whether the parcel qualifies.
In Broward County, the 2026 timely filing period ran from March 4, 2025, through March 2, 2026. The absolute late-filing deadline for 2026 exemptions was September 18, 2026. Those dates have passed and should not be reused for another tax year.
Budget without assuming an exemption until eligibility has been established. For future applications, confirm the relevant year’s requirements and deadlines rather than carrying forward an old calendar.
Before signing, align four workstreams: ownership and cross-border tax review, estate liquidity, title and closing records, and beneficiary authority. Pair them with a property-specific operating budget and assign clear responsibility for keeping it current.
This is a planning framework, not individualized legal or tax advice. Its purpose is to make the residence easier to hold, use, and pass on with intention.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn executor for a nonresident, non-U.S. citizen generally must file when the decedent’s U.S.-situated assets exceed $60,000 in fair market value at death. U.S. real estate is included.
No. It is a filing threshold; the filing obligation and ultimate estate-tax liability are separate questions.
No. Have U.S. estate counsel and Korean tax counsel confirm applicable treatment before relying on treaty relief in the ownership or liquidity plan.
Review potential taxes, debt service, and estate-administration carrying costs. Counsel should help assess funding access and authority rather than relying on a universal reserve target.
It protects owners or lenders against covered losses involving defective or invalid title, liens, and other legal claims affecting title.
Original owner’s and leasehold premiums start at $5.75 per $1,000 for the first $100,000 of coverage, then $5.00 per $1,000 above $100,000 through $1 million. Additional coverage has lower incremental rates.
No. Reissue coverage must qualify, so ask the closing professional to confirm eligibility and show the applicable premium in an itemized estimate.
Address occupancy, expense payments, repair authority, sale approval, and possible buyouts. Ask counsel how to implement those intentions legally.
Obtain property-specific estimates for taxes, insurance, association charges, utilities, management, routine maintenance, storm preparation, and major replacements.
No. Eligibility depends on ownership, permanent-residence status, and other applicable requirements, with the county property appraiser determining qualification.