A discreet cash acquisition calls for two distinct budgets: the capital required to complete the transfer and the liquidity needed to own well. This buyer-focused guide separates recording costs from annual reserves and outlines a property-specific approach to taxes, association charges, insurance, staffing, and optional services.
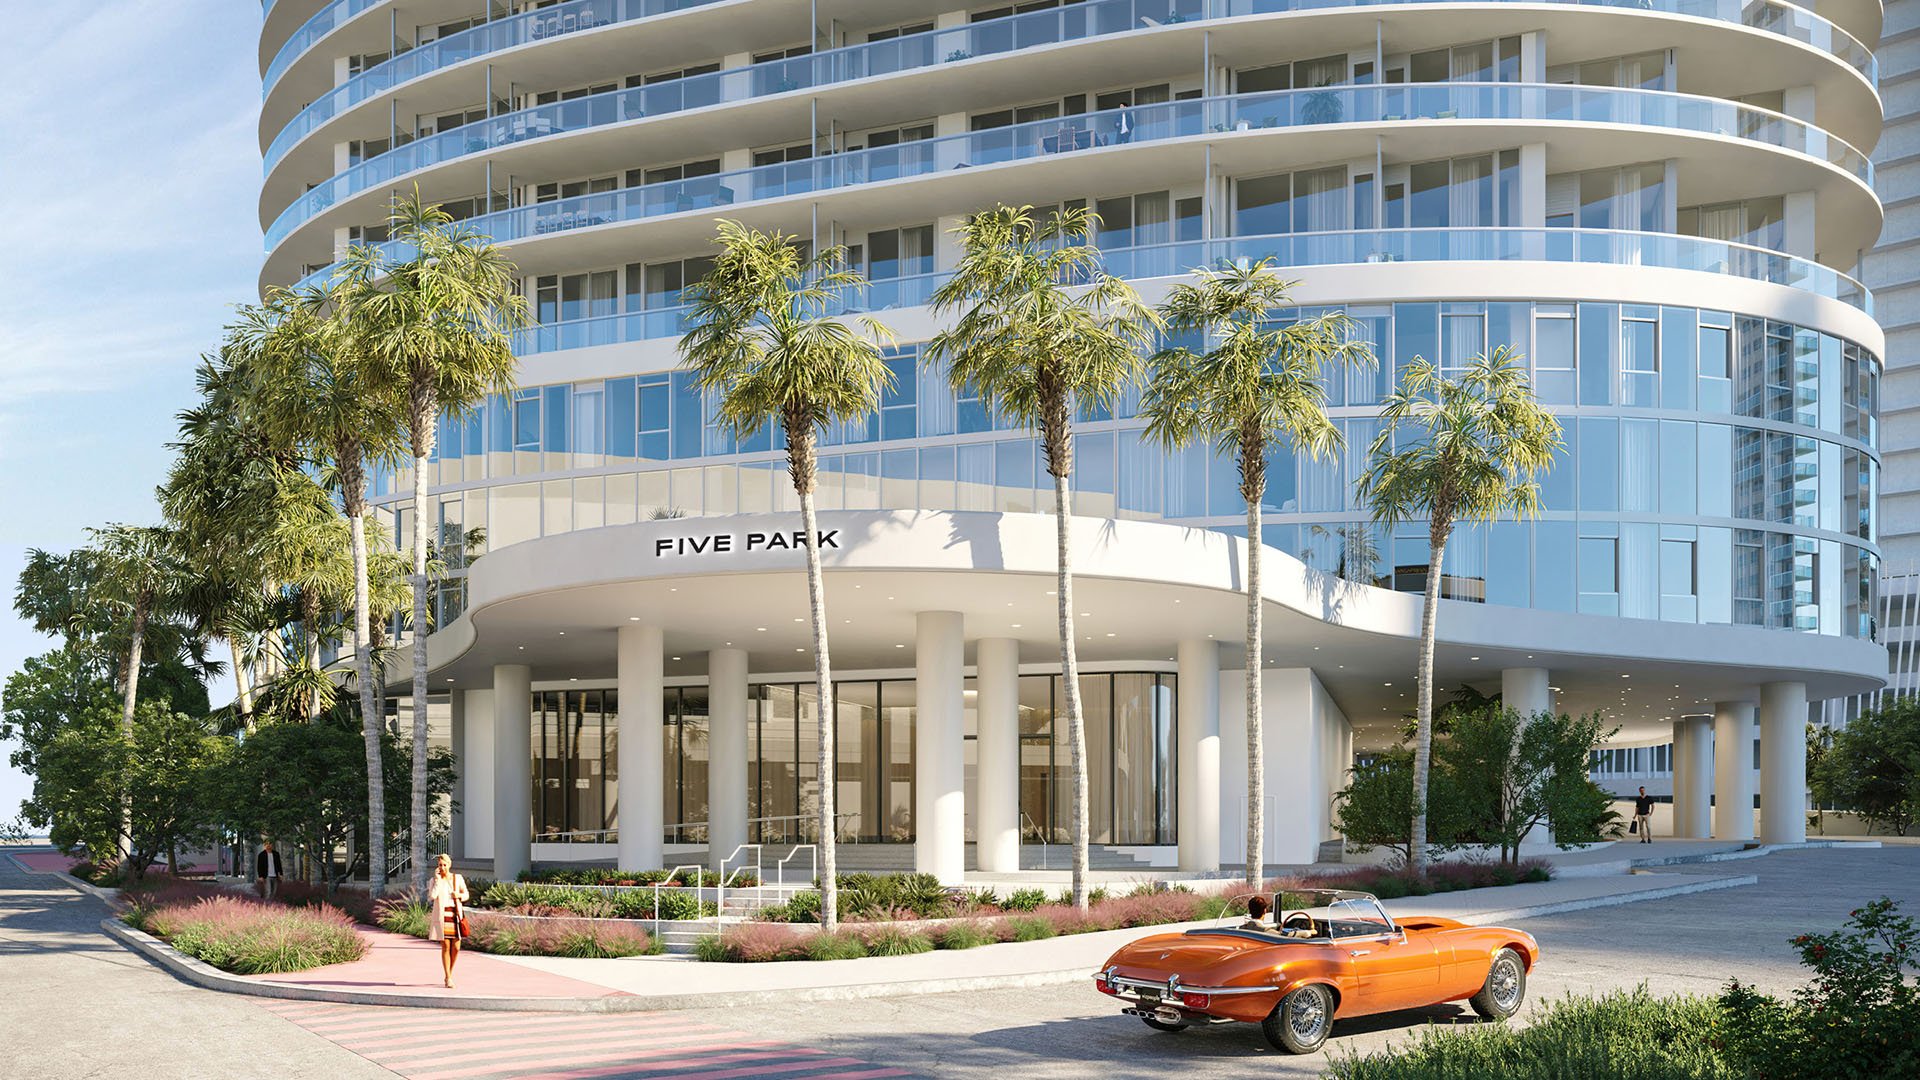
An off-market cash purchase can keep negotiations discreet. It does not make the transfer invisible or establish what the residence will cost to own. For a buyer requiring heightened privacy, financial preparation and disclosure planning should advance together, from offer through recording.
Start with two separate budgets. The acquisition budget covers the purchase and transaction expenses, including applicable deed taxes and recording charges. The annual ownership budget covers property taxes, association charges, insurance, staffing, and selected services. Keep additional liquidity for unresolved exposures visible rather than burying it in a reassuring total.
The objective is not a universal percentage of purchase price. It is a documented reserve plan tailored to the property, the intended ownership arrangement, and the way the household expects to live.
Before submitting an offer, ask counsel to distinguish confidential negotiations from information that will enter official records. A recorded deed becomes part of the county’s official records. An off-market transaction should never be mistaken for an unrecorded transfer.
Establish a written protocol identifying who receives financial documents, who approves their distribution, and who coordinates the recording review. Ask counsel to assess the proposed ownership structure and any applicable disclosures. Do not treat an entity name as a promise of anonymity.
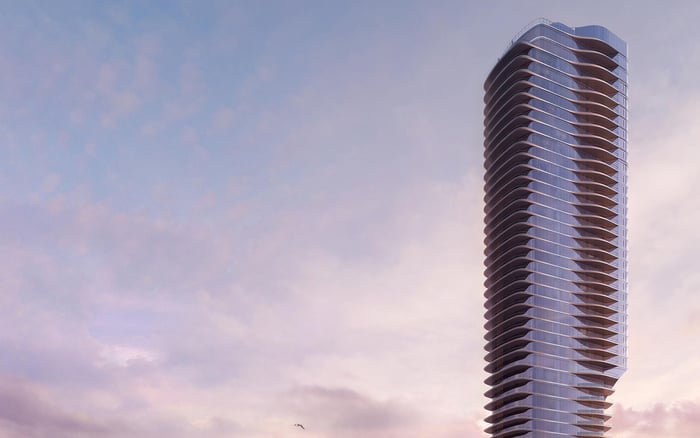
For someone considering Una Residences Brickell, this discipline belongs alongside the residential brief. Keep questions about the residence, the buyer’s disclosure obligations, and the ownership budget distinct. Assign an adviser responsibility for resolving each before closing.
Property taxes require a parcel-specific estimate. In Miami-Dade, applicable millage can include municipal, school, countywide, and other taxing-district components. A single component is not a complete tax rate.
One mill equals $1 for every $1,000 of taxable value. The basic calculation is:
Estimated annual ad valorem tax = buyer-specific taxable value × total applicable millage ÷ 1,000.
The seller’s current bill is background information, not the buyer’s future budget. Assessment rules and exemptions can result in a different post-purchase taxable value for the buyer. Ask for the assumptions behind the estimate, not merely the final number.
A Miami Beach buyer considering The Perigon Miami Beach should apply the same discipline: identify the relevant parcel and confirm how the proposed purchase is reflected in the tax estimate. Neither a neighborhood label nor a purchase price alone provides the complete calculation.
Date the estimate and identify whether its millage assumptions are proposed or adopted. A calculation using proposed rates is provisional, not a final bill. Refresh an earlier estimate before relying on it to fund the ownership reserve.
For a new-homebuyer calculation in Broward, do not treat a county average as a property-specific rate or a finished reserve figure.
When evaluating Four Seasons Hotel & Private Residences Fort Lauderdale, request a residence-specific tax estimate rather than importing a Miami-Dade assumption or adopting a county average without adjustment.
The same care applies in West Palm Beach. For a buyer considering Forté on Flagler West Palm Beach, separate valuation assumptions from tax-rate assumptions. In Palm Beach County, local taxing authorities approve the millage rates. Keep both inputs visible so the estimate can be revised without rebuilding the entire budget.
For association charges, request the residence’s current payment schedule, the relevant budget, and written clarification of what is included. Ask separately about assessments, planned changes, and unresolved amounts. Record the effective date beside each figure.
Distinguish the buyer’s personal carrying-cost reserve from any association reserve contribution identified in the documents. If a contribution is already included in regular charges, do not count it again as a separate owner expense. Keep one-time obligations outside the recurring annual subtotal.
For insurance, commission a property-specific review and written quotations. Ask the adviser to explain the proposed coverage, exclusions, deductibles, payment timing, and how the owner’s policies should relate to any association coverage. Do not derive a premium from the purchase price alone.
Separate the premium allowance from liquidity set aside for deductibles or uncovered exposures. One funds planned payments; the other addresses uncertainty. Neither should be assigned a generic percentage merely to complete the worksheet.
Define the household’s operating brief before assigning a staffing allowance. Specify intended occupancy, responsibilities, coverage during absences, and tasks the owner wishes to outsource. Then obtain written employment or service proposals for professional review.
For optional services, distinguish included access from separately charged use. Price only the services the buyer intends to select, using written terms rather than assumptions about a building’s brand or amenities.
Keep staffing, contracted services, and discretionary spending on separate lines. For each, record the proposed annual amount, payment schedule, cancellation terms, and responsibility for approval. If the same task appears in an association charge and a private proposal, resolve the overlap before funding both.
This is a planning framework, not a market-rate schedule. The reserve should reflect the chosen service scope, with unpriced decisions clearly marked for resolution.
Cash does not generally eliminate Florida deed documentary-stamp tax. In Broward and Palm Beach counties, the rate is $0.70 for each $100 of consideration or fraction thereof. Miami-Dade’s base rate is $0.60, with an additional county surtax of $0.45 for each $100 in applicable transactions.
Ask the closing team to confirm applicability and the complete taxable consideration, which can extend beyond cash paid at closing. Documentary-stamp tax on a recorded taxable document is paid to the clerk or recording official at recording.
A genuinely unfinanced purchase does not generate documentary-stamp tax on a new mortgage. Financing or a deferred-payment instrument requires separate review. Recording fees are distinct from deed taxes; confirm the applicable county schedule, including page and indexing charges.
Keep these transfer expenses outside the annual carrying-cost total. Before authorizing recording, have counsel review the privacy brief against the actual documents-not the assumptions made at the offer stage.
Before closing, consolidate the dated tax estimate, documented association charges, insurance quotations, and selected staffing and service proposals. Label each amount as confirmed, estimated, or unresolved. Distinguish the full-year budget from the cash needed immediately after acquisition.
Fund against the actual payment calendar, not simply one-twelfth of an annual total. Assign responsibility for updating estimates and approving discretionary spending. A carefully documented reserve supports a composed ownership experience without suggesting that privacy or future costs can be guaranteed.
For a discreet conversation about your South Florida residential priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Deeds enter the county’s official records when recorded, so confidential negotiations should not be confused with an unrecorded transfer.
No. Assessment rules and exemptions can make the buyer’s post-purchase taxable value different from the seller’s.
Multiply the buyer-specific taxable value by the total applicable millage, then divide by 1,000. One mill equals $1 for each $1,000 of taxable value.
No. Request an estimate using the residence’s applicable millage and the buyer’s valuation assumptions rather than treating a county average as the final rate.
No. An estimate using proposed rates is provisional and should be refreshed before it is relied on for the ownership reserve.
Generally, no. Florida deed documentary-stamp tax applies separately from financing, while a genuinely unfinanced purchase does not generate tax on a new mortgage.
In Broward and Palm Beach counties, the rate is $0.70 per $100 of consideration or fraction thereof. Miami-Dade’s base rate is $0.60, with an additional $0.45 surtax in applicable transactions.
No. Keep recording fees and deed taxes in the acquisition budget, separate from recurring ownership expenses.
Use the residence’s written association payment schedule and property-specific insurance quotations. Distinguish recurring charges from one-time obligations and premium payments from deductible liquidity.
This framework uses no universal percentage. Define the household’s intended service scope and build the allowance from written proposals and selected services.