A buyer-focused guide to separating lifestyle appeal from supported value, evaluating terraces and bespoke improvements, negotiating appraisal exposure, and keeping recording distinct from tax assessment.
A residence in a private club community can meet a household’s ambitions with unusual precision. The decision to acquire it, however, should distinguish three figures: the negotiated purchase price, the transaction appraisal, and the county’s tax assessment. Each serves a different purpose; none is an interchangeable measure of worth.
The purchase price reflects the agreement between buyer and seller. The appraisal evaluates the property through supported valuation analysis. Florida’s property appraisers establish values annually as of January 1 and apply exemptions, assessment limitations, and classifications that may reduce taxable value. A tax figure is therefore no substitute for a transaction appraisal.
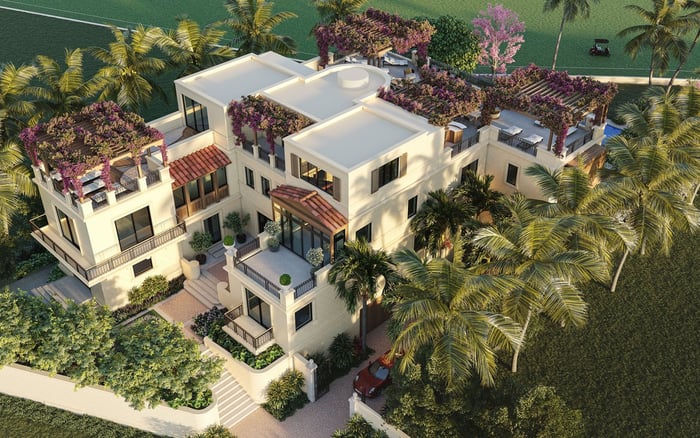
For a household considering The Links Estates at Fisher Island, the starting point is not an assumed premium for exclusivity. It is a clear distinction between what the household values personally and what comparable transactions support. That discipline belongs in the offer discussion, before a valuation difference becomes a closing concern.
The sales-comparison approach examines closed sales, contract sales, and listings, accounting for differences that affect value. Physical and legal similarities matter: site, room count, finished area, architectural style, and condition help determine whether a comparison is meaningful.
For a private-club purchase, ask the valuation team whether relevant same-community transactions are available and how they compare with the subject residence. Proximity alone is not enough. A nearby home with different legal characteristics or substantially different condition may be less informative than a more closely matched property elsewhere.
Consider recency alongside similarity. A recent transaction is not automatically the strongest comparison; an older sale should not be dismissed solely because of its date. The rationale for selection matters more than a superficial match.
Closed sales, pending contracts, and asking prices should not be treated as one category. Transaction conditions, financing concessions, and whether a sale was arm’s-length can affect interpretation. Buyers should also ask their lender which appraisal standards govern the assignment, rather than assume every jumbo or portfolio loan follows identical requirements.
A terrace can be central to a household’s experience of a residence. Its appeal, however, does not establish a universal outdoor-space premium or justify applying the interior price per square foot to exterior area.
The valuation question is how the market responds to the difference. Buyers can make that question concrete by documenting the terrace’s dimensions, layout, condition, and usable arrangement. These details describe what is being acquired; they do not predetermine an adjustment.
When considering The Residences at Six Fisher Island, apply the same discipline: identify the individual residence’s outdoor characteristics, then ask whether relevant comparable transactions support a contribution to value. A project name is not evidence of a terrace premium.
Usable outdoor space can provide meaningful utility, but utility and a quantified adjustment are distinct conclusions. An expensive terrace installation does not automatically add its construction cost to appraised value. The strongest discussion explains both the feature and the evidence of buyer reaction, without treating every exterior square foot as economically identical.
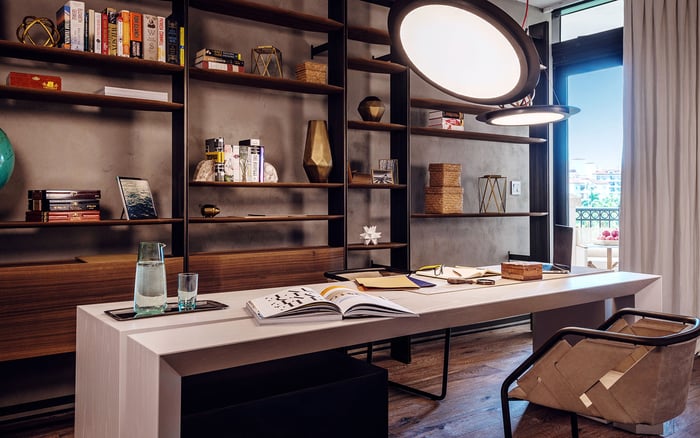
Bespoke interiors present a similar challenge. A seller’s investment may be substantial, while its market-supported contribution is more modest, differently allocated, or difficult to isolate. Construction cost and appraised value are not the same thing.
Prepare a concise improvements dossier for the valuation discussion. It can identify what changed, describe finishes and modernization, distinguish completed work from needed repairs, and include available supporting documents. The purpose is accurate description, not a demand for dollar-for-dollar recognition.
The appraisal should clearly describe improvements, additional features, modernization, and necessary repairs. Supporting addenda can supply detail when the standard form is insufficient. Condition and quality ratings deserve particular attention: incorrect ratings can lead to missing or faulty comparable adjustments.
For buyers reviewing Palazzo del Sol, the principle is the same: assess the individual residence rather than let the project’s identity substitute for an examination of its improvements. A highly personal design may compel one household without generating the same response across the market.
An appraisal gap is a financial decision, not a test of conviction. A household may prefer a residence strongly enough to accept a difference between price and appraised value, but that preference should have a defined limit.
Before committing to gap language, ask the lender how a lower valuation would affect the proposed financing and required cash. Then ask counsel to translate the intended allocation of risk into the purchase contract. Do not assume that a financing provision, an appraisal provision, and a promise to contribute additional cash operate identically.
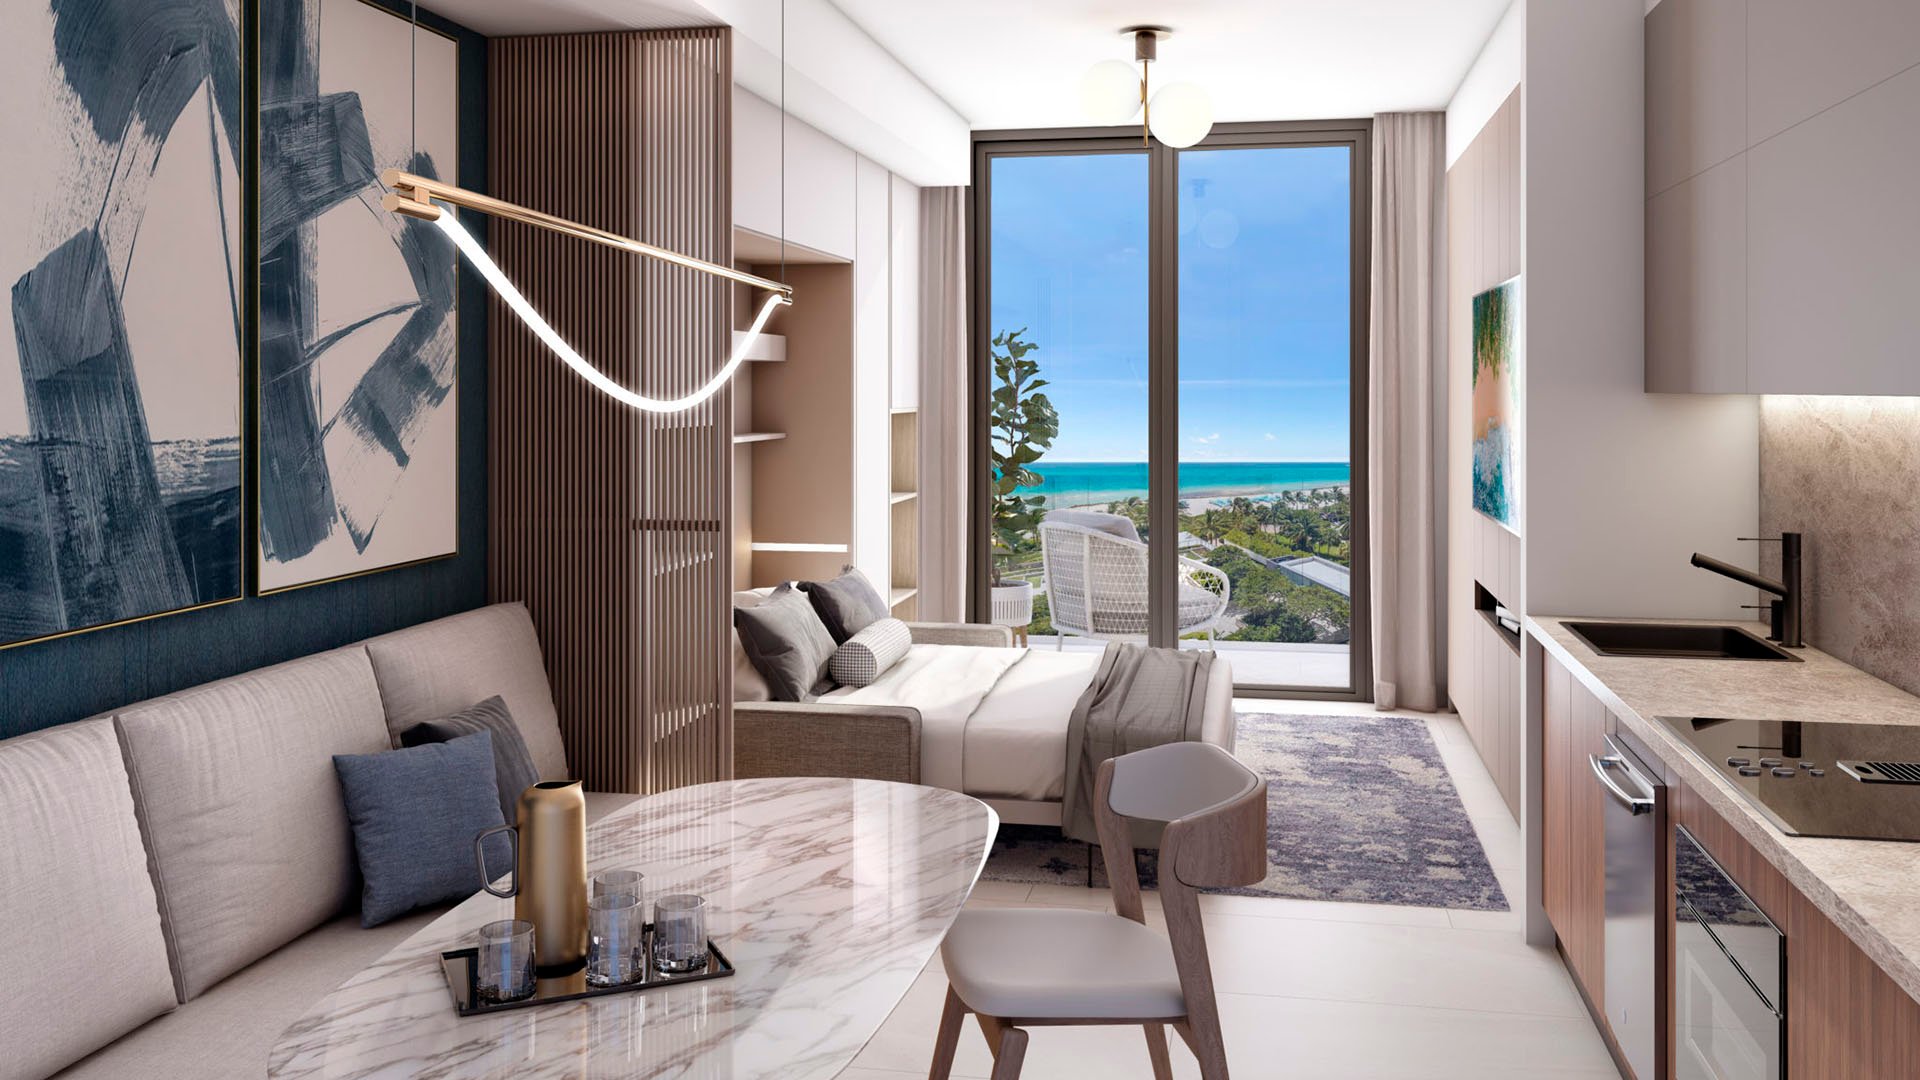
For a search that includes Shell Bay by Auberge Hallandale in Hallandale Beach, have this conversation before the offer is finalized, rather than after the household has emotionally committed.
Questions for advisers should address the maximum additional contribution the household intends to accept, the relevant deadlines, and the options the executed agreement actually provides. None should be presumed universal. Buyers should not assume that a particular reconsideration process, termination right, or seller concession will be available. Each requires confirmation for the specific transaction.
If the valuation differs from the contract price, begin with the substance of the appraisal. Are the property’s physical and legal characteristics accurately described? Does the improvements section capture the renovation and any needed repairs? Are condition and quality ratings consistent with that description?
Next, examine comparable selection and adjustments. A preference for different comparables is not, by itself, proof of error. Focus on identifiable omissions, inaccurate descriptions, and evidence that could materially affect the analysis.
Any request for further review should follow the lender’s applicable procedures. Keep the valuation question separate from the negotiation question: a household can consider changing its economic position without claiming that the appraisal must rise to match the agreed price.
As the purchase moves toward completion, keep appraisal, recording, and tax administration distinct. Miami-Dade County’s Official Records system records deeds and other recordable documents for county properties. Recording is neither a fresh appraisal nor an endorsement of the negotiated price.
Ask the closing team to identify the documents being recorded and the materials the household should retain separately. Confirm county practices locally rather than assume they are interchangeable across South Florida.
The objective is a coherent acquisition: the household understands the residence, the evidence supporting value, the additional cash it is prepared to commit, and the documents marking the transaction’s completion. Personal value can justify a purchase decision without being mistaken for market evidence.
Explore South Florida residences with MILLION and bring a more considered perspective to your next acquisition.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The purchase price reflects the buyer-seller agreement, while the appraisal evaluates value through supported analysis.
No. Florida tax valuation follows an annual January 1 framework, with exemptions, assessment limitations, and classifications that may reduce taxable value.
Similar physical and legal characteristics matter, including site, room count, finished area, architectural style, and condition. Transaction conditions also affect the comparison.
No. An older, more similar transaction can be more informative than a recent sale with substantial differences.
No universal terrace premium is established. Any adjustment should reflect market evidence of buyer reaction to the property's differences.
Not automatically. Their contribution depends on market response rather than the owner's spending or personal preferences.
It should identify the work, finishes, modernization, additional features, and any needed repairs. Available supporting documents can help clarify the property's actual condition.
Ask the lender how a lower appraisal affects financing and cash requirements, and ask counsel to confirm the intended commitment and rights in the contract.
No. Review procedures and contractual options should be confirmed for the specific lender and executed agreement.
No. Recording deeds and other recordable documents is distinct from transaction appraisal and county tax valuation.