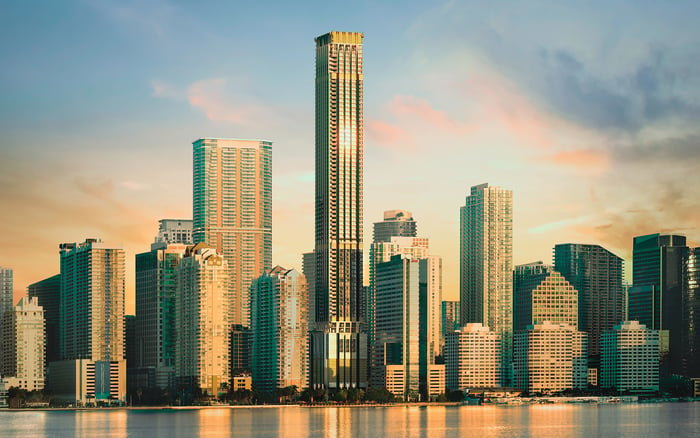
A cash purchase funded by securities-backed credit requires more than available borrowing capacity. For buyers taking title through a revocable trust, disciplined planning connects lender terms, independent liquidity, trust-specific review, seller payoffs, verified wires, and recording confirmation.
For a South Florida buyer, purchasing through a revocable trust with securities-backed credit can preserve an investment portfolio while funding a residence. The appeal is clear: acquire the property without immediately selling the securities pledged to the lender. Yet the cash delivered at settlement may carry obligations that persist long after the keys change hands.
Whether considering Una Residences Brickell or another residence, distinguish three questions: what the purchase contract requires, how the lender will release funds, and how the trust will acquire title. A securities-backed line of credit, or SBLOC, addresses funding. It does not establish the contract's definition of cash, the trust's authority, or the closing team's requirements.
The objective is not simply to reach closing. It is to complete the purchase without making household liquidity dependent on favorable markets.
An SBLOC can finance real estate without an immediate portfolio sale, but the pledged assets remain exposed to market volatility. These facilities are generally demand loans: the lender may require repayment at any time rather than follow a fixed mortgage-style term. Treat that repayment right as a central consideration, not a remote technicality.
Before relying on the facility, review eligible collateral, borrowing limits, maintenance requirements, and the lender's repayment rights. Confirm the proposed use of proceeds with the lender. SBLOCs generally carry non-purpose restrictions and cannot be used to purchase or trade securities.
Have counsel review the purchase contract's funding representations and any requested evidence of available funds. An available credit line is not the same as money ready for settlement. Confirm the draw procedure and funding deadline rather than assuming the facility will deliver funds whenever the closing team needs them.
A revocable-trust purchase requires its own review, separate from the credit decision. Ask the buyer's attorney and settlement team to confirm the proposed title designation, who will sign, and which documents they require to establish authority. Do not presume that an individual borrower and a purchasing trust can be treated interchangeably.
The lender should separately confirm whether the proposed borrower, collateral ownership, and route of funds are acceptable under its facility. If proceeds will move between an individual and the trust, ask legal and tax advisers to review the arrangement before directing the transfer. These are transaction-specific questions, not universal instructions for trust purchases.
For a buyer evaluating The Perigon Miami Beach, the practical priority is alignment: the contract, trust documentation, lender instructions, and settlement instructions should describe a funding path reviewed by the relevant parties.
When collateral falls below required coverage, the lender may issue a maintenance call requiring additional cash, eligible securities, or partial repayment. Borrowers typically have only two or three days to respond. In that short window, accessible liquidity is more useful than an intention to sell assets later.
An unmet call can trigger liquidation of some or all pledged securities. The borrower may have limited control over which positions are sold, and forced sales can create capital-gains tax liabilities even when the proceeds repay the loan. Deferring a voluntary sale at acquisition does not guarantee that a sale, or a tax liability, will be avoided later.
Concentrated holdings warrant particular attention. A decline in one major position can impair borrowing capacity without a broad market downturn. Before closing, ask the lending and investment teams to assess how weaker collateral values would affect both the outstanding balance and the remaining ability to borrow.
Unused borrowing capacity is not a separate cash reserve. When collateral values fall, that capacity can contract precisely when additional liquidity is needed. A prudent approach is to retain accessible resources outside the pledged portfolio rather than rely entirely on another draw or a last-minute securities sale.
No single reserve percentage makes every transaction resilient. Size the buffer with advisers around the facility's terms, portfolio concentration, potential maintenance demands, and the buyer's other cash commitments. Distinguish money reserved for settlement from resources intended to meet a collateral call after closing.
For a purchase under consideration at Four Seasons Residences Coconut Grove, the same discipline applies: assess the acquisition alongside the liquidity that remains afterward. SBLOC interest rates can change, so ongoing cash-flow planning should also allow for potentially higher borrowing costs.
Two distinct movements of money can become blurred in closing discussions. The buyer's SBLOC draw supplies acquisition funds. The seller's mortgage or lien payoff addresses existing obligations associated with the property. Calling the purchase cash does not eliminate those title obligations.
Ask the settlement team to identify applicable payoffs and explain how they appear in the settlement statement. Florida title-closing services can include payoff coordination, statement preparation, signing arrangements, and confirmation of recording details. Review the final statement with the team so the amount requested from the lender aligns with the authorized funds needed for settlement.
Whether evaluating Alba West Palm Beach or a different property, keep separate confirmations for the lender's funding request and the settlement team's payoff coordination. Confirmation of one is not proof that the other is complete.
Before transmitting funds, independently verify wire instructions through a trusted contact channel established separately from the message containing them. Be particularly cautious when instructions arrive by email, change unexpectedly, or introduce urgency. Question changes before sending money; suspected wire fraud requires immediate action.
Confirm the transaction's actual funding deadline, signing arrangements, remaining closing conditions, and instructions for releasing funds. Do not assume that signing, funding, disbursement, and recording follow a universal Florida sequence. The settlement team coordinates signing, verifies applicable conditions, submits required documents for recording, and distributes authorized funds after approval to close.
Ask how recording details will be confirmed and who will communicate completion. Signing is one milestone; confirmation that the required documents have been submitted and recorded is a separate matter to track with the closing team.
Recording does not end the SBLOC's collateral exposure or the lender's repayment rights. Continue monitoring pledged holdings, accessible reserves, and borrowing costs. Maintain a repayment plan that does not depend solely on stable markets or indefinitely available credit.
The most considered purchase preserves choices after acquisition: liquidity to respond, clarity about trust ownership, and a coordinated record of funding and settlement.
For a discreet perspective on South Florida residences and your next acquisition, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn SBLOC can supply purchase funds without immediately selling the pledged investment portfolio. Confirm the intended use and funding arrangements with the lender.
Not necessarily. A buyer using an SBLOC delivers purchase funds while retaining a separate obligation to the securities-backed lender.
SBLOCs are generally demand loans, so the lender may require repayment at any time. Review the facility's repayment rights before relying on it.
A maintenance call can occur when pledged collateral falls below the lender's required coverage. The lender may require cash, additional eligible securities, or partial repayment.
Borrowers typically have only two or three days. Confirm the facility's specific deadlines and maintain accessible liquidity.
The lender may liquidate some or all pledged securities, with limited borrower control over which assets are sold. Those sales can also create capital-gains tax liabilities.
It is not equivalent to independent cash because falling collateral values can reduce available borrowing capacity. Reserve planning should include liquidity outside the pledged portfolio.
Ask counsel and the settlement team to confirm title designation, signing authority, and required documentation. The lender should separately review the borrower, collateral ownership, and proposed funding path.
No. Applicable seller mortgage and lien payoffs remain part of closing coordination and are distinct from the buyer's SBLOC draw.
Independently verify instructions before sending funds, especially if they change or arrive with urgency. Question unexpected changes and act immediately if fraud is suspected.