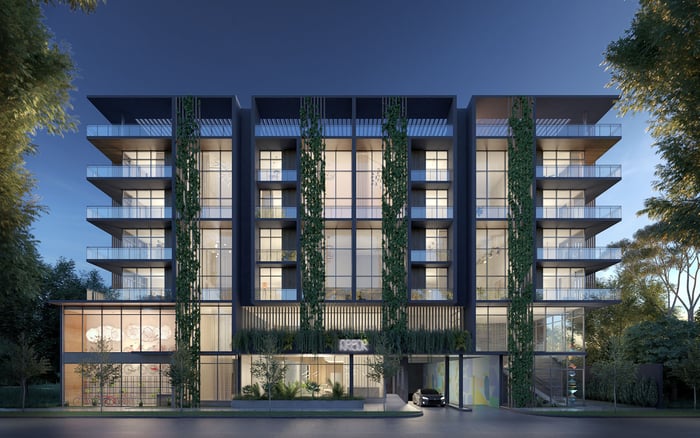
A buyer-focused guide to coordinating insurance acceptance, final settlement figures, wire timing, and contractual contingencies when preparing to close at Opus Coconut Grove.
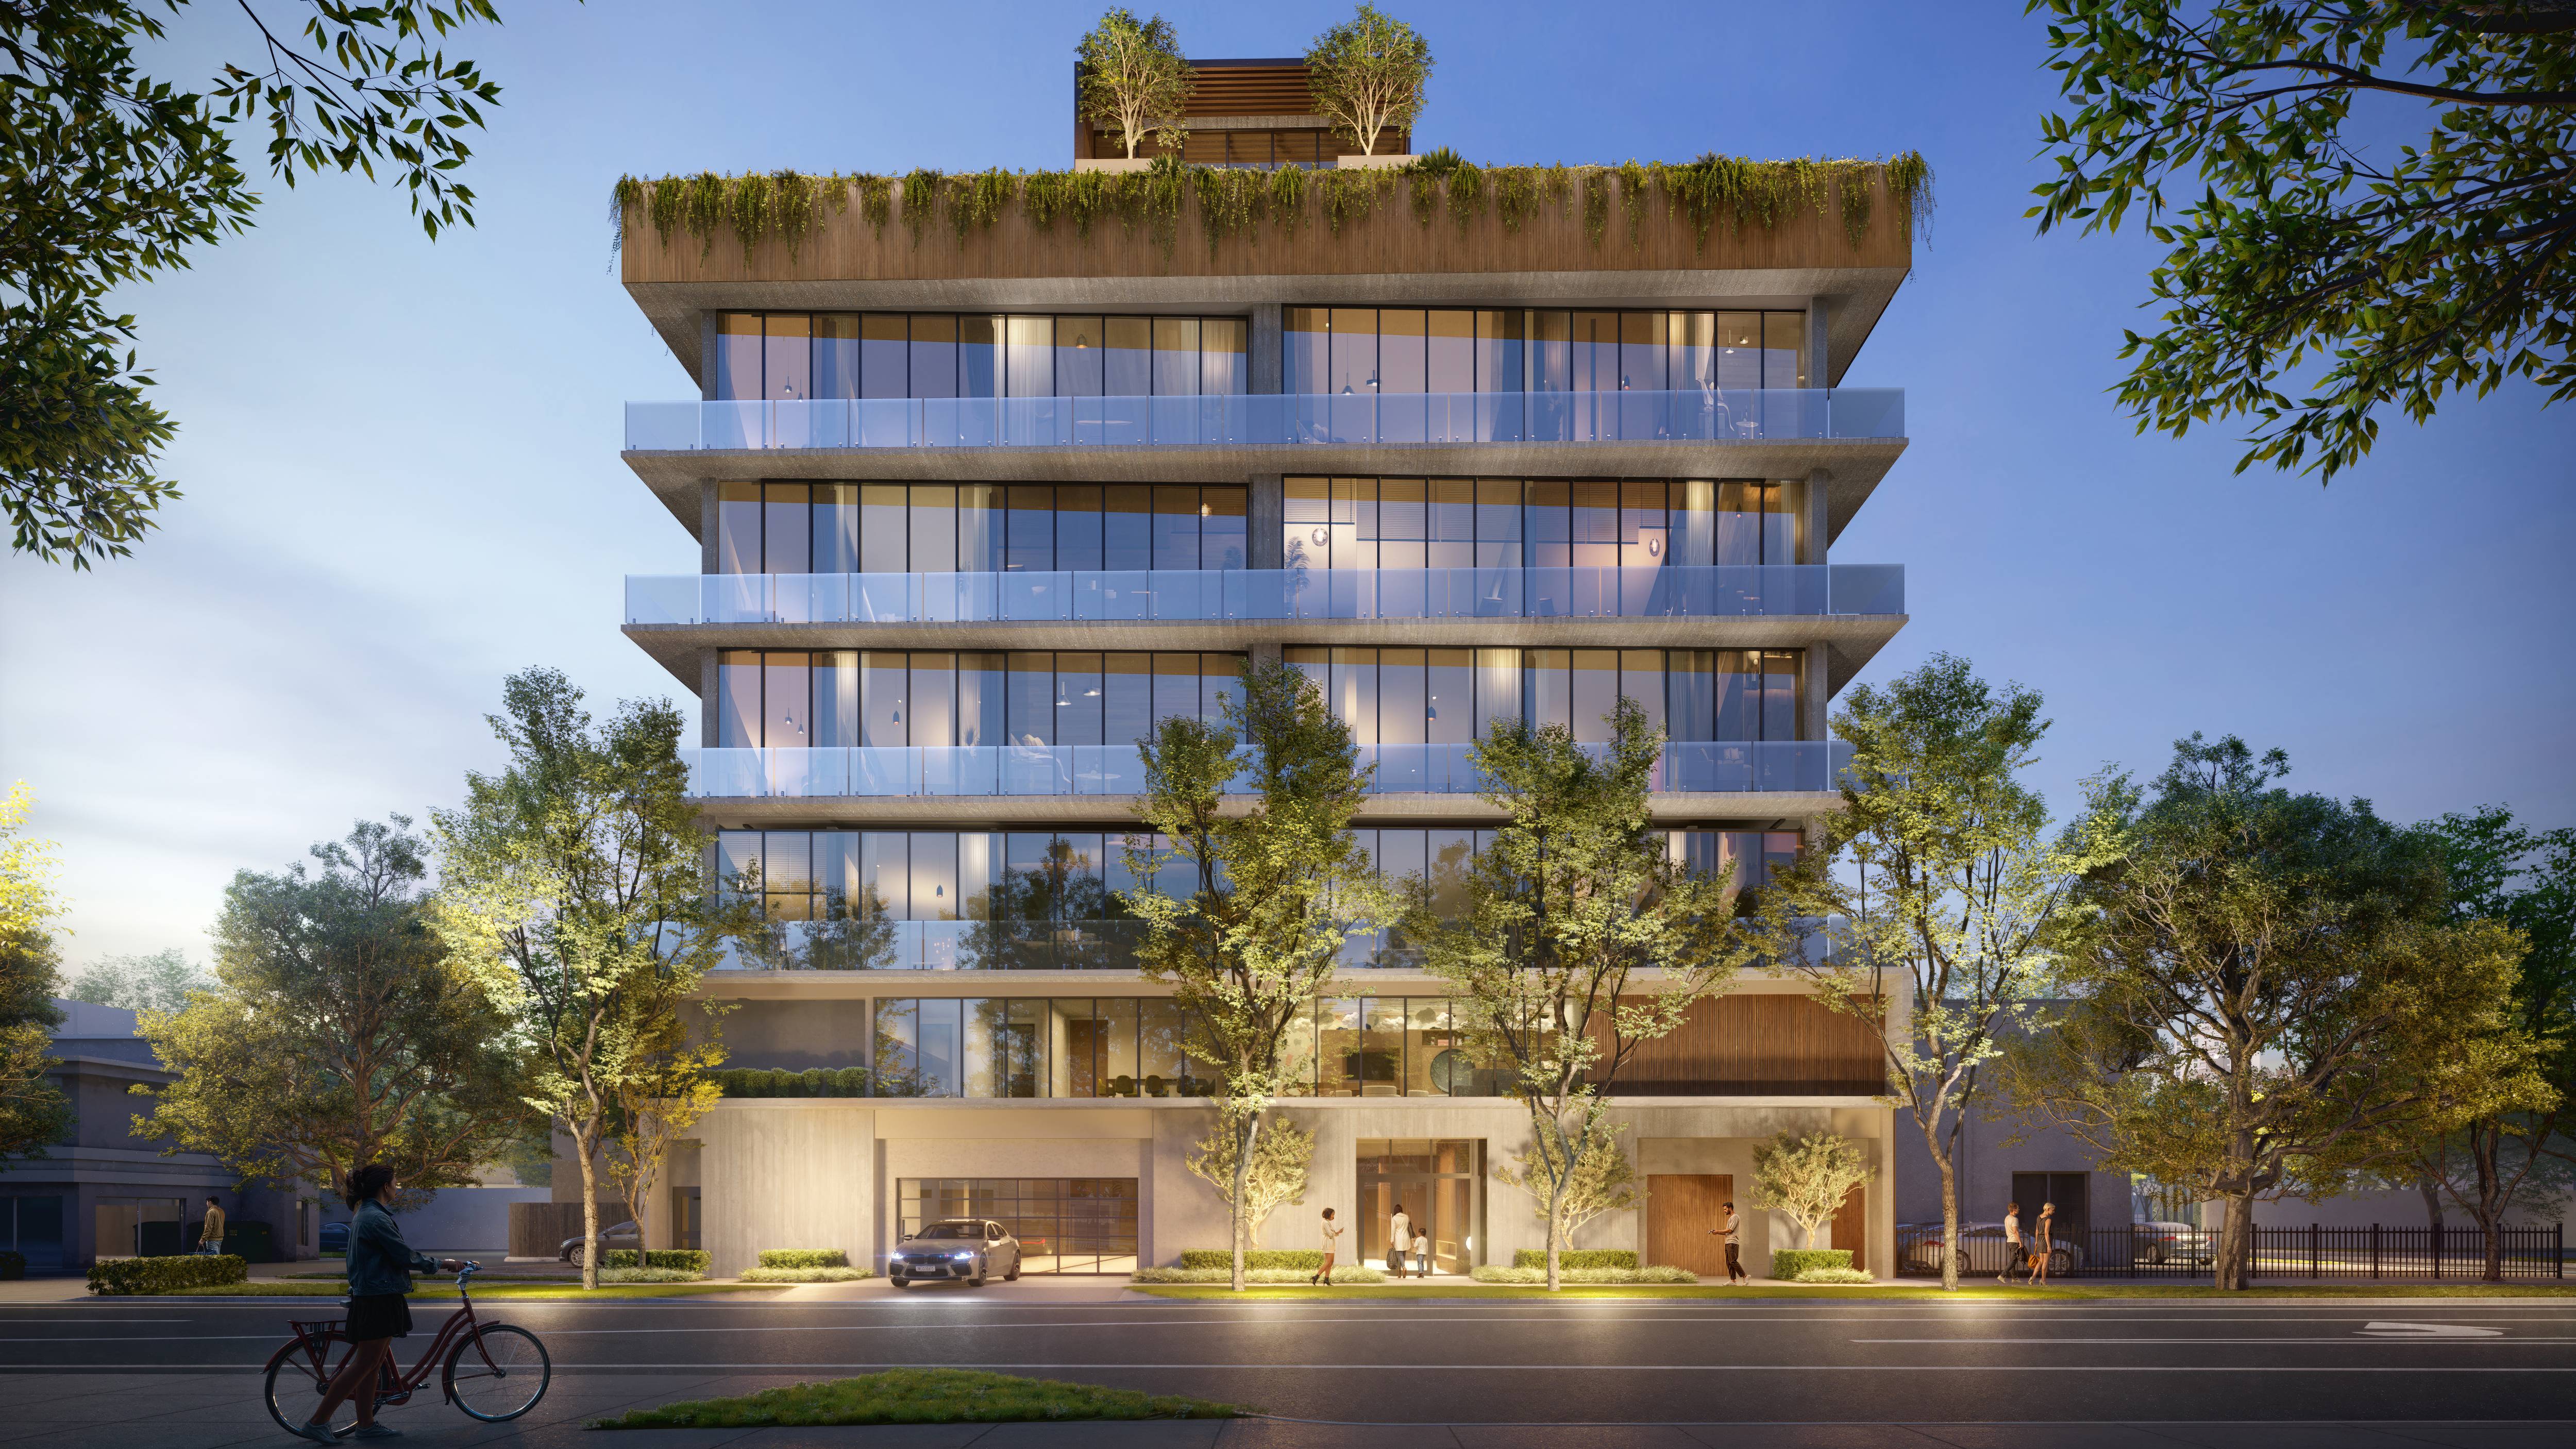
For a buyer at Opus Coconut Grove, the transition from accepted offer to ownership deserves the same attention as the residence itself. The project’s site address is 3137 SW 27th Avenue, Miami, FL 33133. Yet the address is only the starting point: completion depends on coordinated documents, accepted insurance, reconciled funds, and the obligations set out in the purchase agreement.
A sound closing plan distinguishes a scheduled signing from a completed closing. A polished appointment cannot compensate for an unaccepted binder or a wire that has not been received and collected. The buyer’s objective is to resolve those uncertainties before closing day, not across the signing table.
For an Opus purchase, review the brochure and formal condominium disclosures with counsel rather than relying on oral representations. Cross-check marketing language against those documents before using it as the basis for a purchase decision or an assumption about closing obligations.
Keep the executed purchase contract and amendments at the center of the closing plan. Ask counsel to identify the contractual deadline, required deliveries, and any provisions governing delays or extensions. A general explanation of Florida closing practice does not establish the terms of an individual Opus purchase.
For buyers also considering Arbor Coconut Grove, the useful comparison is document-based: review each purchase on its own terms rather than carrying assumptions from one residence to another. Confirm the closing agent’s identity and instructions through the transaction documents and your advisers.
For a financed purchase, an insurance binder provides evidence that coverage will be effective at closing and may be required before the lender releases funds. A binder generally identifies the insured, the property, coverage, the effective date, deductibles, and the lender’s mortgagee information.
Review those details together. Ask the insurance professional to confirm the property identification and effective date, then have the lender verify that the coverage and mortgagee information meet its requirements. Send the required insurance documentation to both the lender and closing agent before funding.
The critical distinction is acceptance, not delivery. An attachment arriving in an inbox does not establish that the lender has cleared the insurance condition. Obtain confirmation that the documentation is acceptable and ask whether any corrections remain outstanding.
Confirm any lender-required flood coverage alongside the primary property policy. Do not assume that association master insurance eliminates the need for unit-owner coverage. Review the applicable association documents with the insurance professional and lender to establish what the buyer must arrange.
Begin insurance arrangements well before closing. During hurricane season, binding restrictions can disrupt the ability to obtain coverage and, in turn, fund a Florida purchase. Leaving the binder until the final morning creates a dependency that scheduling alone cannot resolve.
Ask the insurer how much time is needed to put the required coverage in place, and keep the lender informed of any unresolved insurance condition. If a restriction affects the planned closing, involve the closing agent and counsel promptly. The next step must reflect the executed agreement, not an assumption that weather automatically grants more time.
For a buyer weighing Opus against Four Seasons Residences Coconut Grove, this is a useful due-diligence consideration-not a claim about either project’s insurance arrangements. Establish the requirements applicable to the particular residence, lender, and contract.
For a financed purchase, reconcile the funds being sent with the final Closing Disclosure, not an earlier estimate. For a cash purchase, use the settlement statement supplied at or before closing, often in HUD-1 or ALTA format. In either case, obtain the actual breakdown from the closing agent.
Distinguish deposits already paid, the remaining purchase balance, fees, insurance premiums, credits, and prorations. Confirm that deposits appear correctly and that each adjustment is reflected in the final amount requested. Ask for an explanation of any differences between the final document and earlier figures before authorizing the transfer.
A useful reconciliation does more than check the bottom line. It establishes why that figure is correct and which amounts have already been satisfied. Have the closing agent explain how the settlement entries produce the requested wire amount, including the treatment of any insurance payment already made.
Buyers comparing Park Grove Coconut Grove with Opus should apply the same discipline without assuming identical charges or settlement procedures. The relevant figure is the amount established for the individual transaction, not a fee expectation borrowed from another purchase.
A wire initiated on closing morning may not arrive or be verified in time for same-day completion. Obtain the closing agent’s latest acceptable receipt time in advance, and coordinate the transfer schedule with the sending bank.
When the closing agent permits it, sending funds at least one business day before closing reduces last-minute timing risk. Independently confirm receipt using a trusted telephone number. A transfer confirmation from the sending bank and confirmation of receipt by the closing agent answer different questions; the closing plan needs both.
Before signing day, ask who will confirm that buyer funds are received and collected, whether the lender’s funding conditions are satisfied, and whether all required documents have been delivered. A scheduled appointment is not a substitute for verified readiness.
Ask counsel and the closing agent to confirm the agreement’s requirements for receipt and collection of funds and delivery of closing documents. Signing alone should not be treated as confirmation of completion when required funds remain outstanding. The executed Opus agreement and amendments determine the obligations for the particular purchase.
If funding stalls, identify the unresolved condition: insurance acceptance, receipt of buyer funds, lender funding, or required documents. Ask the responsible professional what remains outstanding and alert counsel if the contractual deadline is at risk. Any extension or other relief must be confirmed against the agreement; neither a delayed wire nor a lender problem should be treated as an automatic extension.
The final readiness check is straightforward: accepted insurance, reconciled settlement figures, confirmed funds, and delivered documents. Same-day funding should remain a coordinated objective, not a promise inferred from a scheduled signing.
For a discreet perspective on Coconut Grove residences and the decisions surrounding ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe project’s site address is 3137 SW 27th Avenue, Miami, FL 33133.
Review the executed purchase contract, amendments, and formal condominium disclosures. Oral representations should not replace the written documents.
For a financed purchase, it provides evidence that coverage will be effective at closing. The lender may require it before releasing funds.
A binder generally identifies the insured, property, coverage, effective date, deductibles, and lender mortgagee information.
Delivery alone does not establish acceptance. Confirm with the lender and closing agent that the required documentation is acceptable and any corrections are resolved.
Binding restrictions can disrupt obtaining coverage and mortgage funding. Begin insurance arrangements early and review any deadline implications with counsel.
Use the final Closing Disclosure rather than an earlier estimate. Verify deposits, remaining purchase balance, fees, premiums, credits, and prorations with the closing agent.
Cash transactions use a settlement statement provided at or before closing, often in HUD-1 or ALTA format. Obtain the actual breakdown from the closing agent.
No; the wire may not arrive or be verified in time. Establish the closing agent’s latest acceptable receipt time and confirm receipt independently.
No automatic extension should be assumed. Available relief and extension rights depend on the executed agreement and amendments.