A disciplined Aria Reserve Miami purchase separates construction deposits from association obligations, aligns liquidity with contract milestones, and tests reserve governance before closing.
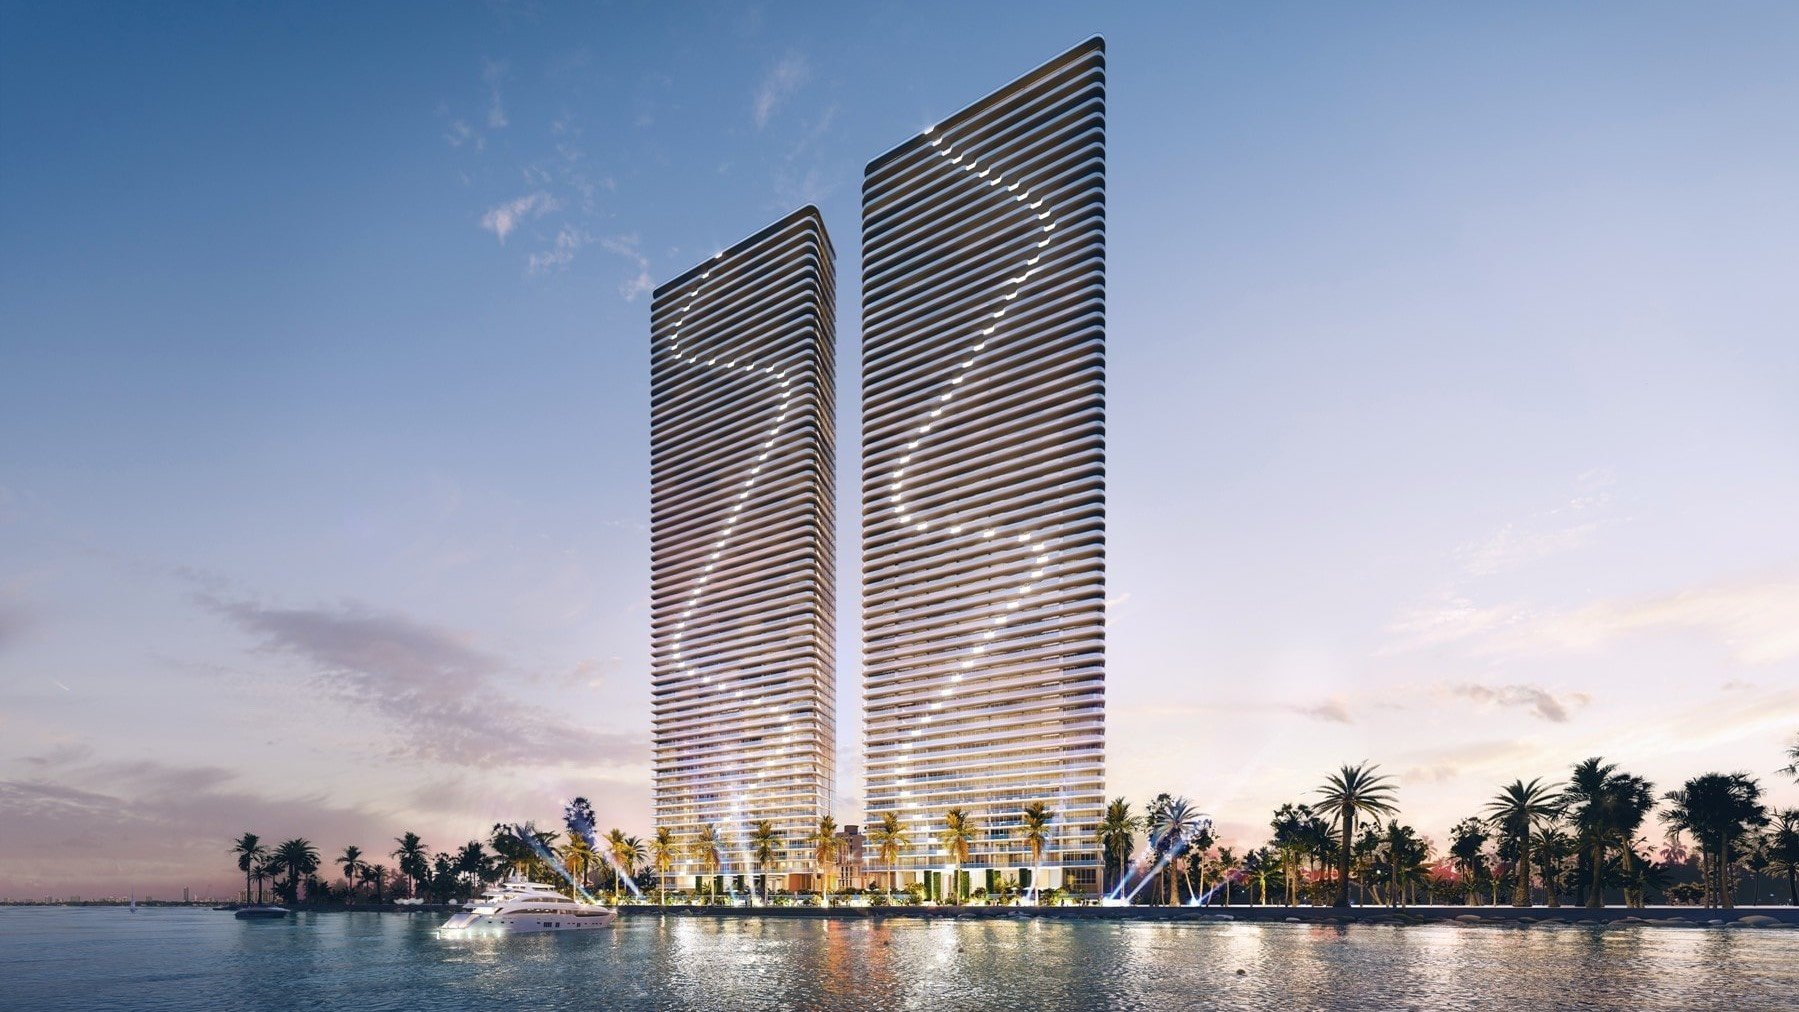
At Aria Reserve Miami, the financial transition from offer to ownership deserves the same attention as the residence itself. The twin-tower waterfront condominium development in Edgewater raises two distinct questions: when must the buyer fund the purchase, and how will the association fund its obligations once ownership begins?
Those questions belong on separate schedules. Construction deposits are purchase-price obligations under a contract. Condominium reserves and special assessments concern association obligations that may affect the buyer at closing or afterward. Treating them as one pool of capital obscures both timing and responsibility.
For a well-capitalized household, the objective is not simply to hold sufficient assets. It is to have funds accessible when the controlling documents require payment, without relying on an assumed delivery date or an unverified assessment estimate.
The indicative payment schedules illustrate materially different funding patterns. Neither replaces the executed purchase agreement and amendments.
The South Tower schedule calls for 20% at contract and 80% at closing. The North Tower schedule calls for 20% at contract, 5% at groundbreaking, 10% at the twentieth-floor pour, 5% at top-off and 60% at closing. That North Tower sequence totals 40% before closing, including 20 percentage points tied to construction milestones after the initial deposit.
The practical distinction is concentration versus staging. The South Tower schedule concentrates the remaining purchase price at closing. The North Tower schedule spreads additional payments across construction events while leaving a substantial closing balance. These indicative structures do not establish what remains payable on any particular residence today.
Before committing, have counsel reconcile the agreement, amendments, credited deposits, payment notices and outstanding balance. Identify the trigger for each remaining obligation and the notice required by the contract. A milestone label alone does not establish a future payment date.
The South Tower's receipt of a Temporary Certificate of Occupancy and entry into the closing phase were announced on August 19, 2025. That dated milestone is neither a current North Tower completion statement nor a substitute for a unit-specific closing notice.
Build the buyer's funding calendar around contractual obligations and written notices. Alongside the purchase-price balance, allow for applicable lender fees, title charges, prepaid assessments, escrows, and move-in or furnishing costs. Keep the closing calculation separate from the household's discretionary interiors budget, even if both draw on the same assets.
Second-home buyers should be particularly deliberate about separating acquisition cash from their ongoing ownership allowance. The question is not merely whether the residence can be purchased, but whether closing and subsequent obligations can be met without a rushed portfolio decision.
For buyers also considering EDITION Edgewater, apply the same comparison framework: contract deposits, closing requirements and association obligations in separate columns. Do not transfer Aria Reserve's indicative percentages to another project.
Association reserve liquidity is distinct from the buyer's personal liquidity. Evaluate a reserve balance alongside its intended uses, expected expenditure timing and accessibility. Reserve adequacy, investment rules and future capital-call dates require current association documentation-not assumptions based on the development's newness.
Request the reserve study and current reserve-account information, then ask for the governing investment policy. The questions should be specific:
Which investments are permitted, and what maturity limits apply?
Who may authorize transactions or act as an account signatory?
What liquidity requirements govern funds earmarked for upcoming expenditures?
Are reserve funds segregated from operating funds?
These are diligence questions, not descriptions of established Aria Reserve policies. Request written answers and supporting documents rather than relying on a general assurance that funds are professionally managed.
Review the policy alongside the expenditure schedule. A balance alone does not establish whether funds will be accessible when planned work requires payment. The buyer's adviser should examine both the amount designated for reserves and the controls governing its use.
The approximate association fee of $0.70 per square foot per month is not a verified current assessment or a reliable measure of post-turnover costs. Use the current adopted budget and the residence's applicable assessment information for underwriting.
Request the declaration, bylaws, current budget, actual financial statements, reserve study, insurance declarations, recent meeting minutes and estoppel certificate. Read them together. The budget sets out planned income and expenditure; financial statements and association records help test that plan against actual activity and documented decisions.
Confirm whether the residence owes assessments to a tower association, a master association or both. That structure remains a transaction-level diligence question. It determines which budgets, reserve accounts and notices apply.
The same document discipline is useful when evaluating Villa Miami as an alternative. A meaningful comparison requires each property's own obligations and governing documents-not an assumption that a shared neighborhood creates comparable carrying costs.
A construction deposit and a special assessment may both require substantial cash, but their legal foundations differ. Keep purchase-contract payments separate from association funding decisions throughout the review.
For any approved or pending special assessment, request written information on its purpose, amount, payment schedule and allocation to the residence. Do not divide a building-wide figure equally among units. The condominium documents and the unit's applicable ownership share determine the relevant allocation.
Before closing, also request written information concerning litigation, insurance claims, unpaid assessments, warranties and developer credits. Read the estoppel alongside the latest budget and association correspondence; it is not a standalone answer to every financial question. Have counsel identify responsibility for obligations that overlap the closing date.
Establish the building's milestone-inspection and Structural Integrity Reserve Study status directly. Generic Florida condominium requirements do not establish Aria Reserve's current obligations, inspection timetable or future assessment calendar.
Before releasing closing funds, refresh the documents most likely to affect the decision: the closing statement, applicable assessment information, estoppel and recent association correspondence. Reconcile any changes with the purchase agreement and the buyer's funding plan.
The standard is straightforward: know what is contractually due, understand what the association documents establish, and retain flexibility for obligations whose amount or timing remains unconfirmed. A polished residence and a disciplined ownership plan should complement one another.
For a discreet perspective on South Florida condominium ownership, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe indicative schedule specifies 20% at contract and 80% at closing. The executed purchase agreement and amendments determine the buyer's actual obligations.
It specifies 20% at contract, 5% at groundbreaking, 10% at the twentieth-floor pour, 5% at top-off and 60% at closing. Buyers should confirm which terms and remaining payments apply to their transaction.
It totals 40% before closing. That includes the initial 20% deposit and another 20 percentage points tied to construction milestones.
The August 19, 2025 milestone marked the South Tower's receipt of its Temporary Certificate of Occupancy and entry into the closing phase. It does not establish current North Tower completion.
No. Construction deposits satisfy purchase-contract obligations, while special assessments fund association obligations and may affect a buyer at closing or afterward.
Allow for applicable lender fees, title charges, prepaid assessments, escrows, and move-in or furnishing costs.
No. It is an approximate figure, not a verified current or post-turnover assessment; use current association documents for underwriting.
Request permitted investments, maturity limits, liquidity requirements and account-signatory controls. Also confirm whether operating and reserve funds are segregated.
Use the condominium documents and the unit's applicable ownership share. An equal division among residences is not a reliable substitute.
Review the declaration, bylaws, current budget, financial statements, reserve study, insurance declarations, recent meeting minutes and estoppel. Request written information about assessments, litigation, claims, warranties and developer credits as well.