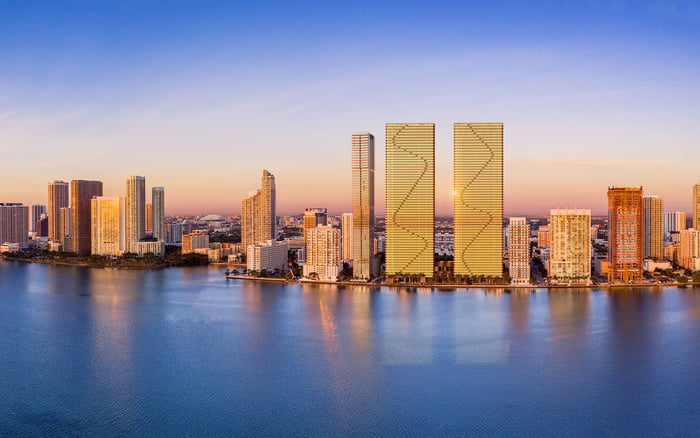
A Greenwich-to-Edgewater move calls for more than a property selection. Align permanent-residence evidence and ownership decisions while keeping banking, entity reporting and closing instructions transaction-specific.
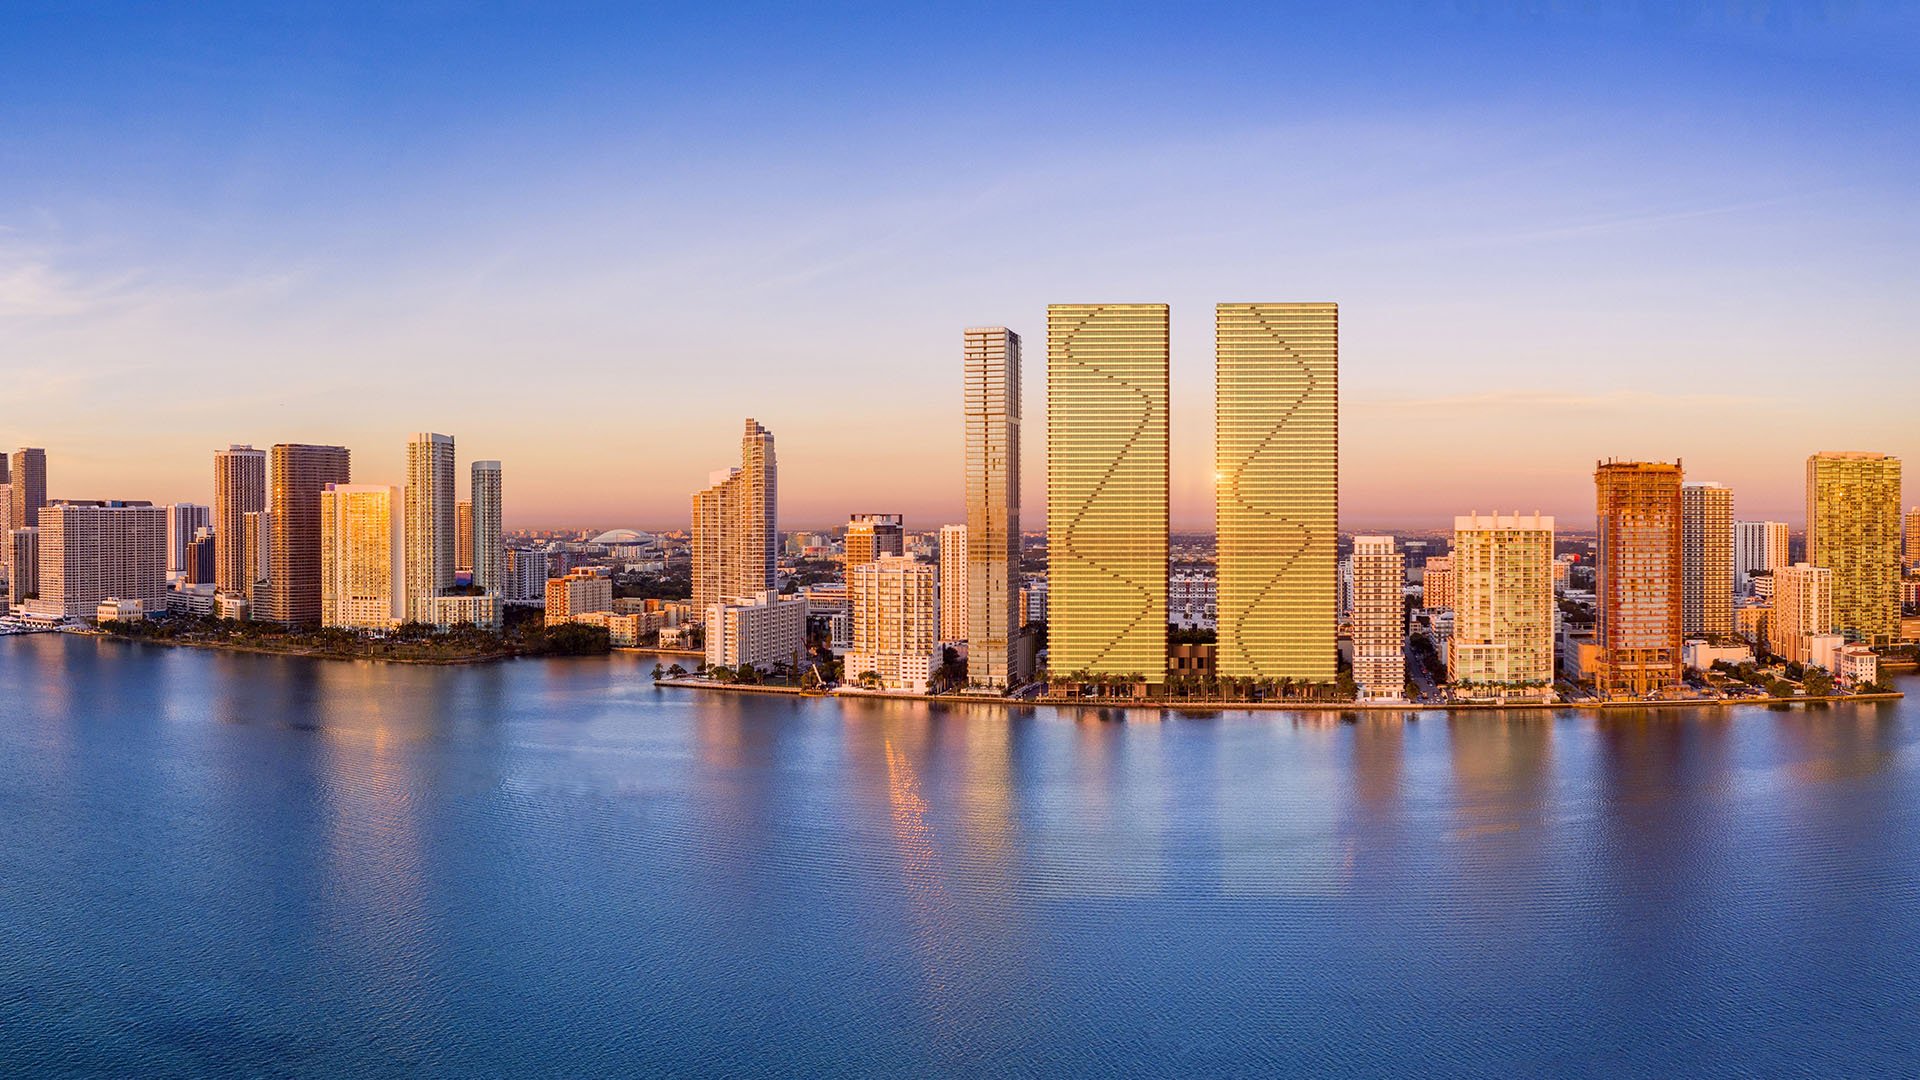
A move from Greenwich to Edgewater begins with two decisions: which residence deserves a place in your life, and how it will fit into your legal and financial affairs. A compelling address answers the first question. It does not, by itself, answer the second.
For a buyer considering Aria Reserve Miami, intended use is the starting point. Will the property become a permanent residence, remain an occasional retreat, or serve an investment objective? That distinction should guide conversations about ownership, residence evidence and transaction administration before assumptions take hold in the purchase plan.
The central discipline is separation. Homestead eligibility, departure-state residency, beneficial-ownership reporting and a bank’s transaction requirements are distinct questions. A document relevant to one should not be assumed to resolve the others.
Miami-Dade homestead eligibility generally requires legal or equitable title to the property as of January 1. The property must also be maintained as a permanent residence as of that date. Ownership alone does not satisfy the residence requirement.
For a relocating household, the planning question is more precise than when the purchase will close: when will both the ownership and permanent-residence conditions be satisfied? The purchase calendar should reflect that distinction, rather than treating the acquisition date as a universal residency milestone.
January 1 is an eligibility reference point here, not a filing deadline. Confirm the applicable filing timetable and full eligibility requirements for the intended year before relying on an anticipated exemption.
At the state level, homestead relief may be available when the property is the permanent residence of the owner or the owner’s dependent. That broader description still calls for an individual eligibility review, especially when the relationship between the intended ownership arrangement and the person occupying the home is not straightforward.
Proof of utility payments at the property and a recorded Declaration of Domicile are among the forms of evidence recognized in Miami-Dade’s permanent-residence framework. Neither substitutes for the underlying requirement that the property be maintained as a permanent residence.
The objective is a coherent record of actual circumstances, not simply a collection of documents. For a household moving between homes, ask advisers how the intended living arrangement should be evaluated and documented. Keep the distinction between evidence and qualification clear.
The same reasoning applies when evaluating EDITION Edgewater. The residence selection and the residence record should tell the same story. A purchase motivated by occasional use should not quietly become a permanent-residence assumption in the financial plan.
A Declaration of Domicile belongs within that broader assessment. Recording it can contribute evidence, but should not be described as independently settling every residence or tax question associated with a move.
Florida homestead qualification should not be treated as establishing that tax residency elsewhere has ended. For a Greenwich household planning an Edgewater move, the departure side requires separate advice-not a conclusion inferred from a Florida property purchase.
The value of the exemption requires an equally important distinction. Homestead relief reduces taxable value rather than providing an equivalent dollar-for-dollar reduction in the tax bill. Confirm the applicable exemption amount and its treatment for the intended tax year before incorporating savings into the ownership budget.
A measured financial plan should not translate a taxable-value reduction into a promised dollar saving. The purchase decision should stand on its residential merits, with the applicable tax treatment evaluated separately. A desirable home should not be justified by a benefit that has yet to be established for the buyer.
Before choosing an ownership structure for an Edgewater residence, ask counsel to confirm whether Corporate Transparency Act beneficial ownership information, or BOI, reporting obligations apply under the rules in effect for the transaction. Have counsel distinguish the treatment of U.S.-created and foreign-formed entities rather than relying on an assumed reporting position.
A reporting conclusion is not a recommendation to acquire a residence through a particular entity. Nor does the absence of a BOI filing obligation fully answer questions about ownership documentation, bank acceptance or homestead eligibility.
Ask counsel to distinguish the entity’s reporting position from the intended residence treatment and to identify the ownership and authority documents appropriate to the proposed structure. Keep that legal review separate from the bank’s confirmation of what it will accept for the transaction.
A U.S. banking plan should begin by confirming directly what the selected institution needs for the proposed transaction. Do not assume that a residence-evidence file or a BOI conclusion also serves as an accepted source-of-funds file.
Rather than relying on a generic document bundle, ask the bank to define its expectations for the particular buyer, ownership arrangement and funds involved. Ask counsel which entity documents are appropriate to that structure. Resolve these questions with the parties handling the transaction; do not infer universal requirements from the property selected.
For wire controls, request verification and authorization procedures from the bank and closing professionals before funds are scheduled to move. The principle is straightforward: transaction-specific instructions should come from the responsible parties, not from assumptions carried over from another purchase.
A buyer weighing Villa Miami may still be deciding how fully to relocate. Preserve that uncertainty in the planning discussion rather than presenting a future intention as an established residence fact.
Second-home use, permanent residence and investment intent should each be discussed on their own terms. None should be inferred from the scale of the purchase or the sophistication of the ownership structure.
The strongest residence strategy aligns the chosen home with actual use, separately assessed tax questions and clearly assigned transaction responsibilities. Treat this as a planning framework, not individualized legal, tax or banking advice.
Explore an Edgewater residence strategy shaped around your priorities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Miami-Dade generally requires legal or equitable title and maintenance of the property as a permanent residence as of January 1.
It is the reference date for the stated title and permanent-residence conditions. It should not be confused with the homestead filing deadline.
Proof of utility payments at the property and a recorded Declaration of Domicile are among the recognized forms of evidence. They are not a complete eligibility checklist.
No. It can support permanent-residence evidence, but it should not be treated as independently resolving every residence or tax issue.
No. It reduces taxable value rather than providing an equivalent dollar-for-dollar tax saving; confirm the applicable amount and treatment for the intended year.
Yes. An owner may qualify when the property is the permanent residence of the owner or the owner’s dependent, subject to the applicable eligibility requirements.
It should not be treated as resolving tax residency elsewhere. An Edgewater relocation requires separate advice on departure-state obligations.
Ask counsel to confirm the rules in effect for the transaction and how they apply to the proposed entity. Do not treat that conclusion as resolving bank documentation or homestead eligibility.
Ask counsel to identify the documents appropriate to the ownership structure and authority to act. Separately ask the selected bank to confirm its acceptance requirements.
Ask the selected bank and closing professionals to confirm transaction-specific documentation, verification and authorization expectations. Do not assume residence evidence or a BOI conclusion satisfies those expectations.