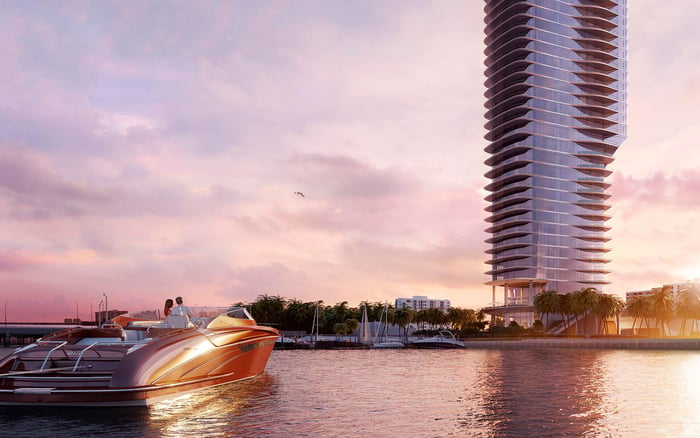
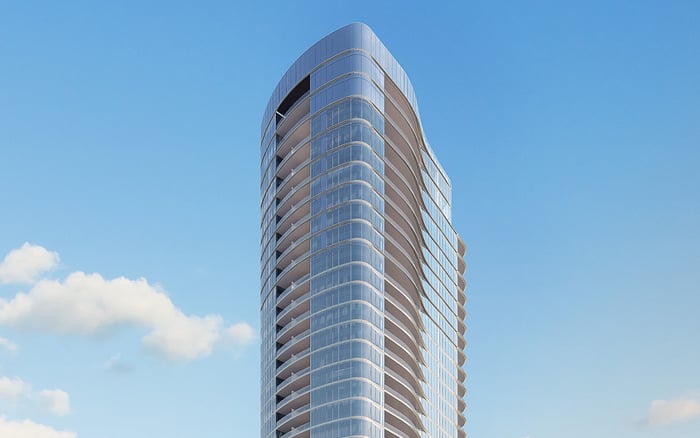
2200 Brickell’s reported temporary occupancy milestone shifts the buyer’s focus toward execution. Lender acceptance, insurance coverage, contract deadlines, and move-in authorization should align before funding, without confusing a TCO with final completion.
For buyers considering 2200 Brickell, the next question is not simply whether a residence is available. It is whether the building’s occupancy authorization, the buyer’s financing, and the arrangements for taking possession align. At this stage, a clear closing calendar matters as much as the residence itself.
By July 29, 2026, the five-story condominium at 2200 Brickell Avenue in Miami’s Brickell neighborhood was reported to have received a Temporary Certificate of Occupancy, or TCO, and begun welcoming residents. By July 30, closings were described as underway following the City of Miami’s issuance of the TCO. These dates mark a reported delivery milestone; they do not establish the exact municipal issuance date.
For buyers, that distinction matters: occupancy permission, loan funding, insurance readiness, and a confirmed move-in appointment are separate matters. None should be inferred from an announcement that delivery has begun.
A TCO permits occupancy before final completion and is distinct from a final certificate of occupancy. Residents may be able to move in while noncritical work and final inspections continue. Temporary occupancy does not mean the building is uninhabitable, nor does it prove that every element of delivery is complete.
Scope matters, too. A TCO can authorize an entire building or only part of it. Before planning occupancy, request the applicable certificate and have the relevant professionals confirm that it covers the intended residence and the access needed for move-in.
A TCO announcement is not confirmation that a final certificate of occupancy has been issued. The useful question is what the current authorization permits for this purchase-not what the milestone suggests in general.
Remaining inventory should not automatically be treated as a purchase with a distant construction horizon. With delivery activity underway at 2200 Brickell, buyers should establish the current certificate status and proposed closing schedule before relying on an earlier estimated completion date.
For someone also considering Una Residences Brickell, the comparison should include a separate review of documents and timing for each purchase. A neighborhood shortlist does not establish a shared delivery stage, financing path, or move-in window.
Ask counsel to review the purchase agreement’s closing provisions alongside its deposit and escrow terms. TCO issuance can bring closing preparations forward, but it does not automatically accelerate every buyer’s obligations. Its effect depends on the agreement and the notices applicable to that transaction. A careful contract review is more useful than a general expectation about how new condominiums close.
Some conventional lenders accept closings under a TCO. Acceptance varies by lender and loan product, however, so general willingness to finance a condominium does not settle the occupancy-certificate question.
Before applicable contract deadlines, obtain written confirmation that the lender accepts a TCO closing for the intended loan. Ask what remains necessary for funding, including any required project documentation. The distinction is critical: acceptance of the certificate type is not the same as readiness to release funds on the scheduled date.
This is general closing guidance, not confirmation that a particular loan at 2200 Brickell has been approved. The buyer’s financing position must be established through the lender’s review of the transaction.
The timing risk is straightforward: a closing schedule can advance while loan approval or required documentation remains pending. Aligning the lender, counsel, and title company on one timetable helps identify that mismatch before it becomes urgent.
Insurance warrants a parallel review, not a last-minute administrative step. Confirm the association’s insurance status, then establish the requirements for the buyer’s unit policy during the TCO period. Ask the insurer whether occupancy status or building-system readiness affects the coverage it is prepared to provide.
A TCO alone does not establish the terms of the association’s coverage or mean that coverage is provisional. Those answers require the actual insurance documentation and the insurer’s confirmation.
Before funding, ask the insurance professional to confirm when the required unit coverage will take effect and whether outstanding information could affect that timing. Coordinate those answers with lender and title-company requirements. Coverage requirements, policy effective dates, and intended occupancy should align; one approval does not resolve all three.
A residence can reach an occupancy milestone without every buyer having a confirmed moving date. Before scheduling deliveries or making relocation commitments, obtain the exact move-in window and clarify the association’s readiness to receive residents.
Ask which delivery conditions remain outstanding and whether remaining work affects the intended use of the residence. Noncritical work may continue under a TCO, so the question is not simply whether work remains, but how it affects the buyer’s occupancy arrangements.
For a household weighing The Residences at 1428 Brickell alongside 2200 Brickell, this distinction is useful without implying equivalent certificate status. Evaluate the proposed ownership date and intended occupancy date separately for each transaction. A preferred residence still needs a workable transition plan.
Cash buyers avoid lender-funding requirements, but not occupancy, insurance, or contractual considerations. Before funding, they should still confirm association readiness, delivery conditions, title-company requirements, and precise move-in arrangements.
Without a lender, the buyer’s own coordination becomes especially important. Ask counsel and the title company what documentation they need, confirm insurance readiness independently, and ensure that the closing timetable reflects the agreement rather than an informal delivery estimate.
For cash and financed buyers alike, a concise written closing checklist can consolidate these confirmations. It should identify the certificate applicable to the residence, unresolved funding or documentation items, coverage timing, contractual deadlines, and the authorized move-in window.
The reported TCO milestone at 2200 Brickell makes delivery-stage diligence central to the purchase decision. It does not replace lender approval, insurance confirmation, contract review, or move-in authorization.
The strongest preparation is to bring those answers together before funding, with responsibility for each open item clearly assigned. Buyers can then assess not only the residence’s appeal, but also the certainty of the transition into it.
For a discreet conversation about evaluating your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA Temporary Certificate of Occupancy and the arrival of residents were reported by July 29, 2026. By July 30, closings were described as underway.
That date establishes when the milestone was reported, not the exact municipal issuance date. Buyers should confirm issuance details through the applicable certificate.
No. A TCO permits occupancy before final completion and is distinct from a final certificate of occupancy.
Yes. Buyers should confirm that the authorization covers their intended residence and the access needed for occupancy.
No. Some conventional lenders accept a TCO, but requirements vary by lender and loan product.
Obtain written confirmation that the lender accepts the intended TCO closing. Separately confirm which funding requirements remain outstanding.
Confirm association insurance status and unit-policy requirements, including any insurer conditions related to occupancy or building-system readiness. Verify coverage timing before funding.
No. It can bring closing preparations forward, but its effect on deadlines depends on the purchase agreement and applicable notices.
Residents may move in under a TCO while noncritical work and final inspections continue. Buyers should verify the scope of authorization and their specific move-in window.
Cash buyers still need to confirm insurance, association readiness, delivery conditions, title-company requirements, and move-in timing. Avoiding lender requirements does not replace those checks.