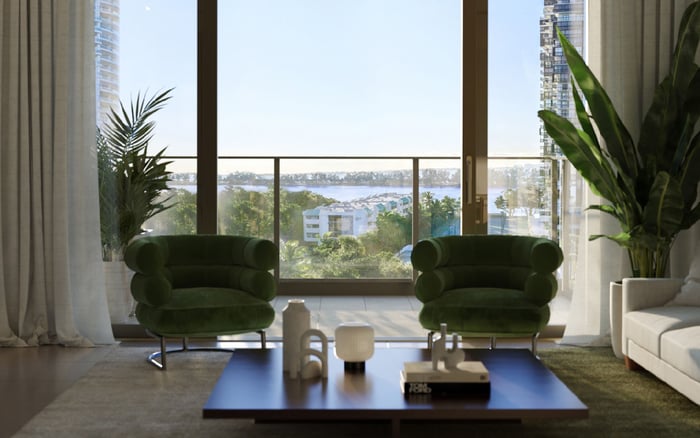
2200 Brickell specifies floor-to-ceiling impact-glass windows, but future claims depend on more than that description. Buyers should distinguish product approvals, written warranties, condominium maintenance duties and casualty insurance before closing.
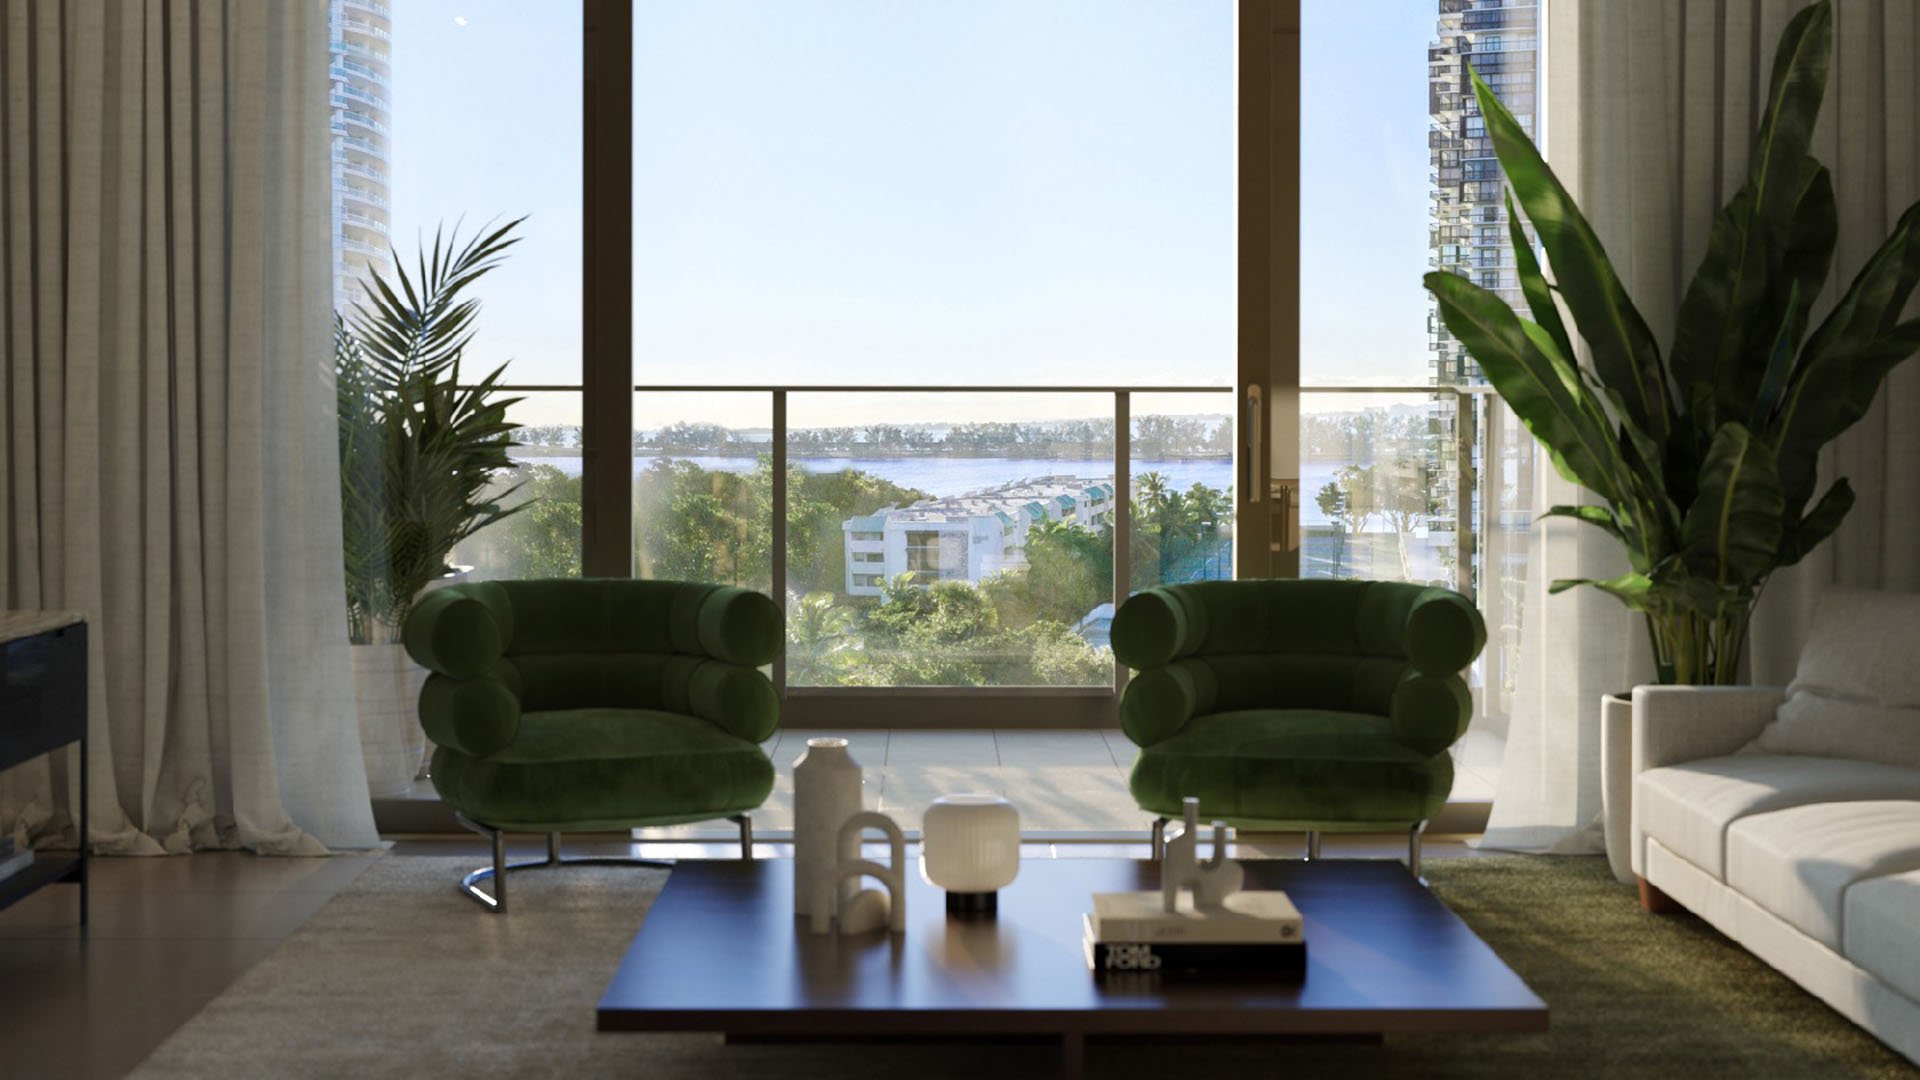
For a buyer considering 2200 Brickell, floor-to-ceiling glazing is both an architectural feature and an ownership consideration. Floor-to-ceiling impact-glass windows and sliding glass balcony doors are advertised features. Those descriptions do not, by themselves, establish a remedy if a window later leaks, a component deteriorates or glass sustains damage.
The essential distinction is between four questions: what product was installed, what approvals apply, what a written warranty covers and who bears responsibility under the condominium documents and insurance arrangements. A satisfactory answer to one does not settle the others. Impact-glass certification is not a warranty, and neither guarantees that an insurer will pay a future claim.
For a luxury purchase, this is less about anticipating failure than preserving clarity. The documentation deserves the same careful consideration as the view.
The advertised specification does not establish the installed manufacturer, a Florida product-approval number, a Miami-Dade Notice of Acceptance, tested pressure ratings or actual warranty terms. Buyers should request those details rather than treat “impact glass” as a substitute for them.
Request the window schedule, applicable product approvals and installation records together. Have a qualified professional compare the installed products with those documents and assess the applicable installation requirements. An approval document alone does not confirm that every installed opening complies.
Written warranties answer a different set of questions. Request the developer and manufacturer warranties, and identify whether each addresses glass, seals, frames, hardware or installation. Ask who may submit a claim, which party receives notice, what deadlines apply and which exclusions could affect a remedy. Do not assume a particular warranty duration for this building without reviewing the governing language.
If your Brickell shortlist also includes The Residences at 1428 Brickell, ask the same document questions there. This is a comparison framework, not an assumption that the projects share products, approvals or coverage.
The obligation to insure a window is distinct from the obligation to maintain it. Association property insurance does not automatically make every adjustment, leak investigation or replacement an association expense.
For ordinary maintenance and replacement, begin with the condominium declaration. Windows may be classified as unit property, common elements or limited common elements. That classification matters, but it must be read alongside provisions expressly assigning maintenance and replacement duties. Association maintenance of common elements provides a general statutory baseline, not a complete answer for every window.
Read unit boundaries, window clauses and exterior-alteration restrictions together. A clause assigning replacement to an owner may interact with restrictions on changing the building’s exterior. Depending on the governing documents, those restrictions can affect an otherwise express owner obligation. They do not establish a universal exemption for owners.
These are general condominium-law principles, not a determination of this building’s obligations or a verification of current statutory language. Before closing, ask Florida condominium counsel to review the governing documents against current law, especially where responsibility and authority appear to diverge.
Sliding glass balcony doors belong in the same diligence file, but their coverage should not be inferred from the window specification. The advertised door specification does not establish their manufacturer, product-approval number or warranty term.
Ask that the product schedule and written warranties identify the door systems as well as the windows. For each, clarify whether glass, seals, frames, operating hardware and installation are covered, and whether different parties handle different components. A broad verbal assurance about “the glazing” is less useful than a written answer tied to the relevant product.
The declaration review should also address the doors specifically. Do not assume that an allocation applying to a window answers every question about a balcony opening. The objective is to know both who must act and whose approval is needed before work begins.
Consider three hypothetical situations, not identified conditions at 2200 Brickell. Each calls for a different document review rather than pointing to a predetermined payer.
A seal or hardware concern:
Start with the written warranty and the declaration’s maintenance provisions. Determine whether the component and claimed condition fall within coverage, who can make the claim and whether notice remains timely. Warranty eligibility and maintenance responsibility are separate inquiries.
Wear, corrosion or a leak unrelated to an insurable casualty:
The responsibility question generally returns to the declaration. The existence of association insurance does not resolve who must maintain or replace the affected window or door.
Damage from an insurable casualty:
Association casualty-repair rules generally become relevant. Developer-installed windows and sliding glass doors generally fall within the original-condominium-property insurance framework, subject to applicable law and coverage. That framework also addresses like-kind-and-quality replacements tied to original plans and specifications. Insurance proceeds and common expenses may fund repairs without eliminating owners’ financial exposure.
In each situation, avoid choosing a claim route solely from the appearance of the damage. Seek an assessment of the condition, then review the relevant warranty, declaration and policy provisions.
A subsequent purchaser should not assume that a warranty available to the original buyer continues unchanged. Request any resale-transfer provisions, identify the eligible claimant and confirm whether a transfer requires notice or other steps. The answer must come from the actual warranty, not a general expectation about new construction.
For buyers weighing Una Residences Brickell alongside 2200 Brickell, keep each property’s documentation separate. A clear warranty package for one residence says nothing about the contractual protection attached to another.
Preserve the advertised specifications alongside the installed-product records. Keep a record of the advertised impact-glass feature, but do not treat it as a substitute for the written warranty or proof of the installed system’s approval status.
Before closing, assemble the window and door schedules, applicable approvals, installation records, developer and manufacturer warranties, declaration and master-policy summary. Ask your advisers to identify unresolved responsibilities and notice requirements in writing.
Keep that file accessible throughout ownership. If a concern develops, it provides a starting point for identifying the product, the responsible party and the applicable claim procedure. It is more useful than relying on a remembered promise of “impact glass.”
A considered purchase rests not on the broadest reassurance, but on specifications, warranties, maintenance obligations and insurance arrangements that can be read distinctly and understood together.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationFloor-to-ceiling impact-glass windows are an advertised residence feature. That description alone does not establish the installed product’s approvals or warranty coverage.
Sliding glass balcony doors are an advertised feature. That description does not identify their manufacturer, product-approval number or warranty term.
No. Product approvals and written warranty coverage address different questions, and neither guarantees payment of an insurance claim.
Request the window and door schedules, applicable product approvals and installation records. Have a qualified professional compare them with the installed systems.
They should clarify coverage for glass, seals, frames, hardware and installation, along with the eligible claimant, notice deadlines and exclusions. Buyers should also check any resale-transfer requirements.
No universal allocation should be assumed. Read the declaration’s property classifications and express maintenance and replacement duties together.
No. The duty to insure is distinct from the duty to maintain, so association insurance does not automatically make ordinary repairs association expenses.
Damage from an insurable casualty generally follows association casualty-repair rules, subject to applicable law and coverage. Non-casualty wear, corrosion, leaks and hardware issues generally return the responsibility question to the declaration.
They can affect how an owner’s replacement obligation operates, depending on the governing documents. Buyers should have counsel read those restrictions alongside unit boundaries and window-maintenance clauses.
No. Review the actual warranty to establish whether it transfers, who may claim and whether notice or other transfer steps are required.