At Jade Ocean, the condominium questionnaire offers a framework for evaluating reserves, insurance, litigation and the financing conditions that can influence a future resale. The essential distinction is between collecting association information and obtaining a written lender determination.
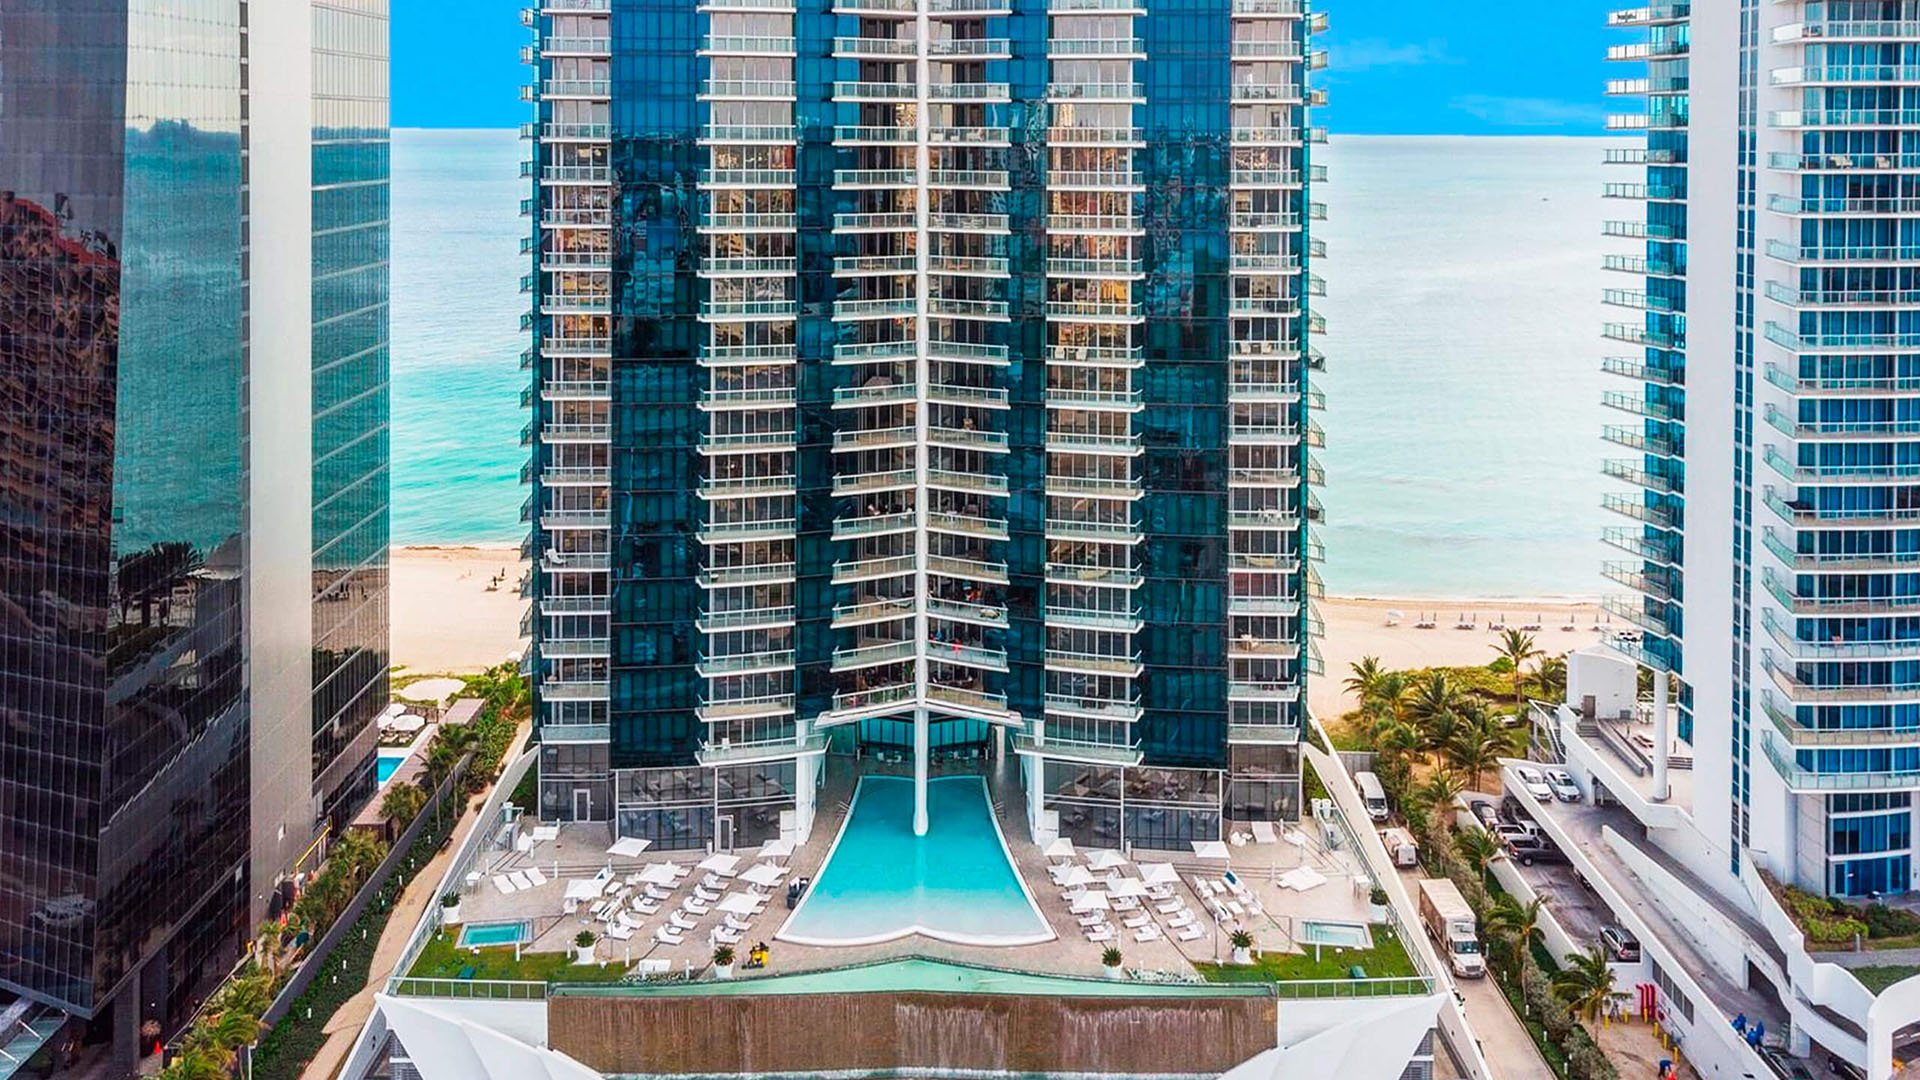
At Jade Ocean Sunny Isles Beach, a 2009 oceanfront condominium at 17121 Collins Avenue, the purchase decision extends beyond the residence itself. For buyers evaluating long-term ownership, the association's financial and legal position warrants attention alongside the property's setting. The condominium questionnaire brings those less visible considerations into a format a lender can evaluate.
The distinction matters: a questionnaire gathers information; it does not confer approval. Its answers can illuminate reserves, insurance, payment delinquencies, litigation and ownership concentration. Whether those answers satisfy a particular financing program requires a lender's project review. For an owner considering a future sale, that review raises another question: how accessible might financing be to the next buyer?
Form 1076 is an optional condominium-project questionnaire; lenders may use substantially similar forms. It collects project-level information relevant to eligibility. Read it as an organized disclosure document, not a certificate of financial strength or structural condition.
For Jade Ocean, the task is to connect each material answer to supporting documentation. Read reserve disclosures alongside the financial package and reserve study. Check insurance answers against current coverage documents. An affirmative litigation response calls for the underlying explanation, not an immediate assumption that financing is unavailable.
Requesting a questionnaire is only the beginning. Buyers should distinguish among an order placed, a completed response delivered and a written lender determination issued. These are separate milestones. Neither a request service nor an association's delivery of paperwork establishes current approval.
The same discipline applies when comparing Jade Signature Sunny Isles Beach: shared branding is no substitute for separate association records or a project-specific financing decision.
A reserve account's existence answers only the first question. More consequential is whether its balance and contribution schedule appropriately reflect identified obligations. Buyers should request the structural integrity reserve study, the current reserve-funding percentage and three years of association-dues history.
Read those documents together. An account balance describes available funds; a funding percentage places reserves in relation to the obligations being measured. Neither should be interpreted without its date, scope and supporting assumptions. The questionnaire can flag these issues, but it does not replace a close reading of the underlying study.
Dues history also requires context. Separate increases attributable to reserve contributions from those attributable to insurance premiums. Both affect carrying costs, but they explain different uses of association funds. A larger bill alone establishes neither reserve adequacy nor financial weakness.
Then examine assessments levied, pending or discussed in board meetings during the preceding 24 months. An adopted charge is distinct from a discussion. Ask for the purpose, status and payment terms of each relevant item rather than treating every reference in the minutes as an established liability.
Insurance diligence should address replacement-cost coverage and the funding of hurricane or named-storm deductibles. The practical ownership question is not simply whether a policy exists, but how the association would meet the deductible: through reserves, an assessment or another documented arrangement.
Here, the questionnaire and lender review should converge. Ask the lender to address insurance in its written project-eligibility determination. Do not assume that an attractive residence, a strong personal balance sheet or a larger down payment resolves a project-level eligibility concern.
Litigation requires equal precision. Form 1076 asks about active or pending HOA litigation and requests documentation from the attorney or association, together with attorney contact information. Disclosure prompts review, not automatic rejection. Historical disputes involving a developer should not be treated as evidence of the association's present litigation status.
Payment delinquencies and ownership concentrations deserve separate review. Ask for current figures and the lender's interpretation rather than drawing conclusions from the building's reputation. These are questionnaire subjects, not established findings about Jade Ocean's current operations.
The connection between project eligibility and resale liquidity is straightforward, but should not be overstated. If financing restrictions reduce the number of buyers able to obtain suitable loans, the financed-buyer pool can narrow. That possibility matters even to someone purchasing without a mortgage today.
It does not establish that Jade Ocean currently faces such restrictions, nor does it demonstrate a particular effect on price or time to sell. A disciplined acquisition analysis keeps those propositions separate. Current lender appetite must be established through an actual review; future liquidity depends on conditions at the time of resale.
For a buyer also considering Armani Casa Sunny Isles Beach, the comparison should apply the same documentation questions without presuming equivalent reserves, insurance or eligibility. Architectural preference and financing access belong in the same decision, but neither can stand in for the other.
The questionnaire is not a complete ownership budget. Obtain the charges applicable to the specific residence, then distinguish ordinary dues from assessments and other documented obligations. Building-wide cost ranges cannot replace a unit-specific statement.
Leasing assumptions also warrant verification. Buyers should verify Jade Ocean's stated six-month minimum lease term against current association documents before relying on rental flexibility. This is particularly relevant when an ownership plan combines personal use with leasing.
The objective is to understand how carrying costs, permitted use and financing access relate. Together, these considerations help buyers evaluate a purchase without turning an unverified operating assumption into an investment premise.
Bring the questionnaire, financial package, reserve study, insurance documents, relevant minutes and litigation explanations into one coordinated review. Before wiring funds, ask the lender to identify unresolved project questions and provide a written eligibility determination addressing reserves and insurance. Confirm the determination's scope rather than treating it as an unlimited assurance.
For Jade Ocean, the strongest conclusion is neither a blanket endorsement nor a warning inferred from incomplete disclosures. It is a documented understanding of the association, the chosen financing path and the obligations attached to the residence. That is the foundation for a more deliberate purchase and a better-informed view of future resale.
For a discreet perspective on South Florida condominium ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationJade Ocean is a 2009 oceanfront condominium at 17121 Collins Avenue in Sunny Isles Beach, Florida.
It gathers project-level information about reserves, insurance, association-payment delinquencies, litigation and ownership concentrations for lender review.
Form 1076 is optional, and lenders may use substantially similar questionnaires to collect project information.
No. A completed questionnaire supplies information for review; project eligibility requires a lender determination.
Request the structural integrity reserve study, current reserve-funding percentage and reserve balance. Read them alongside three years of association-dues history.
Review assessments levied, pending or discussed in board meetings during the preceding 24 months. Distinguish adopted charges from matters still under discussion.
Confirm replacement-cost coverage and how hurricane or named-storm deductibles would be funded. Ask the lender to address insurance in its written project determination.
No. Litigation disclosure requires review of the circumstances and supporting documentation, not an automatic conclusion that financing is unavailable.
Financing restrictions can narrow the pool of financed buyers at resale. That conditional relationship does not establish a specific price or sale-time effect for Jade Ocean.
A six-month minimum lease term is cited for Jade Ocean. Confirm it against current association documents before building an ownership plan around rental income.