For buyers moving from another Florida homestead to Forté on Flagler, Save Our Homes portability may reduce the new residence’s assessed value by up to $500,000. The opportunity depends on eligibility, valuation and a January 1-based timetable, not simply the sale closing date.
Moving from an established Florida homestead to Forté on Flagler West Palm Beach involves more than comparing square footage and waterfront addresses. For an owner with a substantial Save Our Homes assessment difference, the transition raises a separate question: how much of that benefit can follow the move?
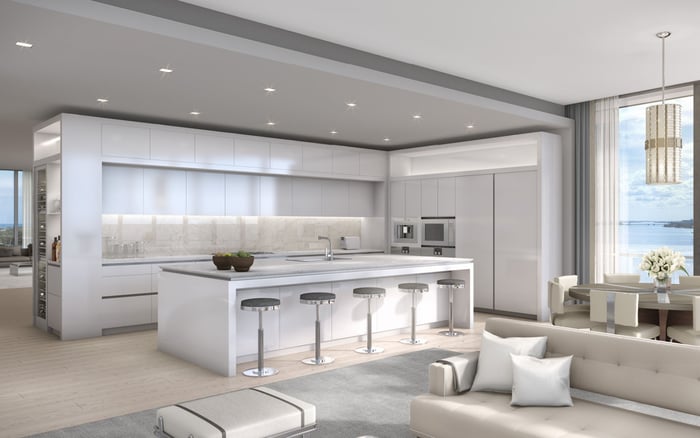
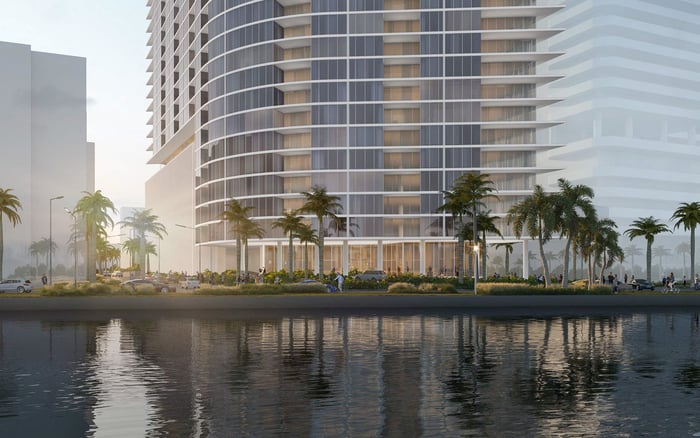
Forté is a 25-story, 41-residence condominium at 1309 South Flagler Drive, directly on the Intracoastal Waterway. Its development and design team includes Two Roads Development, Alpha Blue Ventures, Arquitectonica and interior designer Jean-Louis Deniot. Residence sizes range from approximately 4,200-5,000 square feet, with larger offerings of approximately 6,500-8,400 square feet.
Selected residences are marketed from approximately $14.7 million and full-floor offerings from approximately $20 million. Those figures are neither verified transaction prices nor property-tax assessments. For a buyer considering an eight-figure residence, the distinction matters: portability can improve the ownership budget, but it does not preserve an earlier home’s entire tax position.
Florida’s Save Our Homes limitation caps annual increases in a qualifying homestead’s assessed value at 3% or the change in the Consumer Price Index, whichever is lower. Over time, the difference between the property’s just value and its capped assessed value can become substantial.
That gap is the assessment difference. Portability allows an eligible homeowner to transfer part or all of it to a new Florida homestead, subject to a maximum of $500,000.
The ceiling applies to an assessment reduction, not a tax credit or cash payment. Even an owner with several million dollars in accumulated assessment difference cannot assume the entire amount will transfer to Forté.
A further distinction matters: Save Our Homes limits assessed-value growth, not the percentage increase in the total property-tax bill. A capped assessment is therefore not a promise that annual taxes will rise by no more than 3%.
Following a sale that constitutes a change of ownership, a homesteaded property generally loses the seller’s Save Our Homes protection and is assessed at just value the following January 1. A buyer should not assume that the existing capped assessment becomes the new owner’s tax base.
For Forté, the useful exercise is to estimate the residence’s just value, account for the buyer’s own eligible portability benefit, and then apply the relevant exemptions and tax rates. An advertised purchase price is not a substitute for the property appraiser’s valuation.
The same discipline applies to a comparison with Alba West Palm Beach. If both addresses are on a buyer’s shortlist, each ownership budget should reflect that residence’s valuation assumptions. One property’s historical tax bill should not serve as a comparable expense for another.
When the new homestead’s just value equals or exceeds the previous homestead’s just value, the owner can generally transfer the full assessment difference, subject to the $500,000 ceiling.
When the new residence has a lower just value, the transferable benefit is proportional and remains subject to the cap. It is not automatically the full difference accumulated at the former home.
For luxury buyers, this distinction can be counterintuitive. Moving from a large estate into a condominium may feel like downsizing, but the portability comparison turns on just value-not bedroom count, acreage or interior square footage. A smaller residence can still represent a move up in value. Establish both valuations before assuming which calculation applies.
Consider a hypothetical previous homestead with a $6 million just value and a $3 million capped assessed value. Its assessment difference is $3 million, but the maximum transferable amount is $500,000.
Now assume the Forté residence has a $15 million just value and the buyer qualifies for the full transfer. Portability would reduce the starting assessed value to $14.5 million before applicable exemptions.
At an assumed applicable ad valorem rate of 1.8%-2.0%, that $500,000 reduction would produce approximately $9,000-$10,000 in annual savings. These figures illustrate the arithmetic; they are not a Forté tax quote or a verified unit-specific rate.
Portability can provide meaningful recurring savings, but it remains a limited offset against the tax exposure of an eight-figure residence. A prudent budget models ownership both with and without the anticipated transfer, treating the benefit as conditional until eligibility and the amount are confirmed.
Portability requires Forté to qualify as the owner’s new Florida homestead. A purchase solely for second-home or investment use does not qualify. The residence’s intended role therefore belongs at the beginning of the purchase discussion, not at the end of closing preparations.
The same question matters if a buyer is weighing Shorecrest Flagler Drive West Palm Beach alongside Forté. Choosing a building does not replace the eligibility analysis: whichever residence is selected must qualify as the new homestead for portability to apply.
The new homestead exemption must be established within three years of January 1 of the year the former homestead was abandoned. This is not a rolling three-year period beginning on the sale closing date.
That distinction warrants individual review when a move involves an interim residence or a gap between selling and establishing the next homestead. A closing calendar alone does not establish that the portability timetable has been met.
Applicants must submit Form DR-501T, Transfer of Homestead Assessment Difference, with Form DR-501, the new home’s homestead application. March 1 is the standard filing deadline for the year in which the benefits are sought. Palm Beach County’s Property Appraiser administers homestead exemption and portability for a Forté residence.
Before relying on portability in the purchase budget, confirm the former homestead’s just value, capped assessed value and abandonment year. Then review the proposed new homestead’s eligibility, anticipated transfer amount and filing timetable with the appropriate advisers and local office.
Keep the rest of the ownership analysis separate. Request current residence-specific condominium charges and obtain a tax estimate with explicit valuation and rate assumptions. Neither marketing prices nor an assumed maximum transfer should substitute for that work.
Forté’s scale and waterfront setting frame the residential decision. Portability is best treated as a valuable but limited benefit that follows an eligible owner-not as a feature conveyed with the condominium.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationPortability allows an eligible owner to transfer an accumulated assessment difference from a previous Florida homestead to a new Florida homestead. The transferable benefit is capped at $500,000.
No. It is a maximum reduction in assessed value, not a tax credit or cash payment.
It is the previous homestead’s just or market value minus its Save Our Homes-capped assessed value. The transferable amount remains subject to eligibility rules and the $500,000 ceiling.
A buyer should not assume so. Following a sale that constitutes a change of ownership, the property generally loses the seller’s protection and is assessed at just value the following January 1.
No. The residence must qualify as the owner’s new Florida homestead; a purchase solely for second-home or investment use does not qualify.
The transferable benefit is proportional rather than automatically the full previous assessment difference. It remains subject to the $500,000 cap.
The new exemption must be established within three years of January 1 of the year the old homestead was abandoned. The period does not begin on the sale closing date.
Submit Form DR-501T with the new homestead application, Form DR-501, through Palm Beach County’s Property Appraiser. March 1 is the standard filing deadline for the year the benefits are sought.
At hypothetical applicable ad valorem rates of 1.8%–2.0%, a $500,000 assessment reduction produces approximately $9,000–$10,000 in annual savings. This is illustrative arithmetic, not a verified Forté tax estimate.
No. It caps annual increases in assessed value at 3% or the change in the Consumer Price Index, whichever is lower, rather than capping growth in the total bill.