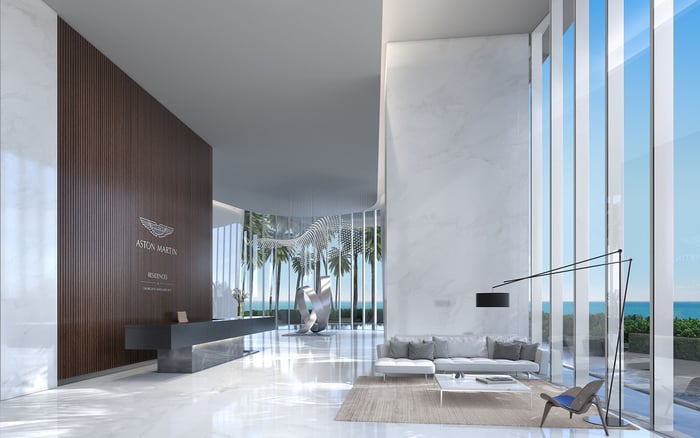
At Aston Martin Residences, an accurate acquisition budget begins with the unit-specific estoppel, not a building-wide dues assumption. Understanding preparation fees, potential capital contributions, transfer charges, and contractual payment responsibility separates closing cash from the longer-term cost of ownership.
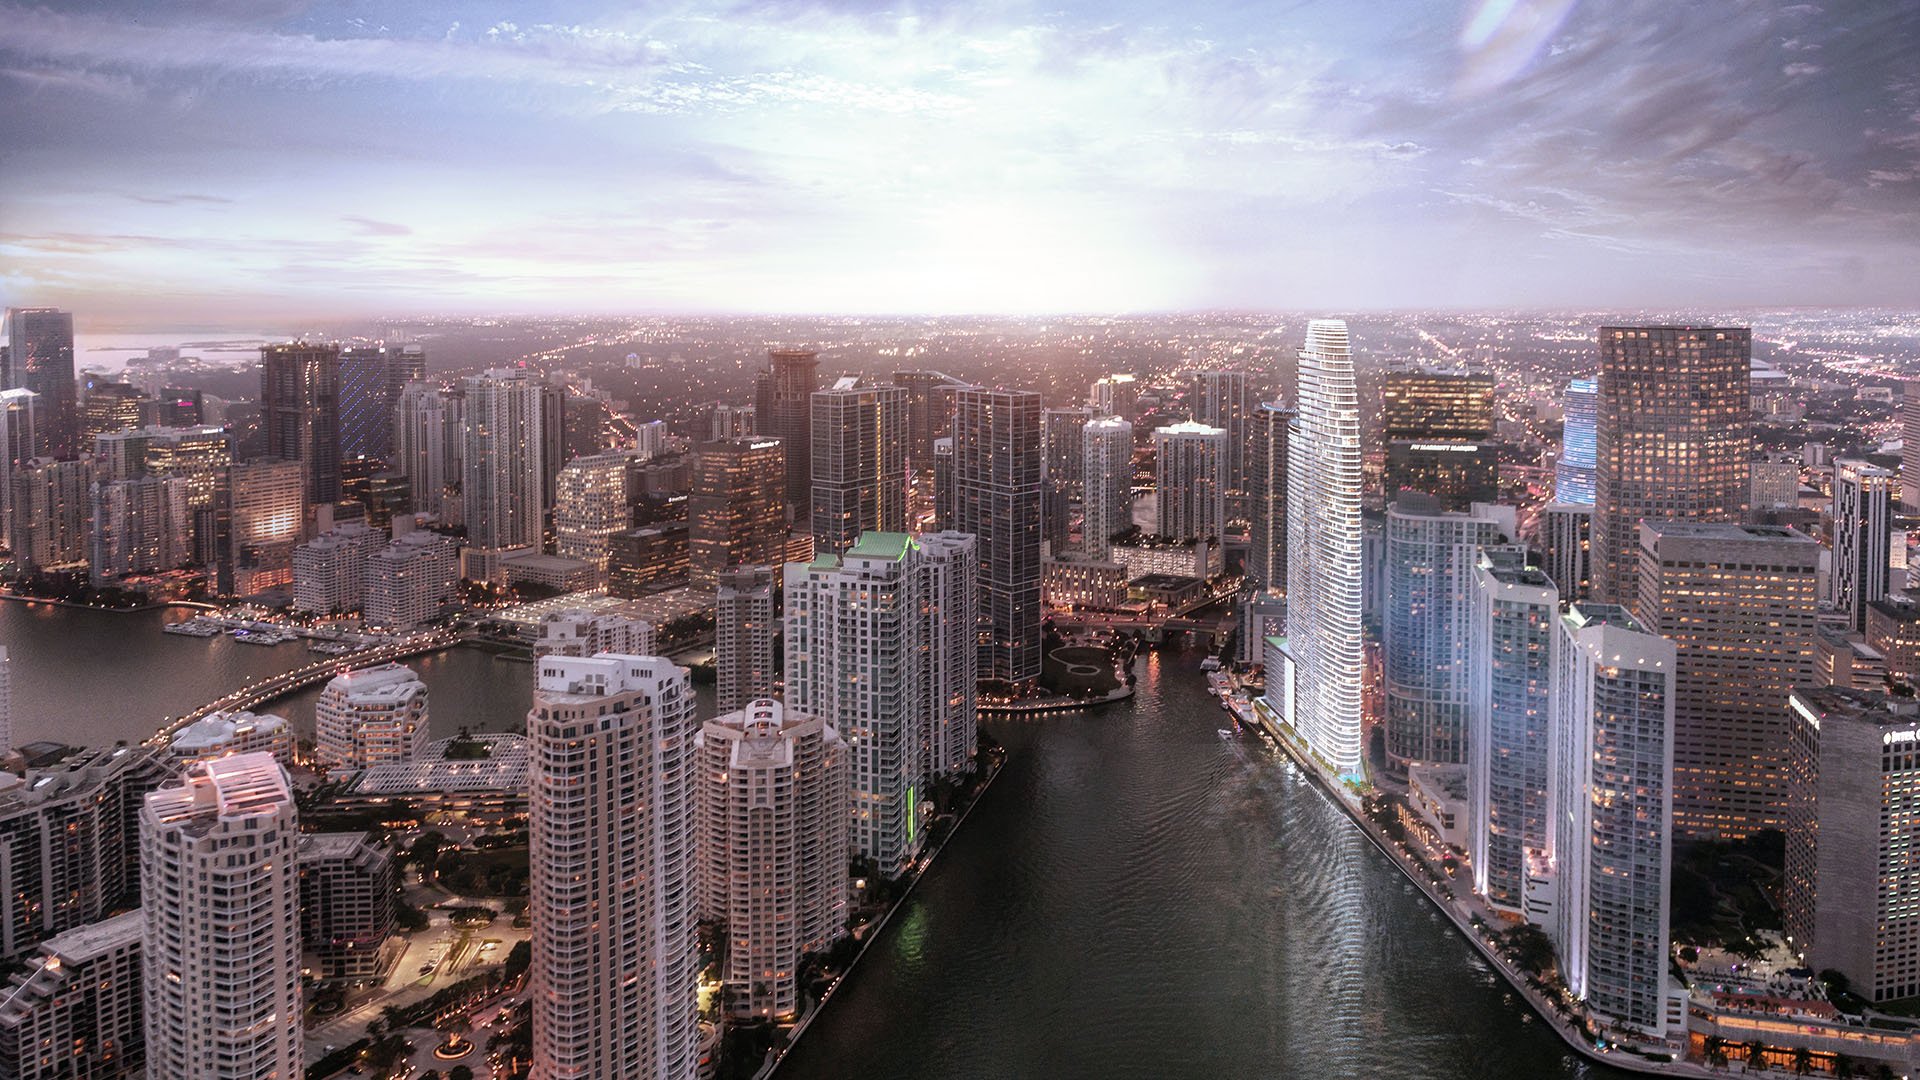
At Aston Martin Residences Downtown Miami, the waterfront address at 300 Biscayne Blvd Way establishes the setting. The financial evaluation demands a different focus: the unit’s association account, charges triggered by the sale, and the documents governing who pays them.
For a buyer, the essential distinction is between cash required to acquire the residence and cash required to own it. Monthly dues belong in the recurring budget. An estoppel preparation fee, an applicable transfer charge, and any required capital contribution belong in a separate closing calculation. Special assessments warrant their own review, not an unexplained allocation to either category.
A precise closing budget identifies each charge, its basis, its payment deadline, and the party responsible under the purchase contract. That discipline matters more than a generalized percentage allowance for closing costs.
A Florida condominium estoppel certificate is the association’s legally binding statement of amounts owed on a particular unit, including assessments and applicable delinquency charges. It is more than an administrative receipt for the closing file.
The certificate should identify association charges triggered by closing, including any required transfer fee, capital contribution, move-in fee, or similar payment. Buyers should have their closing professional reconcile those entries with the contract and closing statement, requesting written clarification wherever a description or allocation is unclear.
Keep two categories distinct. The estoppel preparation fee pays for the document. Arrears, late fees, interest, or assessments disclosed within it are separate obligations. A delinquent account can therefore involve both an additional preparation charge and an outstanding account balance.
The estoppel also has limits. It addresses the unit’s financial obligations but does not replace a review of the association’s budget, reserves, or governing documents. Knowing what must be settled at closing is not the same as understanding future ownership exposure.
The statutory limits for estoppel preparation and delivery are $299 for a non-delinquent account, with additional charges of up to $179 for delinquency and $119 for expedited service. These limits apply to preparation charges. They are neither confirmed fees at Aston Martin Residences nor a ceiling on everything the association might collect at closing.
Standard delivery guidance allows 10 business days; expedited three-day service carries a potential additional charge. Schedule the request early enough for the closing team to resolve questions rather than treating expedited delivery as a substitute for review. Confirm the applicable limits and timing when ordering.
In Florida practice, the seller typically pays the estoppel preparation fee. The purchase contract determines responsibility, however, so custom should never replace an explicit allocation. Nor should a preparation-fee allowance be mistaken for a complete association closing budget.
A capital contribution is generally a one-time payment into association reserves or working capital when ownership changes. It is distinct from recurring monthly dues. A transfer fee is another potential closing charge and should be identified separately, not combined with a contribution under a vague administrative label.
Aston Martin Residences’ actual transfer fee, move-in fee, and any capital-contribution requirement should be confirmed through the association’s transaction documents. Do not assume a contribution applies or calculate one as a multiple of monthly dues without a documented requirement.
For every proposed charge, request its stated basis, amount or calculation, recipient, and payment responsibility. General association-closing practice often places transfer fees and capital contributions on the buyer, but that establishes neither this building’s requirements nor an exception to the contract.
Apply the same discipline to a comparison with One Thousand Museum Downtown Miami: compare documented obligations for the residences under consideration, not assumed charges borrowed from another address. A useful comparison leaves unconfirmed amounts unresolved rather than quietly treating them as zero.
A September 8, 2026 snapshot of 37 active listings with usable fee data showed median monthly association dues of $3,123 at Aston Martin Residences, compared with $974 for Miami condos. This was a listing sample, not a building-wide fee schedule or a quotation for an individual residence.
Unit 3201 illustrates why specificity matters: its listed association dues were $6,852 monthly. Listed inclusions covered insurance, internet, HVAC, hot water, security, pool services, maintenance, water, sewer, trash, and reserve funding. Confirm both the amount and inclusions for the unit being purchased rather than applying that listing to other residences.
These figures inform the carrying-cost discussion. They do not establish a transfer fee, a capital contribution, or the total cash needed at closing. Keep recurring dues separate from one-time acquisition charges, and examine special assessments independently.
For a shortlist extending into Brickell through Baccarat Residences Brickell, use the same comparison structure. Separate monthly obligations, confirmed closing charges, and assessment exposure without implying that different associations share a fee policy.
Negotiation determines who bears a cost; it does not necessarily change what the association requires. A seller credit or an agreement that the seller will fund a capital contribution can alter the buyer’s cash requirement without eliminating the underlying charge.
Ask the closing team to distinguish the estoppel preparation fee, any delinquent balance, applicable transfer or move-in charges, any required contribution, and special assessments. Each should have a clear contractual allocation and corresponding treatment on the closing statement.
Where an assessment is involved, have counsel review the payment schedule and contract language together. Do not assume a broad seller-credit provision settles every association obligation. Precision protects the negotiated economics and keeps the final settlement clear.
Alongside the estoppel, request the declaration, bylaws, current budget, reserve study, recent meeting minutes, and milestone-inspection and Structural Integrity Reserve Study status. Ask counsel or the appropriate professional to interpret applicability and any unresolved obligations.
Reserves fund predictable capital projects and deferred maintenance, separately from the operating budget for routine expenses and services. High dues do not prove adequate reserves. Nor does a listing’s inclusion of reserve funding eliminate future special-assessment risk.
The final decision should rest on three distinct views: documented association cash due at closing, verified recurring carrying costs, and the association’s longer-term financial position. At this level of ownership, certainty is more than an administrative benefit. It is part of the value being acquired.
For a discreet conversation about evaluating South Florida residences and their ownership costs, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt is the association’s legally binding statement of amounts owed on a specific unit, including assessments and applicable delinquency charges. It should also identify required association charges triggered by the closing.
The stated limits are $299 for a non-delinquent account, plus up to $179 for delinquency and $119 for expedited service where applicable. These are not confirmed Aston Martin Residences charges and should be checked when ordering.
Standard delivery guidance allows 10 business days, with expedited three-day service potentially available for an additional charge. Allow time for review and clarification as well as delivery.
The seller typically pays in Florida practice, but the purchase contract determines responsibility. Confirm the allocation rather than relying on custom.
A capital-contribution requirement is not established here. Confirm whether one applies, and its amount or calculation, through the association’s transaction documents.
No. A capital contribution is generally a one-time payment into reserves or working capital when ownership changes, while monthly dues are recurring obligations.
A September 8, 2026 sample of 37 active listings showed median dues of $3,123 monthly, while Unit 3201 listed $6,852 monthly. Neither figure substitutes for confirmation of the particular unit’s current dues.
A seller credit can change who effectively bears the cost, but it does not establish that the association will waive the charge. Document the obligation and contractual allocation separately.
No. High dues and a listing’s inclusion of reserve funding do not establish adequate reserves or rule out future special assessments.
Request the declaration, bylaws, current budget, reserve study, recent meeting minutes, and milestone-inspection and Structural Integrity Reserve Study status. These help evaluate obligations and longer-term financial exposure beyond the closing account.