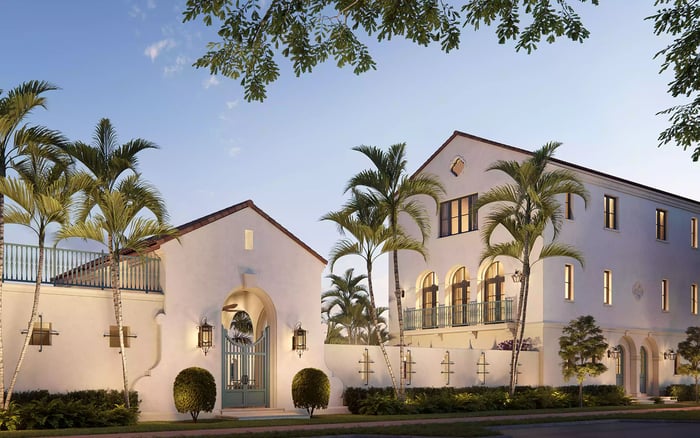
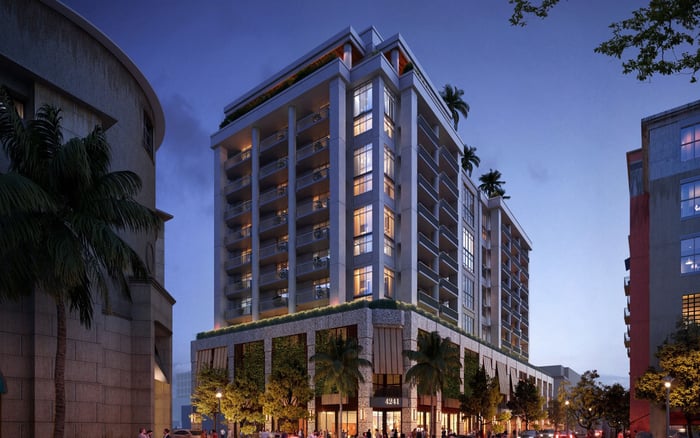
For Aspen owners establishing a Coral Gables base, a considered arrival begins before packing. Align detailed inventories, personal-property and valuable-articles coverage, and written delivery instructions before collections leave the mountain residence.
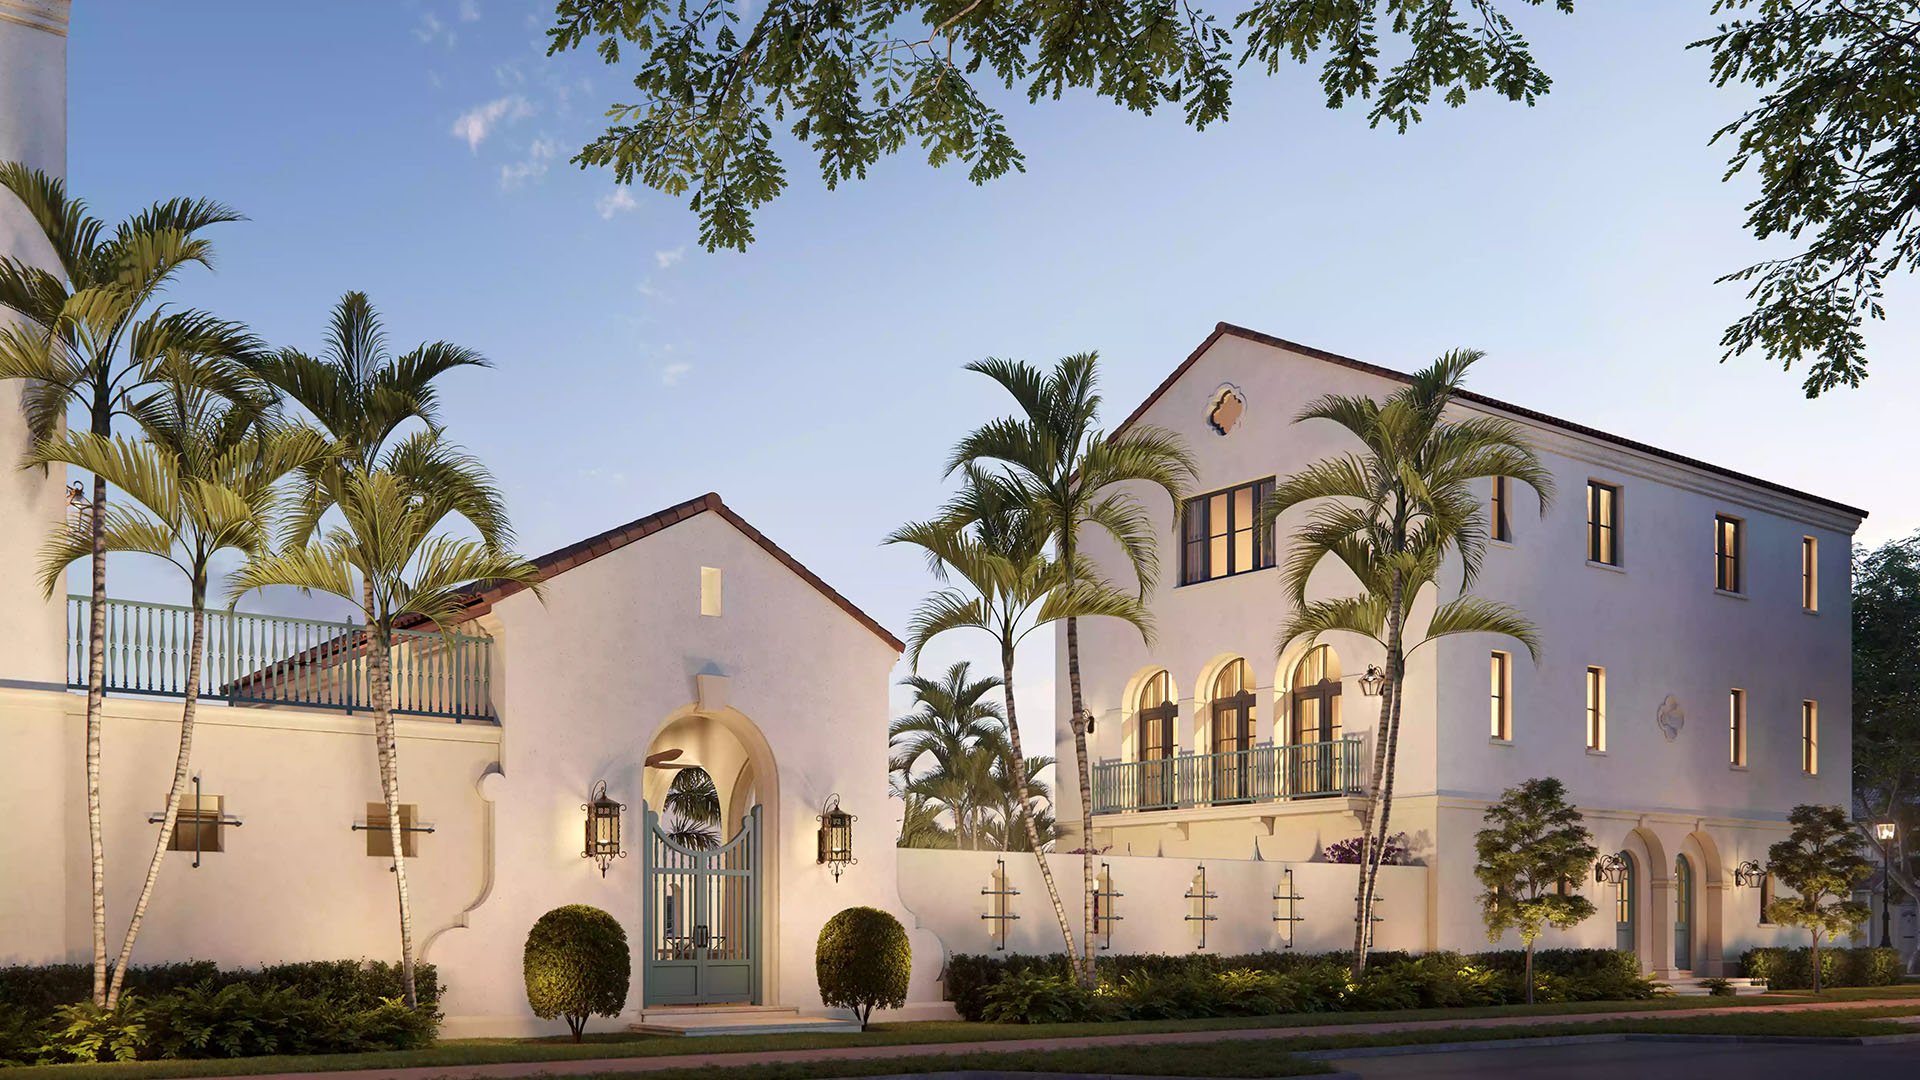
Establishing a Coral Gables base from Aspen involves more than placing favorite furniture and finding the right wall for a painting. The less visible work is aligning ownership records, insurance protection, and the people authorized to receive each shipment. A thoughtfully furnished residence should begin with an equally considered record of what belongs there.
Second-home planning benefits from separating three questions: what is moving, what protection applies, and who takes responsibility at each handoff. Neither a generous contents limit nor a specialist mover's proposal answers all three. Resolve them together before packing begins, rather than leaving insurance as a final administrative task.
For buyers considering The Village at Coral Gables, that preparation can accompany the property decision. Build the receiving plan around the residence ultimately selected, without assuming that any particular address provides collection handling or insured storage.
An effective inventory is itemized, not merely a room-by-room estimate. Record descriptions, brands, models, serial numbers where applicable, purchase dates, purchase locations, and original costs. Attach receipts when available. If an exact purchase date is unavailable, mark it as approximate rather than supplying false precision.
Photographs and video capture details that written descriptions can miss. Photograph distinguishing features and existing condition before packing, then connect those images to the corresponding inventory entries. A broad photograph of a furnished room provides useful context, but should not replace individual documentation for important pieces.
For a household divided between Aspen and Florida, consider adding destination and status fields: remaining in Aspen, moving to Coral Gables, or awaiting a placement decision. Keep original purchase cost distinct from estimated replacement cost. They answer different questions; an invoice alone should not become the default basis for the entire coverage review.
Maintain copies of the inventory and policies in a safe location where they remain accessible after a disaster. Keep a protected backup separate from the shipment and both residences' everyday paperwork.
Coverage C is the personal-property portion of a homeowners policy, covering contents subject to the policy's terms. Personal property includes household belongings used, owned, or worn by the insured or family. That broad definition does not mean every object is protected up to the overall contents limit.
Standard policies commonly impose special limits on categories such as jewelry, silverware, guns, antiques, and cash. Art and cameras can also face special limits. Compare the inventory's estimated replacement cost with the total personal-property limit, then review valuable categories separately. If the inventory exceeds available protection, discuss increasing coverage.
Distinguish replacement-cost protection from scheduled-item coverage. A personal-property replacement-cost endorsement can provide replacement-cost protection for contents damaged or stolen, subject to its terms. It does not, by itself, confirm that a particular artwork or jewel has been individually scheduled or that category limits no longer apply.
Take a focused set of questions to the insurance adviser:
Which items need separate scheduling or other valuable-articles protection?
What valuation documentation or appraisals does the proposed policy require?
Which deductibles, exclusions, and loss circumstances apply?
Where does protection apply when belongings move between residences?
These are matters to confirm in the actual contract, not benefits to presume. Ask specifically about disappearance, temporary storage, and the transition between shipping protection and household coverage.
The destination shapes the delivery plan, but a project name is not a handling protocol. When evaluating Ponce Park Coral Gables, ask who would coordinate deliveries, which access arrangements would need approval, and whether an owner's representative could receive goods. Obtain answers for the particular residence and its applicable procedures.
For a purchase at Cora Merrick Park, apply the same discipline: confirm the practical route from vehicle to final placement before committing to a shipment date. Ask about appointment arrangements, access dimensions where relevant, and any documentation requested from delivery personnel. These planning questions are not statements about the project's services or rules.
If the search extends to Coconut Grove and Four Seasons Residences Coconut Grove, retain the same checklist. Confirm any staffing or receiving assistance directly; neither is a substitute for verified insurance protection.
Treat transit as a separate coverage conversation. Ask the household insurer and proposed shipper to explain protection during packing, collection, transport, any storage, unpacking, and installation. Seek written confirmation of when each arrangement begins and ends, particularly when different parties handle successive stages.
Declared value, cargo coverage, and limited liability are not interchangeable labels. Request the actual terms, including covered events, exclusions, valuation basis, and claims procedures. Do not assume that protection described as full coverage is unrestricted, or that protection for a lost item also covers physical damage.
Select a shipping arrangement only after confirming its suitability for the specific objects and journey. A general high-value service description does not establish that every collection, packing method, or storage interval is eligible. What matters is the written agreement for the shipment being made.
Appointment-only receipt, recipient verification, condition reports, and chain-of-custody records are sensible planning measures. They are presented here as recommendations, not as statements of Coral Gables legal requirements or guaranteed carrier commitments. Agree on them with the parties involved before dispatch.
Designate a primary recipient and backup, and specify how substitutions will be authorized. Match inventory identifiers to the packing list, then request a handoff record showing who released and received the shipment and when. Share detailed collection information only with those who need it to perform their role.
Arrange a documented condition check at arrival and unpacking. Ask in advance how visible damage, concealed damage, or missing pieces should be recorded and reported under the applicable contract. Useful claim records include descriptions, quantities, purchase dates, values, and amounts paid, supported by photographs and receipts where available.
Once belongings are placed, update their inventory locations and retain receiving records with the relevant insurance documents. Revisit estimated replacement costs and coverage when meaningful purchases or transfers change the household's contents. The goal is not a larger file for its own sake, but a clear record that remains useful after the move.
For a considered approach to your South Florida property search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRecord descriptions, brands, models, serial numbers where applicable, purchase dates, purchase locations, and original costs. Attach available receipts and mark uncertain dates as approximate.
Yes. Photographs and video supplement written records; documenting distinguishing details and existing condition before packing is a useful planning step.
Coverage C is the personal-property portion of a homeowners policy. Protection for household contents remains subject to the policy's terms and limits.
Not necessarily. Jewelry, art, and other valuable categories can have special limits that require review separately from the overall contents limit.
No. A replacement-cost endorsement addresses protection for eligible contents damaged or stolen, while individually scheduled protection requires a separate review of the actual policy.
Do not assume a universal requirement. Ask the proposed insurer what valuation documentation or appraisals it requires for the specific items and coverage.
Do not presume continuous protection. Confirm the applicable terms for packing, transport, storage, delivery, and installation with the insurer and shipper.
The delivery measures discussed here are planning recommendations, not statements of local legal requirements. Agree on appointments, authorized recipients, and handoff documentation with the parties involved.
Retain descriptions, quantities, purchase dates, values, amounts paid, and supporting photographs or receipts. Follow the applicable contract's damage-reporting and claims procedures.
Keep copies in a safe location so they remain available after a disaster. A protected backup separate from the shipment is a practical precaution.