A trustee’s preconstruction purchase requires more than an attractive residence and sufficient assets. The contract review should align deposit triggers, escrow protections, notice procedures, currency exposure, and accessible reserves with the trust’s authority and distribution obligations.
For a trustee acquiring a South Florida residence, the purchase agreement also commits trust liquidity. The essential question is not simply whether the portfolio can afford the property, but whether the trustee can meet each payment obligation without compromising distributions, exceeding authority, or relying on assets that cannot become cash in time.
A residence at The Residences at 1428 Brickell may enter the family’s consideration, but the trustee’s review should begin with the trust instrument and governing law-not the presentation suite. Counsel should confirm purchasing authority, required approvals, signing capacity, and how the intended ownership and use fit the trust’s purposes. These are questions for review, not assumptions about any particular project’s terms.
A staged purchase needs a calendar that connects contractual obligations to available funding. For every installment, record the amount or calculation, triggering event, due date, notice requirements, payment destination, and consequences of late payment. Distinguish fixed dates from construction milestones and other events whose timing may shift.
Add an internal timeline for trustee approvals, asset sales, currency conversion, and transfer processing. Internal deadlines should precede contractual deadlines by a margin suited to the trust’s circumstances. Do not assume that anticipated financing, an expected distribution from another investment, or a pending sale will deliver funds when needed.
The calendar should also identify who monitors notices and who can authorize payment if the principal decision-maker is unavailable. A second reviewer can help catch discrepancies between a payment request and the signed agreement. Treat amended schedules as new obligations to assess, not administrative changes to file away.
For Florida condominium purchases before construction, furnishing, and landscaping are substantially completed, payments up to 10% of the purchase price generally must be escrowed, subject to statutory exceptions. Later payments require separate analysis. Amounts exceeding 10% received before construction is completed generally belong in a special escrow account controlled by an escrow agent, subject to permitted withdrawals.
The agreement may authorize the developer to withdraw deposits above the initial 10% once construction has begun. An escrow designation therefore does not establish that every installment will remain untouched until closing. Ask counsel to examine the construction-start conditions, permitted releases, escrow agent, interest treatment, and disposition of funds in the event of default.
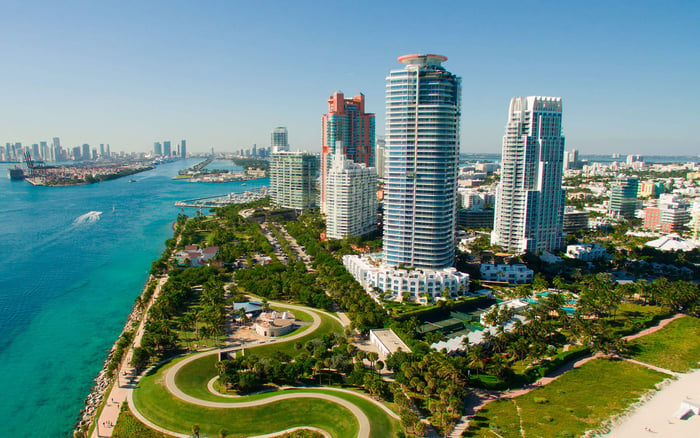
Whether considering The Perigon Miami Beach or another Miami Beach residence, compare the actual contractual treatment of each payment rather than general assurances about escrow. These condominium rules should not automatically be extended to every preconstruction property purchase.
A trustee may describe an upcoming installment internally as a capital call. That label does not establish a legally required notice period. Review the agreement for the event that makes payment due, the notice the developer must provide, and any applicable cure provisions.
Ask whether notices are effective when sent or received, which delivery channels count, and whether copies can go to counsel and the person managing treasury operations. Confirm how address changes are handled and what happens if a milestone notice arrives while an authorized signatory is unavailable. If the agreement permits a short payment window, assess whether the trust can realistically meet it.
Seek clarity on the evidence accompanying a milestone demand and any procedure for disputed triggers. Do not assume that questioning a milestone suspends payment. Any requested notice protection, extension, or cure mechanism should be documented in the agreement, not left as a conversational assurance.
Where trust assets are held in a currency different from the contractual payment obligation, review two matters separately: who bears exchange-rate movement and what constitutes timely payment. Confirm the payment currency, receiving account, responsibility for charges, and whether the contract measures compliance by initiation or receipt of funds.
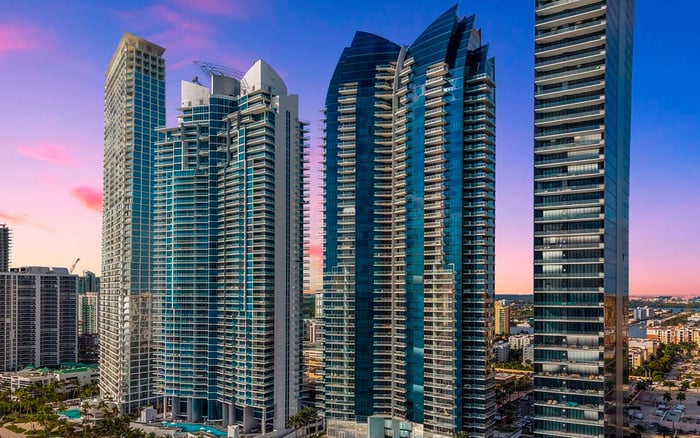
For a potential purchase at Bentley Residences Sunny Isles, a trustee evaluating Sunny Isles Beach should resolve these questions through the agreement and the trust’s banking arrangements. Do not presume project-specific conversion terms.
Treasury advisers can compare converting funds ahead of a deadline with retaining foreign-currency exposure longer. Either approach should account for authorization, availability, fees, and the possibility that exchange-rate changes increase the funding requirement. This review establishes no universal conversion mechanism; the appropriate approach depends on the contract, trust powers, and professional advice.
A short-term liquidity reserve should be a deliberate allocation, not whatever remains after the initial deposit. Build the forecast from scheduled installments, anticipated trust distributions, and identified transaction expenses. Then test earlier payment triggers, delayed completion, and adverse currency movements where relevant.
This review prescribes neither a reserve amount nor a forecasting horizon. The trustee should choose a period that captures meaningful contractual exposure and revisit it when milestone expectations or trust obligations change. Accessible funds matter more than a reassuring total portfolio value.
For a West Palm Beach search that includes Alba West Palm Beach, apply the same discipline: evaluate the proposed commitment against the trust’s other needs. Do not assume that deposits can be reclaimed promptly, that assignment will be available, or that a future sale will provide an exit. Each possibility requires contractual review.
For qualifying developer condominium transactions, Florida’s disclosure provisions provide a cancellation period extending 15 days after receipt of all required documents. Exercising that right requires written notice delivered to the developer within the applicable period. Record document delivery dates and have counsel confirm eligibility and the deadline; signing alone should not be treated as the sole calendar reference.
The trustee’s investment analysis must also follow the applicable trust law. Ask counsel to assess the proposed South Florida purchase against the trust’s purposes, terms, distribution requirements, and other circumstances. Separately, scrutinize personal or financial conflicts and document whose interests the proposed ownership and use serve.
Before signature, assemble a single decision file containing the approved agreement, deposit calendar, escrow analysis, notice protocol, currency plan, and reserve assessment. The strongest commitment is one the trustee can fund, administer, and explain under the trust’s governing framework. This is a review framework, not a substitute for transaction-specific legal and financial advice.
Explore South Florida residences with MILLION while keeping the trust’s contractual and liquidity requirements at the center of the search.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCounsel should confirm the trust’s governing law, purchasing authority, required approvals, and signing capacity. The proposed ownership and use should also be assessed against the trust’s purposes.
No. Florida condominium law generally treats payments within the initial 10% differently from later payments, subject to statutory exceptions and permitted withdrawals.
The purchase agreement may authorize withdrawals of excess deposits once construction has begun. Counsel should review the applicable conditions and permitted releases.
Record each payment’s amount, trigger, deadline, notice requirements, destination, and late-payment consequences. Add internal deadlines for approvals, conversion, and transfers.
No universal notice period is established here. Review the actual agreement for payment triggers, delivery rules, deadlines, and cure provisions.
Confirm the contractual payment currency, exchange-rate allocation, charges, and whether timely payment requires receipt rather than initiation. Align conversion and transfer arrangements with the trust’s authority and deadlines.
There is no prescribed amount established here. Size accessible reserves around contractual payments, anticipated trust distributions, identified expenses, and relevant stress scenarios.
For qualifying developer condominium transactions, the period extends 15 days after receipt of all required documents. Counsel should confirm eligibility and timing, and cancellation requires written notice delivered within the applicable period.
Ask counsel to review the proposed ownership and use under the trust instrument and applicable governing law. Include distribution requirements and potential personal or financial conflicts in the assessment.
Neither should be assumed to provide an available or timely exit. Review the agreement’s assignment provisions and assess reserves without depending on an uncertain future sale.