A multigenerational Palm Beach purchase works best when the family distinguishes ownership, repayment and gifts before closing. Here is how to frame unequal contributions, shared expenses, future exits and the tax questions that deserve separate review.
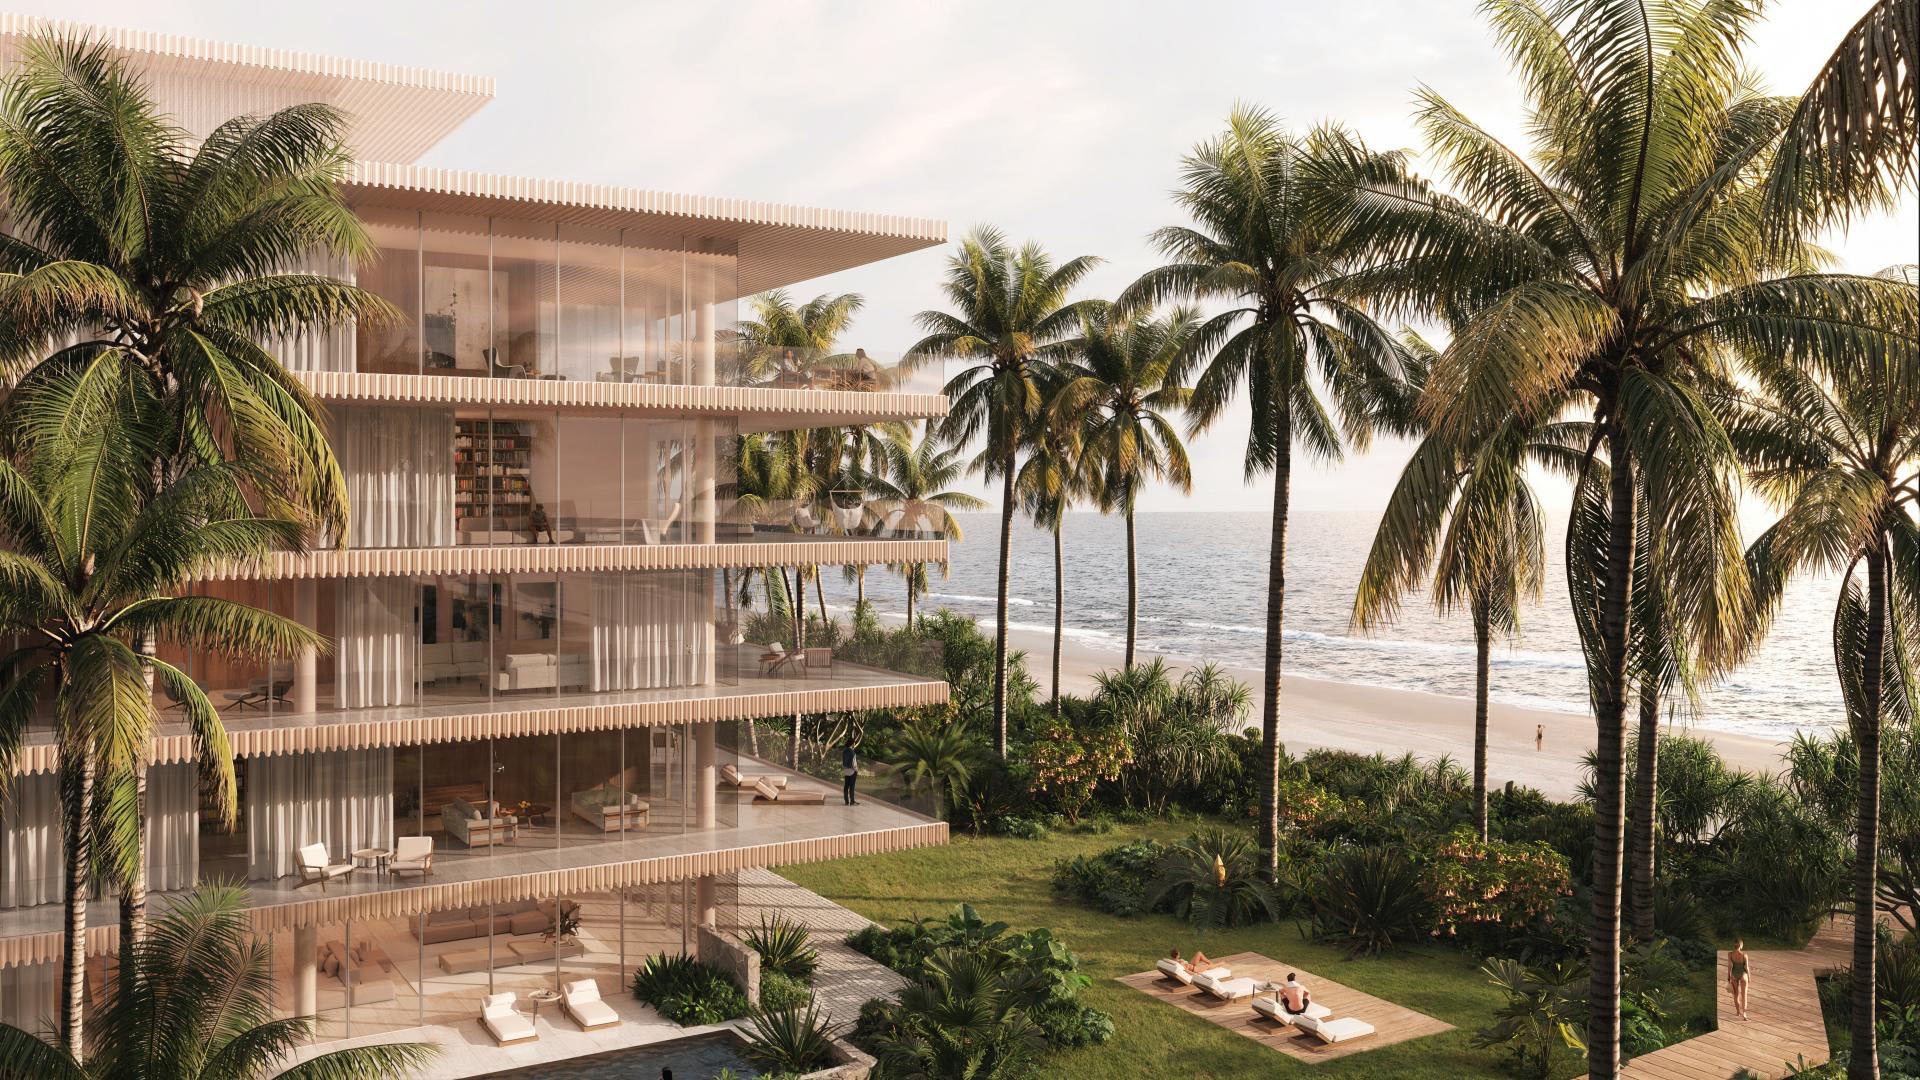
A Palm Beach home shared across generations can be both a private retreat and a long-term family commitment. The delicate question is not simply who contributes more at closing, but what that additional capital is intended to secure: a larger ownership interest, repayment ahead of shared proceeds, or a gift to the next generation.
Resolve that distinction before choosing ownership percentages. Equal enjoyment need not mean equal economics, and unequal funding need not dictate every decision about the home. Begin with a written statement of intent: who contributes, who expects money back, who occupies the property and what each generation hopes to preserve.
For a family considering Palm Beach Residences, these questions belong alongside the residential brief, not after it. The ownership plan should be as deliberate as the choice of home.
Ask counsel and tax advisers to compare three possible approaches. These are contractual planning options, not prescribed Florida rules, and none is inherently best.
Unequal ownership.
A family might propose ownership percentages that reflect each party’s contribution. In a hypothetical all-cash purchase funded 80 percent by parents and 20 percent by an adult child, that could mean discussing an 80/20 ownership split. The documents should address whether later contributions change those percentages and how gains or losses would be allocated.
Priority repayment.
Alternatively, the family might prefer different ownership percentages while giving an additional contribution a negotiated repayment priority. Have counsel distinguish a proposed capital-return arrangement from an actual loan. Specify when repayment would occur and what happens if available proceeds are insufficient. Do not assume that either capital contributions or family loans automatically take priority.
An intentional gift.
Parents may instead want part of their contribution to benefit a child without repayment. Treat that as a separate tax-planning discussion rather than describing every family payment as an investment. A label is no substitute for reviewing the transaction’s substance.
Consistency is essential: the funding schedule, ownership documents and family understanding should tell the same story.
Transferring property or an ownership interest for less than adequate and full consideration is generally a gift for federal tax purposes. A parent who funds a child’s ownership share without receiving equivalent value should therefore assess potential gift treatment before closing.
The federal annual gift-tax exclusion is $19,000 per recipient for 2026, unchanged from 2025. That figure is not a blanket exemption for funding a substantial ownership interest. A gift above the annual exclusion may require a gift-tax return even when no gift tax is immediately payable. The donor, rather than the recipient, is generally responsible for any gift tax.
Ask the tax adviser to evaluate the proposed transfer and reporting obligations before funds move. Do not assume that an equal division on the deed settles the tax consequences of unequal funding. If the intention is repayment rather than a gift, have advisers assess and document the arrangement accordingly.
Once the acquisition is structured, create a separate operating budget. Include property taxes, insurance, maintenance, association charges where applicable, and a reserve for agreed future work. Decide which expenses the family proposes to share by ownership percentage, by use or through another negotiated formula.
For a family comparing Alba West Palm Beach with other West Palm Beach residences, affordability is only part of the question. Every participant must also be able to sustain the agreed commitments without recurring negotiation.
Distinguish routine expenses from improvements. If one generation pays for a renovation, will that payment be reimbursed, recorded as additional capital or treated as a voluntary expense? Decide before approving the work. A shared ledger can record contributions and approvals, but it should support the agreement, not silently rewrite ownership rights.
Do not assume that a seasonal family home qualifies for the homestead treatment available to a permanent residence. Florida homestead eligibility generally requires Florida residency and use of the property as the owner’s permanent residence as of January 1.
Review whether any co-owner receives a residency-based exemption on another property in Florida or another state and how that affects the proposed arrangement. When one generation intends permanent residence and another expects occasional visits, ask the county property appraiser to evaluate the actual ownership and occupancy arrangement before relying on projected savings.
Homestead exemptions reduce taxable property value, not the property-tax bill dollar for dollar. Qualifying property may also receive the Save Our Homes assessment limitation. Those distinctions matter when comparing the costs of permanent occupancy with a seasonal arrangement.
For buyers considering Forté on Flagler West Palm Beach, a tailored tax projection is more useful than an assumption carried over from another family residence.
The seller’s property-tax bill may not reflect the buyer’s future liability. Reassessment following a purchase generally takes effect on January 1 of the following year. Ownership changes can also remove existing exemptions and reset assessed value to just or market value. Transferring a deed to an heir or changing the named owners can affect an existing homestead exemption.
Review those consequences before adding a child to title later. Confirm exemption eligibility with the county property appraiser rather than treating a family transfer as tax-neutral.
Separately, ask counsel to draft a proposed exit process covering valuation, a potential family buyout, payment timing, sale expenses and allocation of insufficient proceeds. These are matters for negotiation and legal review, not automatic rights established by this planning framework.
A family considering Mr. C Residences West Palm Beach should discuss who approves major spending, how holiday use is scheduled and what happens when an owner wants to leave. Ask counsel which decisions could require unanimous consent and how a disagreement would be handled.
Before closing, bring the contribution schedule, proposed ownership split, expense policy, occupancy expectations and exit preferences into the same advisory discussion. Stress-test a renovation, a missed contribution and a requested sale. The objective is not identical treatment in every circumstance, but a clear agreement that each generation understands before the home becomes part of family life.
Explore Palm Beach-area residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe planning options discussed include unequal ownership, negotiated repayment arrangements and intentional gifts. Have legal and tax advisers assess the proposed structure rather than assuming one formula is mandatory.
Funding a child’s ownership share without receiving equivalent value should be reviewed for potential gift treatment. An intention to receive repayment needs separate professional assessment and documentation.
The annual exclusion is $19,000 per recipient for 2026. The same amount applied in 2025.
Not necessarily. A gift above the annual exclusion may require a gift-tax return even when no gift tax is immediately payable.
The donor is generally responsible for paying any gift tax, rather than the recipient.
Do not assume that result. Ask counsel to specify whether an additional payment is reimbursable, additional capital or a voluntary expense, and how it affects the agreed economics.
No. Eligibility generally requires Florida residency and use of the property as the owner’s permanent residence as of January 1, with the county property appraiser determining eligibility.
Yes, disclose any residency-based exemption on another property in Florida or another state. Ask the county property appraiser how it affects eligibility under the proposed ownership and occupancy arrangement.
The seller’s bill may not reflect the buyer’s future liability. Reassessment following a purchase generally takes effect on January 1 of the following year.
Yes, changing the owners listed on a deed can affect an existing homestead exemption. Review the proposed transfer and confirm eligibility with the county property appraiser before proceeding.