Forté on Flagler’s completion and recorded closings materially reduce non-delivery uncertainty. A closer look at its construction financing clarifies what buyers can establish, what remains undisclosed, and which ownership documents deserve attention before closing.
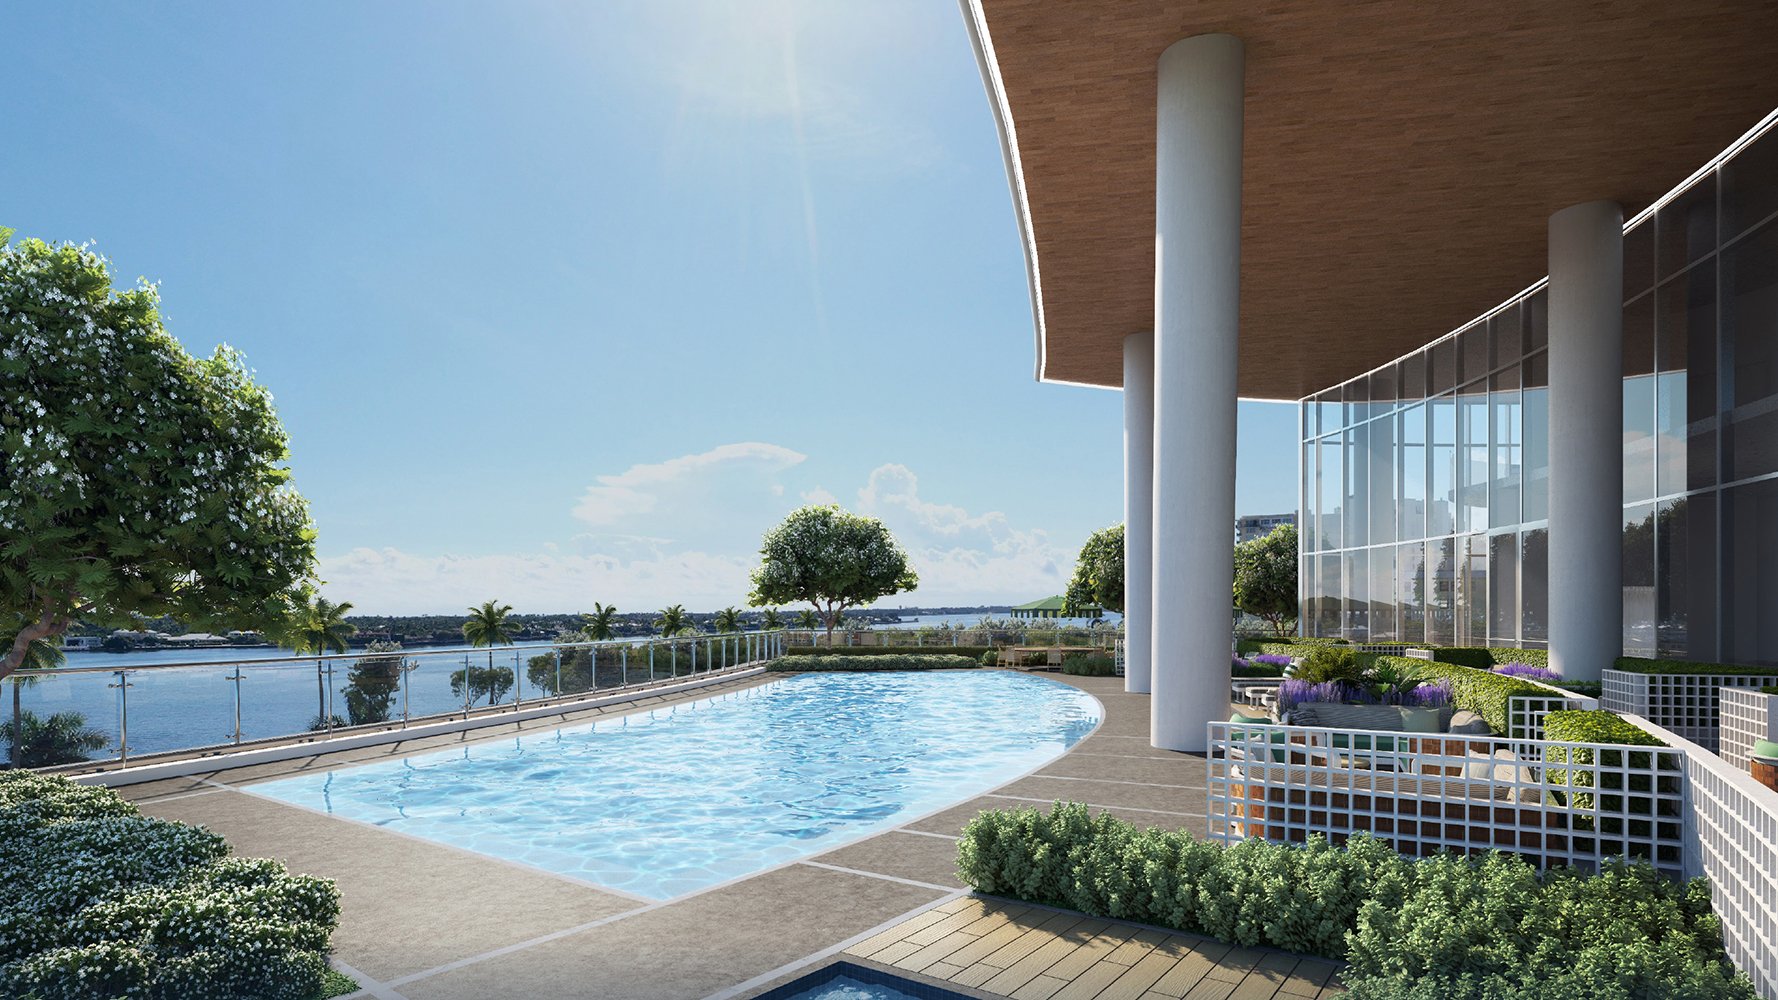
For a buyer considering Forté on Flagler West Palm Beach, the central delivery question has changed. By July 31, 2025, the 25-story waterfront condominium was described as recently completed, and unit closings had begun that month. By August 8, 2025, 19 deeds had been recorded. Those milestones establish more than a reservation book: ownership transfers had moved beyond the presale stage.
Completion and recorded deeds materially reduce non-delivery uncertainty. They do not, however, establish that every construction obligation has been discharged, every defect resolved or every lender claim released. For a substantial acquisition, the distinction is between evidence that a building is complete and evidence that a particular residence can be acquired on acceptable legal and financial terms.
Forté offers a useful lens for examining luxury condominium risk after construction. Its financing history matters, but its value lies in guiding the next questions-not replacing the closing file.
Two Roads Development and Alpha Blue Ventures secured a $121.5 million construction loan from Bank OZK in late 2021. The figure is often rounded to $122 million. Bank OZK was the sole senior secured construction lender through its Real Estate Specialties Group.
That establishes a senior financing relationship and an announced loan amount. It does not establish how much was ultimately drawn, how the outstanding balance changed as units closed or whether the construction loan has since been satisfied. Nor does the designation “sole senior secured construction lender” rule out subordinate financing or other capital arrangements.
The financing relationship was not a completion guarantee. The loan’s existence also does not prove that every project cost was fully funded or that the development remained within its original budget.
For purchasers also considering Alba West Palm Beach, the comparison requires the same discipline: evaluate each financing announcement alongside that property’s own completion and closing documentation. Forté’s financing history cannot establish another building’s risk profile.
Two Roads is led by co-managing partners Reid Boren and Taylor Collins. Marius Fortelni and Scott Maslin are the principals behind Alpha Blue. These names clarify the sponsorship, but they do not reveal the economics of the development partnership.
Developer equity contributions, ownership percentages, guarantees, loan covenants, release prices and outstanding debt are not publicly disclosed in the available financing detail. The title-holding development entity is also not identified. Buyers should not treat developer brands as a substitute for confirming the actual seller and its authority to convey the residence.
Without those capital details, sales headlines support no defensible calculation of sponsor profit, equity returns or remaining financial exposure. Likewise, financing for the separate Forté Jupiter development does not establish Forté on Flagler’s debt payoff or sponsor-wide solvency.
The practical objective is narrower than reconstructing every partnership arrangement: determine which obligations could affect the residence, the closing or the condominium after ownership transfers.
Forté topped off on April 19, 2024, with Moss Construction overseeing placement of the final beam. That milestone marked completion of the structural frame, not the entire building.
At that stage, completion was projected for the first quarter of 2025. The subsequent sequence places completion descriptions and initial closings in summer 2025. This does not support an unqualified claim of on-schedule delivery, nor does it establish a contractual default. Assessing contractual timing requires the relevant agreement and its provisions.
The developers received the condominium declaration in summer 2025. Together with recorded deeds, that supports legal progress toward individual ownership transfers. Specific certificate-of-occupancy or temporary-certificate dates are not established here and should be verified separately.
Identification details also warrant reconciliation. Early plans described 24 stories and 41 residences; later descriptions use 25 stories and 40 units. The address used during construction was 1309 South Flagler Drive, while October 2025 sales descriptions used 1333 South Flagler Drive. The buyer’s legal description and recorded condominium documents should anchor the transaction-not assumptions about those differences.
As of August 8, 2025, 37 presold residences represented approximately $289.1 million in aggregate sales volume, while 19 deeds had been recorded. These measure different forms of progress. Presale contracts demonstrate commitments; recorded deeds establish transfers. Neither figure, standing alone, discloses net cash available to the developer.
Subtracting the original $121.5 million loan from the presale total and labeling the difference profit or remaining equity would therefore be misleading. That arithmetic ignores the distinction between contracted and realized proceeds, as well as undisclosed costs, financing terms and other obligations.
As of October 2, 2025, 37 of 40 residences were identified as sold. That is a dated measure, not a verified current inventory count. It should not be treated as interchangeable with the earlier presale or deed counts.
Buyers weighing Forté against Mr. C Residences West Palm Beach should apply these distinctions independently. A compelling sales narrative is no substitute for a closing statement or mortgage release.
Benjamin Duell’s penthouse purchase was placed at approximately $28.2 million to $28.3 million in October 2025. Separately, a top-floor penthouse carried a $47.5 million asking price that month. The latter was an asking price, not a completed transaction.
Neither figure establishes the construction lender’s remaining exposure. A high-value deed demonstrates an individual transfer, not how all project proceeds were applied. The available inventory detail also does not establish that the offered penthouse was additional to the units remaining within the 40-residence total.
For a buyer, the most useful next step is a residence-specific review with qualified counsel and the title team. Request confirmation of the seller’s legal identity, the recorded condominium declaration and amendments, the unit’s legal description, title exceptions and the documentation needed to release applicable lender liens at closing.
Separately, seek the relevant occupancy documentation, inspection findings, outstanding punch-list commitments, warranty terms and condominium financial information. These are diligence requests, not assertions that Forté has unresolved defects or financial difficulties.
The conclusion is measured but meaningful: completed construction and recorded ownership transfers substantially narrow delivery uncertainty. The remaining task is to distinguish that achievement from clean title, resolved obligations and the practical responsibilities of ownership.
For a discreet perspective on South Florida condominium acquisitions, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationForté was described as recently completed by July 31, 2025, and unit closings began that July. Completion materially reduces non-delivery uncertainty but does not establish that every construction obligation is resolved.
The developers are Two Roads Development and Alpha Blue Ventures. Their identities do not establish the title-holding entity or the partnership’s ownership percentages.
Bank OZK provided the $121.5 million construction loan secured in late 2021. It was identified as the sole senior secured construction lender through its Real Estate Specialties Group.
No. The announced loan does not establish total funding coverage, final costs, the absence of subordinate financing or compliance with the original budget.
A construction-loan satisfaction and the outstanding debt balance are not established by the available financing detail. Buyers should verify the lien-release documentation applicable to their residence.
Nineteen deeds had been recorded by that date. The separate figure of 37 presold residences measured contractual sales activity rather than the same number of completed transfers.
No. That figure represented aggregate presale volume as of August 8, 2025, not equivalent realized proceeds, profit or evidence of loan repayment.
The April 2024 projection targeted the first quarter of 2025, while completion descriptions and initial closings followed in summer 2025. That sequence does not support an unqualified on-schedule claim or independently establish contractual default.
No. It was an October 2025 asking price for a top-floor penthouse, separate from Benjamin Duell’s approximately $28.2 million to $28.3 million purchase.
A buyer should have counsel and the title team review seller identity, condominium documents, title exceptions and applicable lender releases. Occupancy documentation, inspections, warranties and condominium finances deserve separate attention.