The choice between a luxury condominium and a waterfront estate is also a choice about financial control. Compare recurring dues, optional services, capital reserves and assessment exposure before deciding which ownership model best serves the household.
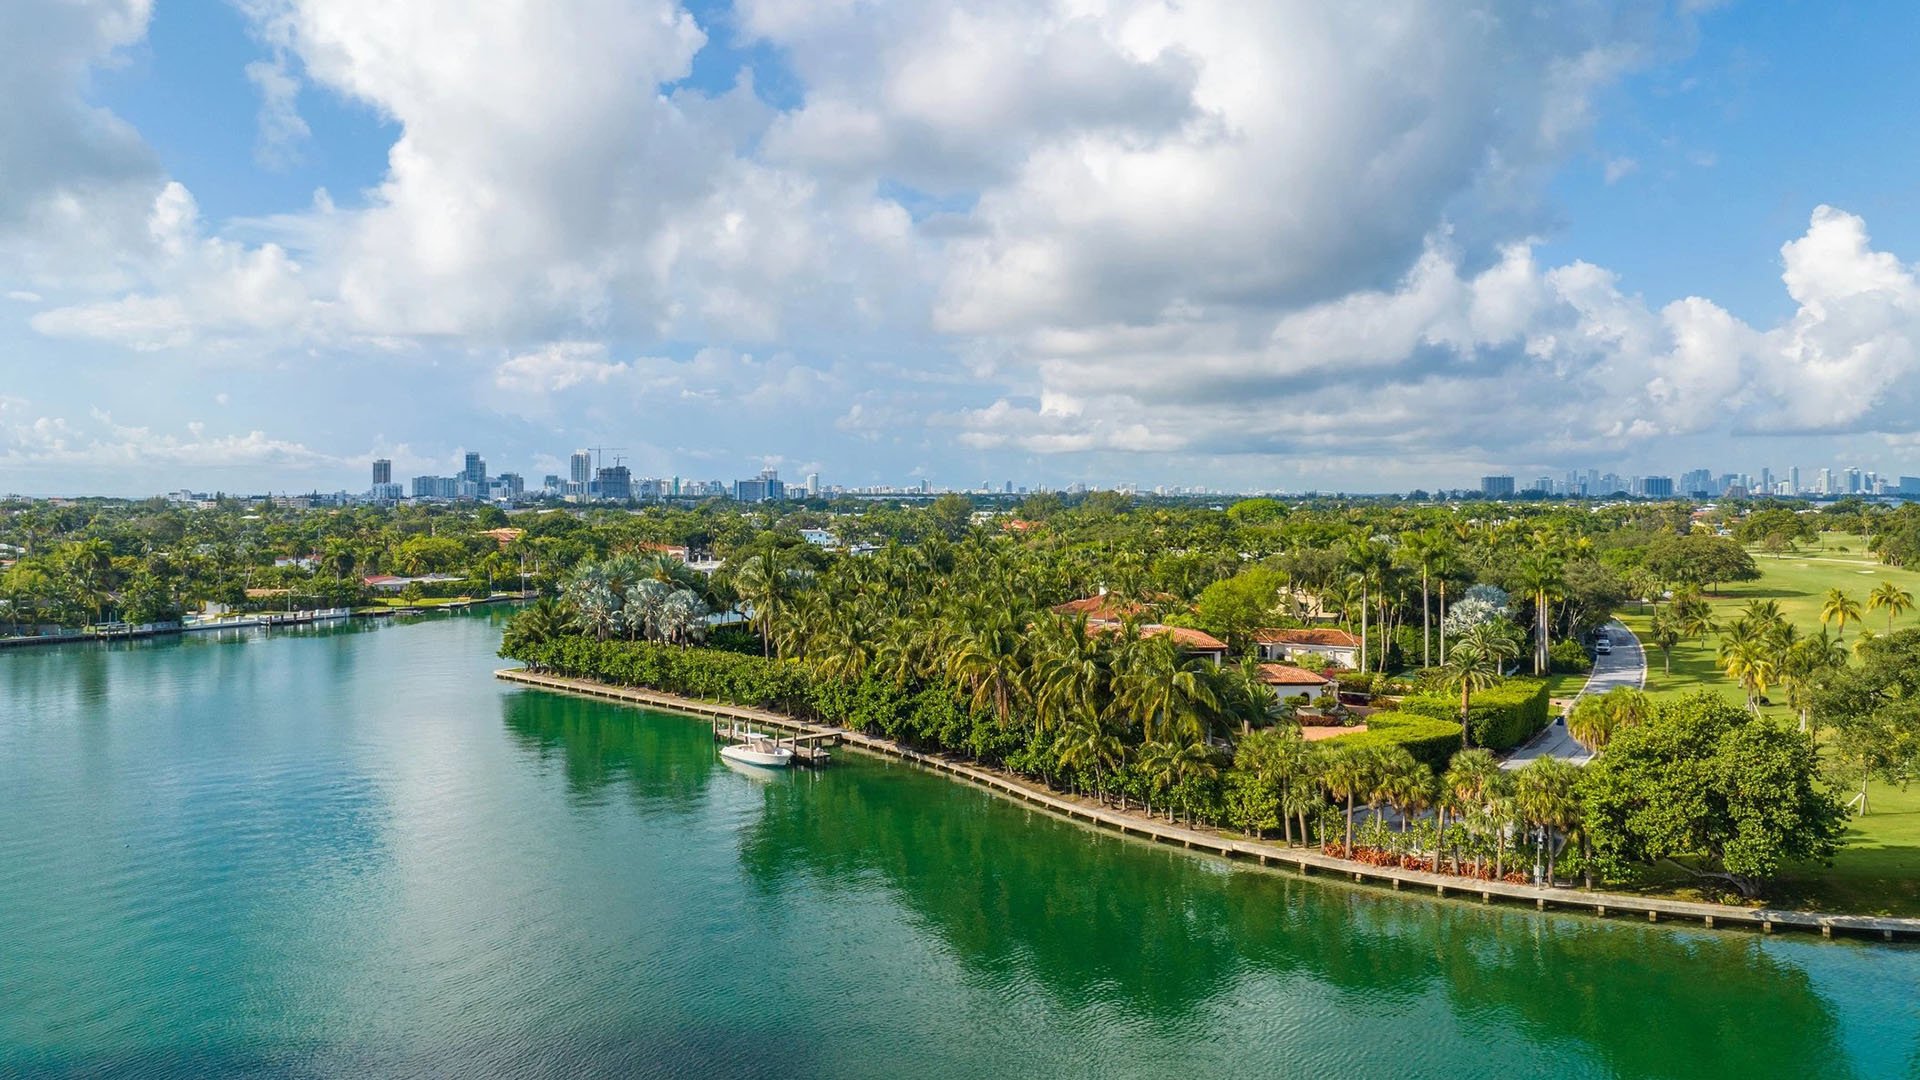
Choosing between a luxury condominium and a waterfront estate in South Florida is not simply a question of views, privacy or architectural preference. It is also a household decision about how expenses are organized, who directs capital work and how much financial uncertainty feels comfortable.
The useful comparison is not monthly condo dues against an estate with no equivalent monthly bill. It is the full ownership obligation: recurring operations, selected services, future replacements and cash available for the unexpected. Neither model should be assumed inherently cheaper. The better fit depends on the property's documents and condition, as well as the household's appetite for oversight.
Start with the desired routine. Decide which services the household would actually use, how much administration it wishes to delegate and how much control it wants over spending. Then test those preferences against a documented budget, not a marketing description.
Regular condominium assessments typically support common-area utilities, landscaping, insurance, management and reserve contributions. Amenities are only part of the picture. A monthly figure deserves scrutiny rather than acceptance as a single price for convenience.
For a household considering Una Residences Brickell, the central question is what the applicable budget requires owners to support. Request the operating budget and reserve contribution schedule, then distinguish current expenses from funds set aside for future work. This is a diligence framework, not a judgment about that property's finances.
Low dues are not evidence of strong finances. Because reserves are funded through regular assessments, recurring charges can rise when an association strengthens its capital position, even without adding services. Conversely, an appealing monthly figure may leave important questions about future funding unanswered.
Compare budgets on the same basis. Identify what is included, what remains payable by the owner and which obligations are already scheduled rather than merely anticipated.
A polished residential experience does not establish a universal service package. Commonly funded amenities and separately billed, opt-in services belong in different parts of the household budget. Availability does not mean inclusion.
When evaluating Four Seasons Residences Coconut Grove, request written clarification of included services and separately charged offerings. Do not infer a housekeeping, concierge, valet or spa arrangement from branding. Confirm what is offered, what the regular assessment supports and what an individual request would cost.
Build two annual spending scenarios: the mandatory ownership baseline and the household's preferred pattern of optional use. Apply the same discipline to an estate by obtaining quotes for services the household intends to arrange privately.
The purpose is not to eliminate discretionary spending. It is to distinguish the cost of ownership from the cost of living as the household prefers.
A reserve balance is meaningful only in relation to the work ahead. Review the latest reserve study, current balances and upcoming capital needs together. Ask whether projected contributions and available funds align with the timing of major repairs-not simply whether an account holds a substantial-looking sum.
Florida's Structural Integrity Reserve Study framework generally requires covered condominium buildings of three or more stories to undergo a study at least every 10 years. SIRS examines specified components, including roofs, load-bearing walls, floors, foundations, fire-protection systems and plumbing. Have qualified advisers confirm the requirements applicable to the building under consideration.
A study can identify a funding shortfall that prompts additional owner contributions. Inadequate reserves increase the likelihood of special assessments for major repairs; a study alone does not establish that the necessary money is available.
For a Miami Beach purchase such as The Perigon Miami Beach, review the documents before committing. Apply the same questions across the shortlist, without presuming any particular reserve position or assessment exposure.
A special assessment is an additional charge, payable once or in installments, for expenses the regular budget and existing reserves cannot absorb. Structural repairs, roof replacement, elevator modernization and emergency work can all create such demands.
Exposure has two dimensions: the association's funding requirement and the share allocated to the residence. For SIRS-related assessments, review the percentage of undivided interest recorded in the declaration rather than assuming every unit pays equally. Ask counsel to confirm the applicable allocation and approval procedure. Special assessments generally require board approval, while an owner vote may also be required by governing documents or applicable law.
Request details of approved and contemplated assessments, including their purpose and payment schedules. Distinguish an established obligation from a possible future expense.
Insurance is not a universal backstop. Hurricane damage exceeding association coverage can generate assessments tied to deductibles or coverage gaps. Individual loss-assessment coverage may respond to covered insured events, subject to terms and limits. Deferred maintenance or structural deterioration generally does not become covered merely because an inspection or SIRS identifies it.
An estate comparison should replace the assumption of no dues with a deliberate capital plan. Do not assume every waterfront home sits outside an HOA or is automatically free of association assessments. Establish the ownership structure and any shared obligations first.
Then apply reserve-study logic to the property itself. Commission appropriate evaluations of roofs, seawalls, docks, pools and mechanical systems where present. Use the findings to develop a replacement schedule and a dedicated capital allowance. This is a budgeting recommendation, not a claim that estate expenses follow a standard amount or timetable.
Separate recurring maintenance from eventual replacement. A service contract is not proof that future capital work has been funded. For household planning, assign responsibility for monitoring condition, obtaining proposals and updating the budget. The absence of a condominium assessment notice is no substitute for that discipline.
Association finances matter beyond the household's immediate cash flow. Outstanding assessments and inadequate reserves can complicate condominium financing, making the association's financial position relevant both at acquisition and eventual resale. Even a cash buyer should consider that connection.
Before choosing, place the two alternatives on one decision sheet: mandatory annual spending, preferred optional services, planned capital contributions and unresolved exposure. Keep known obligations separate from contingencies, and have legal, insurance and technical advisers examine the relevant documents.
The most suitable home is not necessarily the one with the smallest visible monthly charge. It is the one whose obligations the household understands and can comfortably support without compromising its preferred way of living.
Explore South Florida residences with MILLION to refine a shortlist around your household's lifestyle and ownership priorities.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThey typically fund common-area utilities, landscaping, insurance, management and reserve contributions. Amenities are only part of the budget.
Not necessarily. Compare dues with the latest reserve study, current reserve balances and upcoming capital needs before drawing a conclusion.
No universal package can be assumed. Verify which amenities and services are funded through common assessments and which are separately billed or optional.
SIRS examines specified building components and their reserve needs. Florida's framework generally requires covered condominium buildings of three or more stories to undergo a study at least every 10 years.
Yes. Strengthening reserves can increase recurring assessments because reserve contributions form part of the regular budget.
Expenses beyond the regular budget and available reserves can trigger one. Examples include structural repairs, roof replacement, elevator modernization and emergency work.
Do not assume equal shares. Review the declaration's percentage of undivided interest for SIRS-related allocations and have counsel confirm the applicable obligation.
No. Coverage may respond to covered insured events within policy terms and limits, but deferred maintenance or structural deterioration generally is not covered merely because an inspection identifies it.
Do not assume an inherent cost advantage. Compare property-specific operations, optional services and future capital needs, and verify whether the estate has HOA obligations.
Inadequate reserves and outstanding assessments can complicate condo financing. That can matter to a future buyer and therefore to the owner's eventual resale.