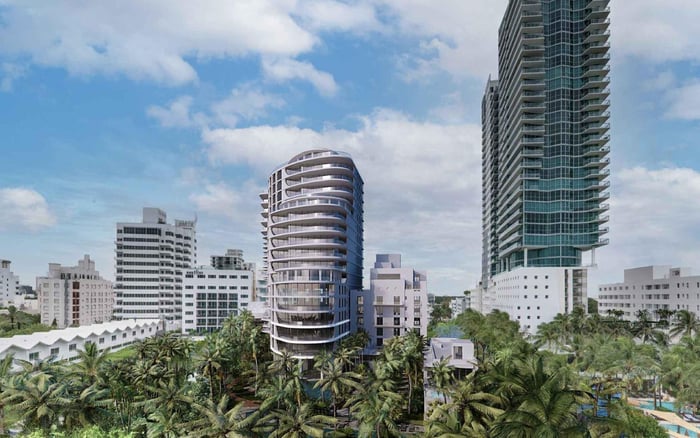
A Luxembourg sale and a Miami Beach acquisition require coordinated, but distinct, planning. Understand acquisition-side FIRPTA duties, compare ownership structures, and model the eventual exit before committing capital.
Moving capital from a Luxembourg property sale into a Miami Beach residence is both a lifestyle decision and a cross-border planning exercise. The address may be the emotional center of the purchase, but ownership, tax compliance and eventual access to sale proceeds warrant attention before signing the contract.
Treat the Luxembourg disposal and the U.S. acquisition as distinct transactions requiring coordinated advice-not as a presumed tax-deferred rollover. Do not assume that reinvesting the proceeds in Florida establishes Luxembourg reinvestment relief, favorable holding-company treatment or a particular treaty benefit. Have Luxembourg counsel establish the sale's consequences while a U.S. international-tax adviser evaluates the purchase.
For a buyer considering The Perigon Miami Beach, the first planning question is not simply which residence to select. It is how the home will be used, who should own it and how much capital should remain available outside the acquisition.
FIRPTA is triggered by a foreign seller's disposition of U.S. real property, not simply by a foreign buyer's purchase. Moving funds from Luxembourg to acquire a Miami Beach home does not, by itself, create FIRPTA withholding on the purchase money.
The purchaser must, however, establish the current seller's FIRPTA status. If that seller is foreign, the buyer generally becomes the withholding agent. Before funds are released, the closing team should resolve the seller's documentation, applicable withholding and filing responsibilities.
Generally, Forms 8288 and 8288-A and the required withholding must be submitted by the 20th day after the sale, subject to applicable exceptions. Failure to withhold and remit correctly can expose the buyer to liability. Delegating closing administration is no reason to leave the issue unexamined.
The same framework becomes an exit concern if you later sell as a foreign owner. Acquisition compliance and future disposition planning therefore belong in the same conversation, even though they concern different sellers at different times.
The standard FIRPTA withholding rate is 15% of the gross sale price, not the profit. For a luxury owner, that distinction can materially affect the cash available for the next purchase, regardless of the property's actual gain.
Withholding is a payment toward tax liability, not necessarily the final tax owed. It can exceed the seller's actual liability, with reconciliation handled through the applicable tax process. An exit model should distinguish expected tax expense from proceeds available at closing.
Qualifying buyer-residence transactions can receive a withholding exemption at $300,000 or less, or a 10% rate above $300,000 through $1 million, subject to residence-use requirements. Above $1 million, the buyer's intended residential use does not reduce the standard 15% rate. Another applicable exception or reduction would be needed.
Whether the purchase shortlist includes Setai Residences Miami Beach or another residence, model the eventual disposition under the withholding rules. Do not assume a future owner-occupant will resolve the liquidity question.
The structures worth evaluating include personal title, a U.S. LLC and a foreign entity owning a U.S. LLC. Familiarity alone is not a reason to select one. Each requires a comparison of estate exposure, administration, financing and control.
Personal ownership requires particular attention to succession. Direct ownership of U.S. real estate by a nonresident foreign individual can create U.S. estate-tax exposure, separate from income tax and FIRPTA withholding.
A U.S. LLC can offer liability protection, but it does not automatically eliminate estate-tax exposure. Nor is it a promise of anonymity or a universal FIRPTA solution. The entity's classification and ownership arrangement require professional review.
A foreign entity holding a U.S. LLC deserves equally careful analysis. Ask advisers to compare the full ownership cycle-acquisition, use, ongoing administration and disposal-rather than formation alone. Do not assume all structures produce identical withholding outcomes.
Before purchasing at Five Park Miami Beach, for example, have the accountant and attorney align the proposed titleholder with the intended use and financing. The residence can remain the focus of the search while the ownership decision receives its own disciplined review.
A personal retreat, a rental investment and a mixed-use residence call for different planning briefs. Establish the intended pattern of use before choosing a structure or relying on a particular exit strategy.
Foreign individual owners should plan for applicable U.S. taxpayer-identification and return-filing requirements. These can include reporting taxable rental income, reporting sale gains and reconciling withholding. Ongoing compliance belongs in the ownership budget, not just the closing checklist.
A qualifying Section 1031 exchange can defer gain on investment real estate. Do not assume it is available merely because a property is valuable or its sale proceeds will purchase another home. Investment-property treatment matters, and foreign sellers must coordinate exchange requirements with FIRPTA rather than assume an exchange automatically removes withholding.
A buyer considering Shore Club Private Collections Miami Beach should clarify the intended use without presuming any particular rental or assignment permission. Contractual possibilities and tax treatment require separate confirmation.
Luxury-condo planning can encompass a permitted pre-construction assignment, resale around delivery, medium-term ownership or a five-to-ten-year hold. These are scenarios to evaluate, not promises of availability or performance. Any assignment strategy should begin by confirming that the contract permits it.
For each plausible exit, ask advisers to model gross proceeds, transaction costs, any financing repayment, estimated tax and withholding. Keep the closing-cash calculation separate from the eventual after-tax result. That distinction is especially important when the sale is intended to fund another acquisition.
Form 8288-B allows a foreign seller to request an IRS withholding certificate reducing withholding to the applicable tax liability, potentially including zero where justified. Discuss preparation early enough for advisers to assess the application and its interaction with the closing timetable.
Early preparation is a recommendation, not a universal 90-day filing requirement or a guarantee of approval. Unless a valid reduction or exception applies, plan liquidity around the standard withholding-not an anticipated favorable decision.
A considered acquisition brief should identify the intended use, proposed titleholder, current seller's FIRPTA status, applicable filing responsibilities and a realistic exit horizon. Luxembourg and U.S. advisers should coordinate their conclusions without treating one jurisdiction's answer as a substitute for the other's.
This is general planning guidance, not individualized legal or tax advice. The objective is a residence that fits the buyer's life and an ownership plan that remains workable when that life changes.
For a considered approach to your Miami Beach residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationForeign-buyer status alone does not trigger FIRPTA. However, buying from a foreign seller can create withholding obligations for the purchaser.
No tax-deferred rollover should be assumed. Luxembourg counsel should establish the sale's consequences separately from the U.S. acquisition analysis.
No. Standard withholding is 15% of the gross sale price, not the seller's gain, unless an applicable exception or reduction applies.
No. Withholding is a payment toward tax liability and can exceed the actual tax owed, requiring reconciliation through the applicable tax process.
Residential use alone does not reduce the standard 15% rate above $1 million. Another applicable exception or reduction would be needed.
The buyer is generally the withholding agent. Forms 8288 and 8288-A and the withholding are generally due by the 20th day after the sale, subject to applicable exceptions.
No. A U.S. LLC can offer liability protection but does not automatically eliminate U.S. estate-tax exposure.
Options to evaluate include personal title, a U.S. LLC and a foreign entity owning a U.S. LLC. Advisers should compare estate exposure, administration, financing, control and disposition consequences.
It allows a foreign seller to request an IRS withholding certificate reducing withholding to the applicable tax liability, potentially including zero where justified. Approval should not be assumed.
No. A qualifying exchange can defer gain on investment real estate, but foreign sellers must coordinate exchange requirements with FIRPTA separately.