A practical guide to coordinating trust or LLC ownership, unit-owner insurance, deposit reconciliation, and funding contingencies for a purchase at One Park Tower by Turnberry in North Miami.
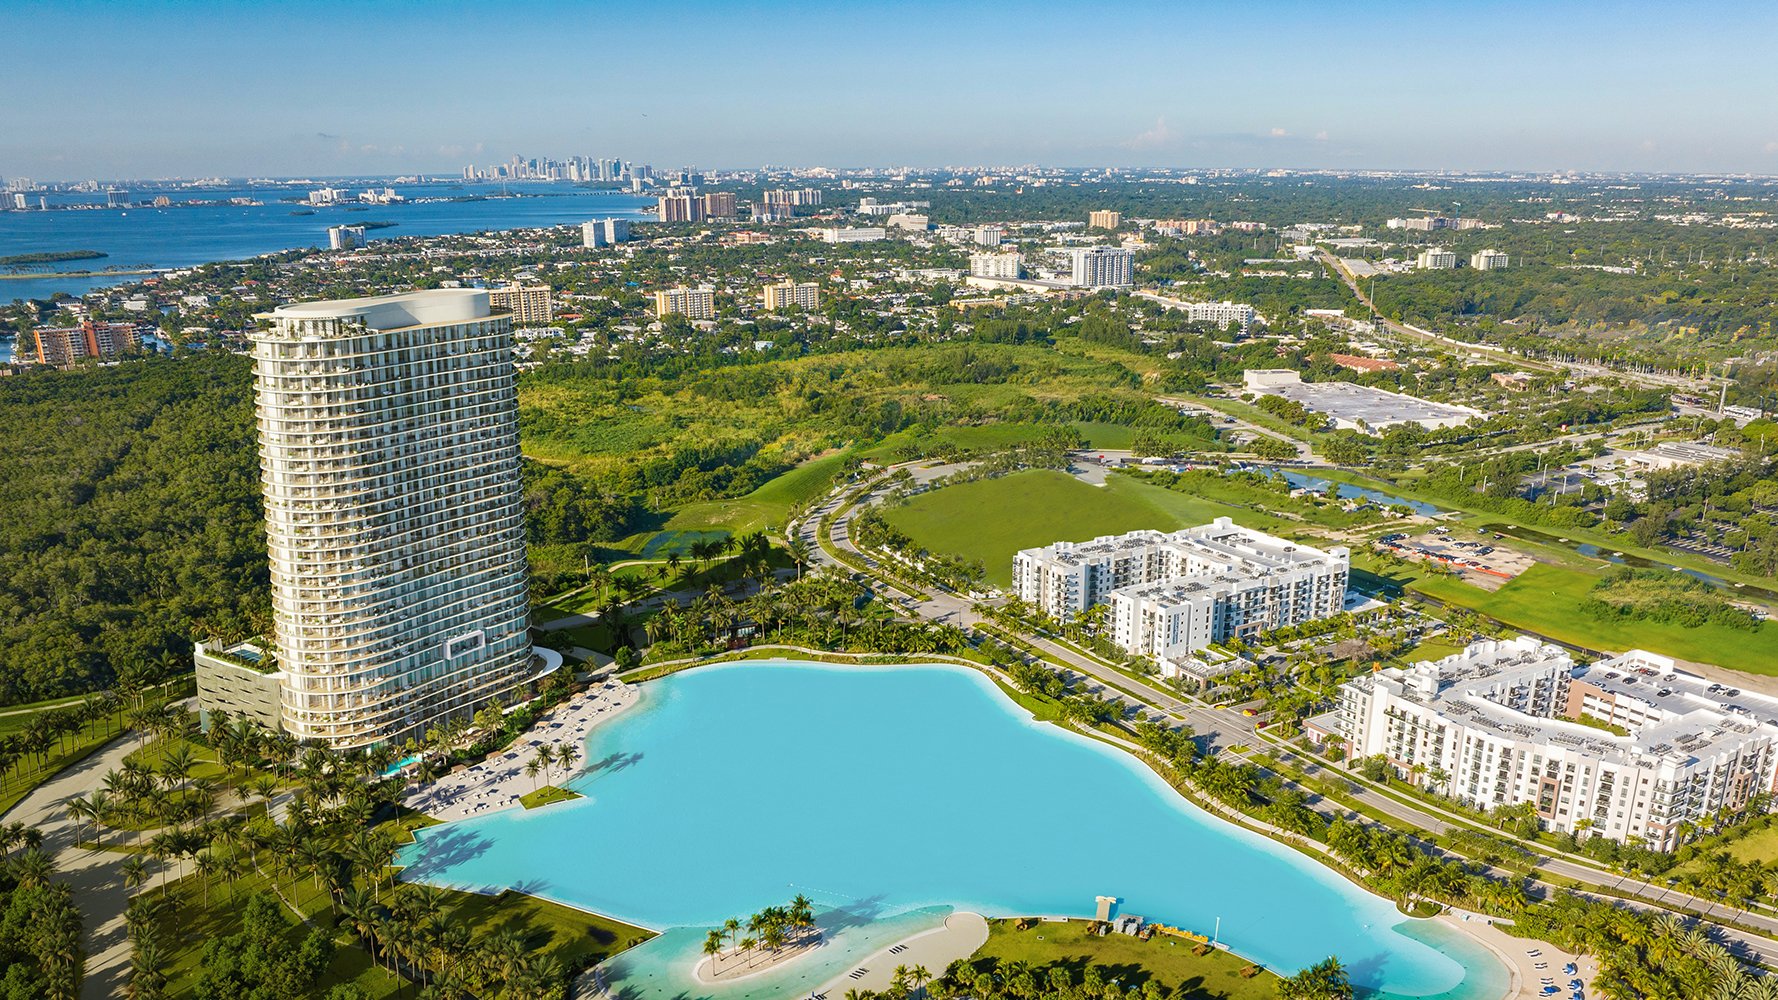
At One Park Tower by Turnberry North Miami, a luxury condominium development at SoLé Mia, an elegant acquisition calls for equally disciplined execution. For a buyer using a trust or LLC, the essential task is to align the purchasing party, authorized signer, insurance arrangements, and movement of funds before closing becomes time-sensitive.
The project’s purchase framework directs buyers to the Florida prospectus and legally required developer disclosures rather than advertising, renderings, floor plans, descriptions, or oral representations. Review those materials alongside the purchase agreement before treating any marketing description as a binding term.
Keep four workstreams distinct: ownership approval, insurance readiness, cash-to-close reconciliation, and funding contingencies. Each needs a responsible contact and written confirmation. A proposed ownership structure is not accepted title vesting, just as a wire instruction is not proof that funds have been received and cleared.
Ask the developer and closing counsel whether the proposed trust or LLC may purchase directly, and whether changing the purchaser named in an existing agreement requires consent, an assignment, or another documented step. Do not assume that moving from an individual purchaser to an entity is merely a clerical correction.
Request written confirmation of the exact name and capacity to appear on the deed and closing documents. For a trust, ask how the trustee should be identified. For an LLC, ask who may execute documents and what evidence of authority the closing team requires. Have counsel identify the supporting documents needed for the specific structure rather than assembling a generic package.
Coordinate that confirmation with any lender and insurer. The objective is not necessarily identical wording on every document, but an accepted, coherent description of ownership and signing authority. Ask who will resolve discrepancies and when revised documents must arrive.
For buyers also considering Turnberry Ocean Club Sunny Isles in Sunny Isles Beach, the same questions apply, but obtain answers independently for each transaction. Neither a shared developer name nor a similar ownership plan establishes identical closing terms.
The association’s master insurance policy does not automatically replace the owner’s unit-owner coverage. Before arranging a binder, request master-policy information and clarify which property and risks remain the owner’s responsibility. Use those boundaries to guide the coverage discussion rather than assuming the building’s policy resolves every insurance need.
Ask the insurer and closing team to confirm the insured-name wording appropriate to the accepted trust or LLC structure. Also confirm the effective date, property description, and any lender or association conditions applicable to the transaction. A binder prepared for an individual buyer should not be reused without review after the ownership arrangement changes.
Request confirmation that the proposed evidence of coverage satisfies the applicable closing conditions. Ask what remains outstanding and who must approve a corrected binder. Treat insurance readiness as a separate closing checkpoint: a paid premium or issued document does not establish that its wording and timing have been accepted for this purchase.
Florida’s developer-sale disclosure statute requires the purchase contract to identify the escrow agent and state that purchasers may obtain receipts for their deposits upon request. Those receipts provide a useful starting point for reconciling money already paid.
For condominium property that has not been substantially completed, Florida law generally requires buyer payments up to 10% of the sale price to be held in escrow. Exceptions and permitted alternative assurances matter, however. Do not assume that every payment, or every portion of a deposit schedule, carries identical escrow protection.
Ask counsel to explain the treatment applicable to your agreement and payments. Qualifying title insurers, title insurance agents, Florida attorneys, banks, and other authorized institutions may serve as condominium escrow holders, subject to statutory requirements.
Separately confirm who will receive the closing funds and in what capacity. Clearly identify both the entity handling purchase deposits and the party receiving the final closing wire; do not infer one role from the other.
Before authorizing the final wire, request a closing statement that can be reconciled against the contract, amendments, deposit receipts, and confirmed credits. The question is not simply whether the total looks plausible, but whether each component has a documented explanation.
Review the purchase price, deposits credited, contractual credits, prorations, taxes, fees, and any other applicable adjustments. Ask the closing team to explain unfamiliar charges and identify unresolved estimates. When an amount changes between statement versions, request the reason and its effect on the final balance.
Use a buyer-side reconciliation worksheet if helpful, but do not treat it as a substitute for the closing team’s approved statement. Confirm the final wire amount in writing and ask how an overpayment, shortfall, or late adjustment would be handled.
A buyer comparing The Residences at 1428 Brickell with a North Miami purchase can apply the same discipline. Compare documented obligations and transaction-specific totals rather than assuming that fees, credits, or deposit arrangements are interchangeable.
Same-day funding should be a coordinated plan, not an expectation based on when a wire is initiated. Obtain written answers about the receiving party’s cleared-funds cutoff and the sending bank’s timing. Ask what confirmation the closing team requires before it considers the funding condition satisfied.
Address delayed wires and compliance holds explicitly. Who monitors an outstanding transfer? Who can approve an extension? What notice must be given, and what contractual consequences could follow? Counsel should evaluate those answers against the purchase agreement rather than rely on a verbal assurance that a delay will be accommodated.
Clarify the sequence for document execution, receipt of cleared funds, recording, disbursement, and key release. Ask whether any of those steps may occur on different days and what that means for possession. Avoid scheduling arrivals or deliveries around an unconfirmed handover.
The fallback should identify responsible contacts, escalation steps, and any extension process available under the agreement. Do not treat a requested contingency as an established project policy until it is confirmed in writing.
Before closing, request a coordinated status review: accepted vesting and signer authority, satisfactory insurance evidence, reconciled cash-to-close, and confirmed funding procedures. Every outstanding item should have a responsible contact and an agreed next step.
A trust or LLC can be part of a considered acquisition plan, but the structure itself does not resolve contract, insurance, or funding questions. Have legal, tax, insurance, and closing advisers address their respective responsibilities before the final transfer becomes urgent.
For a discreet perspective on South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationObtain written confirmation from the developer and closing counsel that your proposed ownership arrangement is acceptable. Ask whether consent, an assignment, or other documentation is needed for your specific agreement.
Ask closing counsel to identify the documents needed to establish the proposed ownership and signer authority. Do not assume a generic entity package meets the transaction’s requirements.
Review the purchase agreement, Florida prospectus, and legally required developer disclosures. Do not treat advertising, renderings, floor plans, or oral representations as binding purchase terms.
Not automatically. Request the master-policy information and clarify which property and risks remain your responsibility before arranging coverage.
Confirm the insured-name wording, effective date, property description, and any applicable lender or association conditions with the insurer and closing team. Have ownership changes reviewed before reusing an existing binder.
Florida’s developer-sale disclosure statute requires the contract to state that purchasers may obtain deposit receipts upon request. Use those receipts to check the deposits credited on the closing statement.
No. For property not substantially completed, Florida law generally requires payments up to 10% of the sale price to be escrowed, but exceptions and alternative assurances can affect the applicable protection.
Review the purchase price, deposits, contractual credits, prorations, taxes, fees, and other applicable adjustments against the supporting documents. Obtain written confirmation of the final wire amount.
Do not assume it does. Confirm cleared-funds cutoffs and the procedures for delayed transfers, compliance holds, recording, disbursement, and key release.
Follow the confirmed escalation and notice procedures, and have counsel review any extension rights and contractual consequences. A requested extension should not be treated as approved until it is documented.