A buyer’s guide to aligning trust or LLC ownership with insurance at Aston Martin Residences, from replacement-cost appraisals and storm deductibles to the limits of loss-assessment protection.
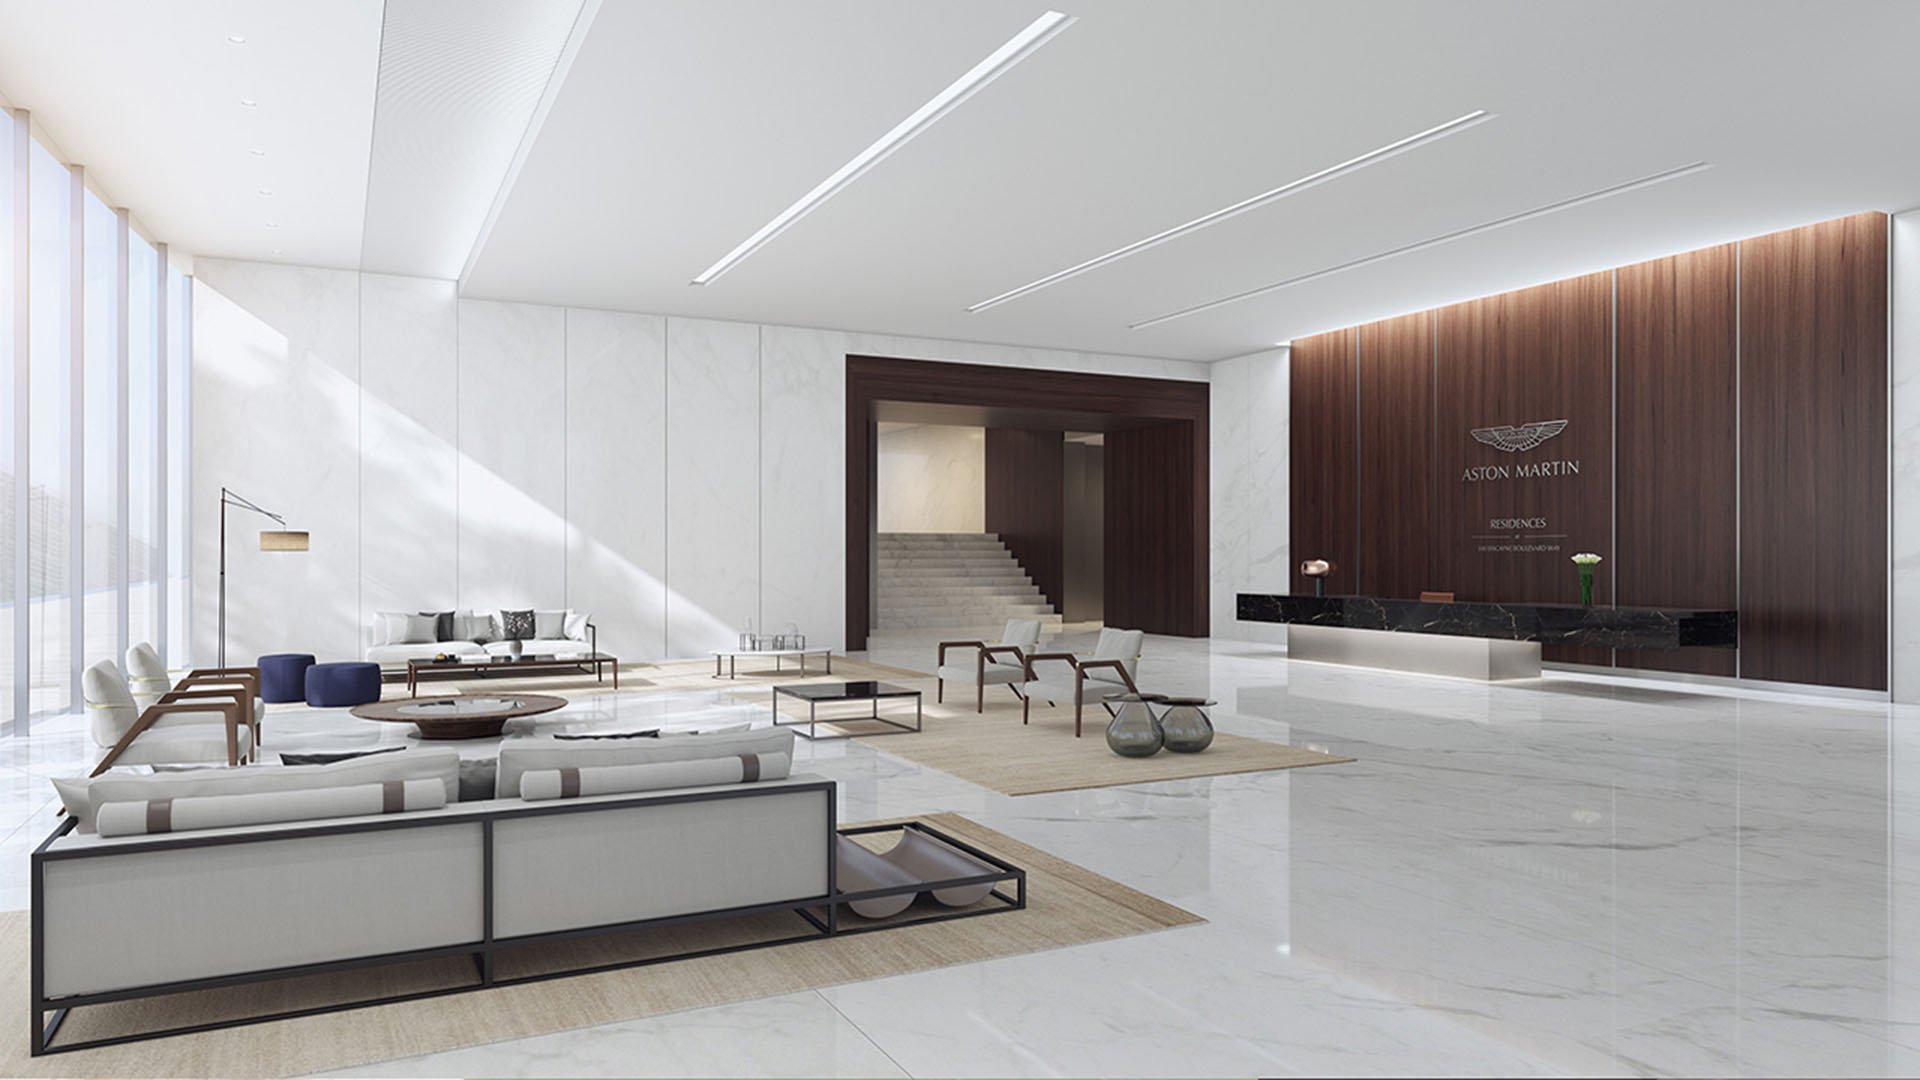
At Aston Martin Residences Downtown Miami, located at 300 Biscayne Boulevard Way, Miami, Florida 33131, a purchase through a trust or LLC warrants an insurance review alongside the title review. The objective is not merely to obtain a policy, but to understand whose interests are insured, which losses qualify, and what financial exposure remains with the owner.
For a substantial condominium acquisition, three questions merit particular attention: what the association’s replacement-cost appraisal establishes, how a storm deductible translates into dollars, and whether the unit-owner policy would respond to a resulting assessment. Neither the residence’s purchase price nor its branding answers those questions.
Treat the ownership structure, master policy, and individual policy as one coordinated diligence exercise. Before closing, ask counsel and the insurance broker to reconcile the proposed titleholder, intended occupants, and coverage wording in writing.
Do not assume a policy suitable for an individually owned residence will suit the proposed trust or LLC. Ask counsel whether the intended structure satisfies the condominium’s governing documents, and ask the broker whether the carrier accepts that structure for the intended occupancy.
Be specific. How should the trust, trustee, or LLC appear in the policy? Who should be a named insured, and which endorsements, if any, are needed? How will residents’ personal property and liability interests be addressed? If financing is involved, will the lender approve both the ownership arrangement and the insurance documentation?
These are points to confirm, not conclusions about this building’s rules or any carrier’s eligibility standards. Request written answers tied to the proposed policy, rather than a general assurance that entity ownership is routine. Ask the same advisers to confirm how loss-assessment coverage would apply to the proposed insured ownership arrangement.
Florida’s condominium-insurance framework focuses on full insurable value, replacement cost, or similar coverage-not a unit’s resale price. Replacement cost may be established through an independent insurance appraisal or an update of a previous appraisal. The association’s appraisal or update is required at least every 36 months.
For a buyer, the practical request is straightforward: obtain the latest replacement-cost appraisal, its effective date, and the master-policy declarations and endorsements. Ask the broker to explain how the valuation relates to the insured property and the limits purchased. A purchase appraisal does not answer that question.
Keep this valuation exercise separate from any policy provision labeled “appraisal” that addresses a claim dispute. Do not assume such a clause exists or carries particular terms. If one is present, have counsel examine its trigger, scope, procedure, and costs in the actual policy.
A buyer also considering Waldorf Astoria Residences Downtown Miami should ask the same document-based questions there, without assuming the two properties share valuation practices or policy provisions.
An association’s named-storm deductible can be expressed as a percentage of insured value. A modest-looking percentage can therefore represent a substantial amount before the association’s insurance responds, subject to the policy’s terms.
As a purely hypothetical illustration, 5% applied to a $500 million insured-value base equals $25 million. Neither figure describes Aston Martin Residences. The calculation shows why the deductible percentage alone is insufficient: the value to which it applies matters just as much.
Ask the broker to identify the applicable valuation base, trigger, and calculation method. Confirm the policy’s definitions rather than treating “named storm,” “hurricane,” and “windstorm” as interchangeable. Request a dollar illustration using the actual policy and valuation schedule.
Then distinguish the association’s exposure from the individual owner’s potential obligation. Allocating insured-loss deductibles and uninsured repair costs requires a review of applicable condominium law, governing documents, and insurance terms. Do not simply divide a hypothetical deductible equally among residences or assume the purchase agreement establishes the allocation.
Florida requires residential condominium unit-owner policies to include at least $2,000 in property loss-assessment coverage. That statutory floor is neither a personalized recommendation for an ultra-premium residence nor a promise that every assessment will be reimbursed.
The required coverage concerns assessments resulting from direct losses to condominium property caused by a peril covered by the unit-owner policy. Associations have authority to levy assessments for maintaining, repairing, and replacing common elements and association property. That authority does not make every assessment an insured event. Ordinary maintenance and reserve-funding assessments do not qualify merely because they are assessed.
For the required loss-assessment coverage, the deductible cannot exceed $250 for each direct property loss. If a deductible already applies to other property damage from the same direct loss, no additional deductible applies to that required coverage.
Ask the broker to confirm available limits, covered perils, exclusions, and any sublimit for assessments arising from the association’s deductible. A prominent overall limit is no substitute for reading those provisions.
Timing matters equally. The insurer’s maximum responsibility for one direct property loss is governed by the loss-assessment limit in effect one day before the occurrence. Increasing coverage after a storm does not retroactively increase the applicable limit for that storm’s loss.
Request the master-policy declarations and endorsements, latest replacement-cost appraisal, and governing documents. Add assessment notices, open-claim information, and the current budget and reserves. Together, these documents give counsel and the broker the material needed to distinguish insured exposure from costs that may remain with owners.
Ask for a written review of the deductible calculation, allocation provisions, individual coverage limits, and ownership-related endorsements. Where an answer depends on policy wording, retain that wording with the review.
The loss-assessment notice timetable calls for notice by the later of one year after the loss or 90 days after the association votes to levy the assessment, with an overall three-year limit after the damage occurred. Confirm applicability to the policy and loss date with counsel before relying on that timetable. Notify the insurer promptly rather than treating the outer deadline as a target.
For buyers weighing Aston Martin against Baccarat Residences Brickell, the useful comparison is not an assumed insurance advantage attached to a name. It is the clarity of each property’s documents and the fit between the proposed ownership structure and available coverage.
The strongest closing position rests on a coordinated file: title arrangements reviewed by counsel, insurance terms explained by the broker, and residual exposure understood by the buyer. That discipline keeps the residence itself the pleasure of the acquisition, rather than its unanswered financial question.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationHave counsel confirm the proposed structure against the condominium’s governing documents. Separately, ask the broker and any lender to approve the ownership and insurance arrangements.
Ask the broker how the proposed trust, trustee, or LLC should appear and whether endorsements are needed. Confirm residents’ coverage rather than assuming titleholder coverage addresses every interest.
No. Florida’s condominium-insurance framework uses full insurable value, replacement cost, or similar coverage rather than a unit’s resale price.
The association’s insurance appraisal or appraisal update is required at least every 36 months. Obtain the latest document and confirm its effective date.
No. The valuation appraisal establishes replacement cost; any claims appraisal provision must be reviewed separately in the actual policy for its scope and procedures.
Ask the broker to identify the insured-value base and calculate the dollar exposure under the actual policy. Counsel should separately review how deductible costs may be allocated to owners.
Florida requires residential condominium unit-owner policies to include at least $2,000 in property loss-assessment coverage. That floor is not a recommendation for a particular buyer’s exposure.
It cannot exceed $250 for each direct property loss. No additional deductible applies to that required coverage if a deductible already applies to other property damage from the same direct loss.
No. The required coverage concerns direct property losses caused by a peril covered by the unit-owner policy; ordinary maintenance or reserve-funding assessments do not qualify merely because they are levied.
An increase does not retroactively raise the applicable limit for that storm’s loss. The insurer’s maximum responsibility is governed by the loss-assessment limit in effect one day before the occurrence.