A trial retirement should leave room for a second act. Structure a South Florida purchase around realistic carrying costs, genuine residence intentions, and the homestead consequences of a future move or rental.
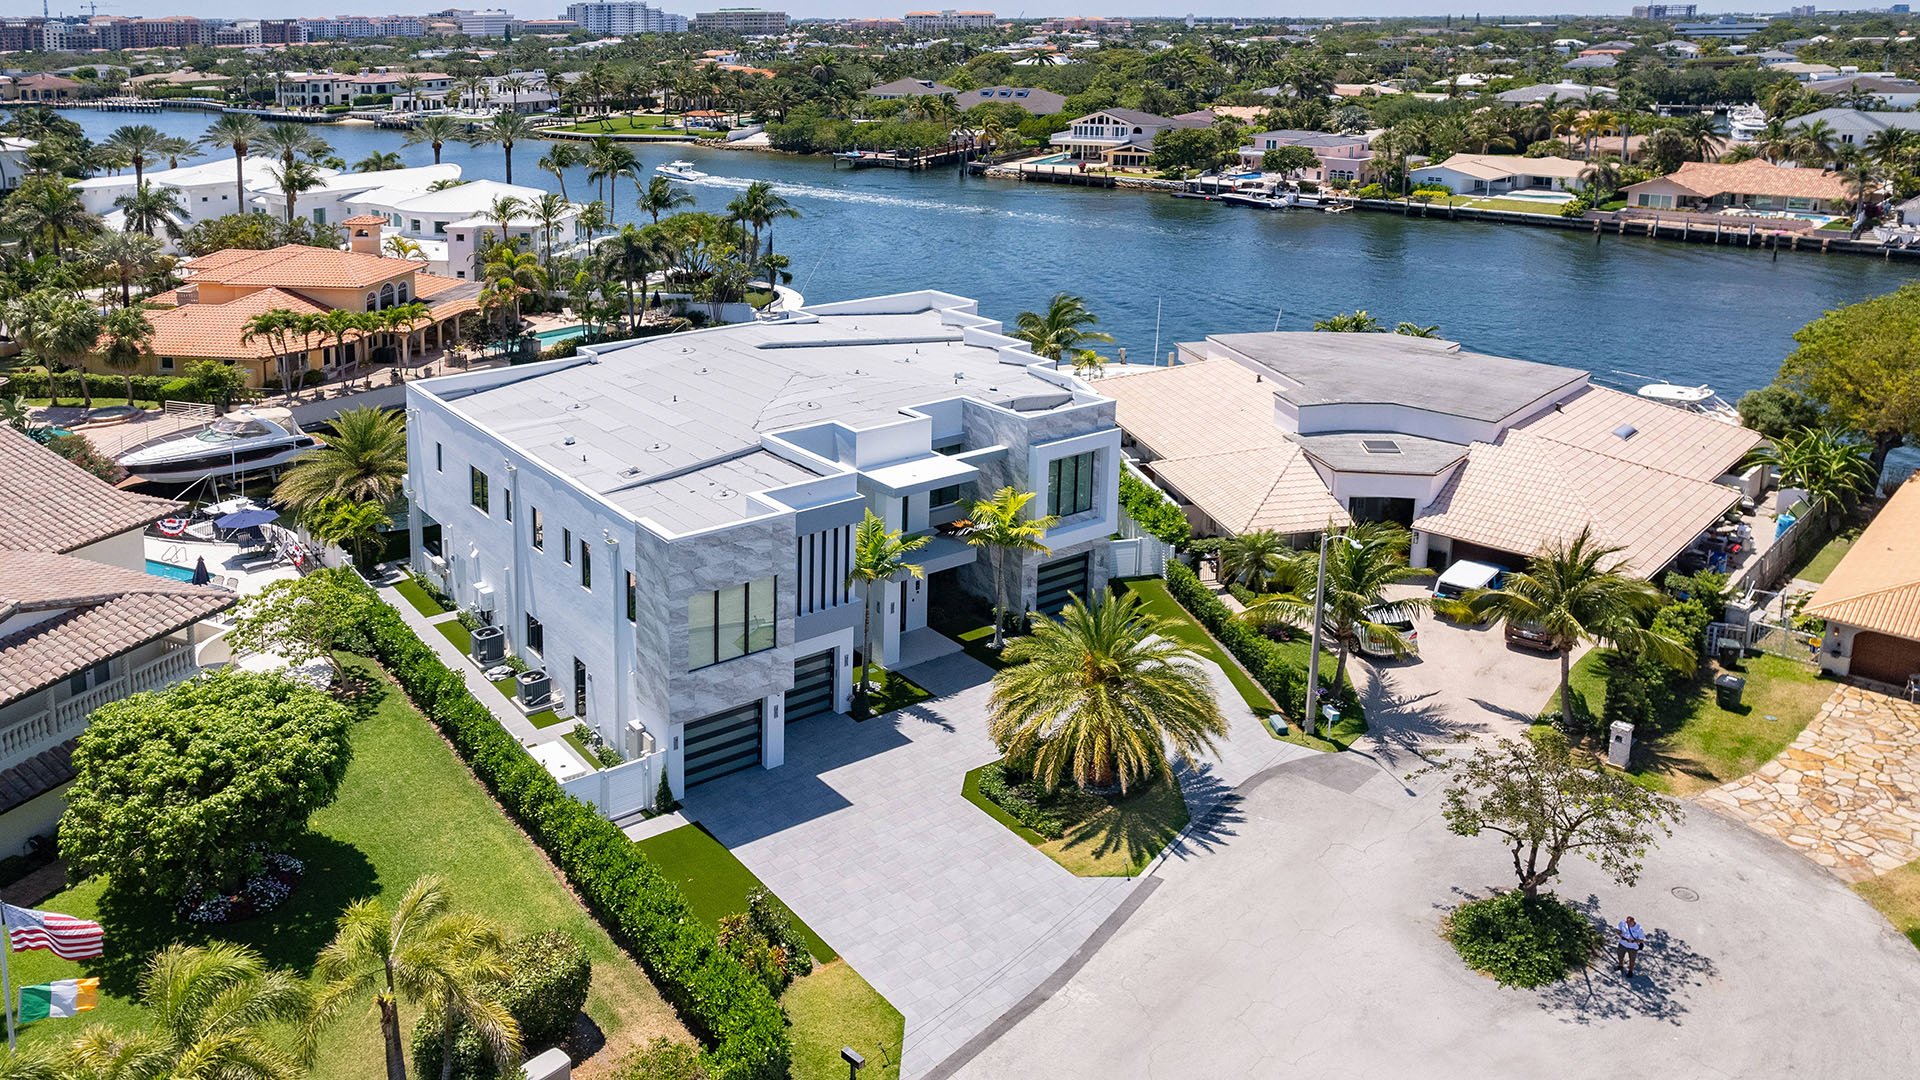
A trial retirement in South Florida can be an elegant experiment: a different daily rhythm, more time outdoors, and a home chosen for enjoyment rather than proximity to an office. The purchase becomes less forgiving if it depends on never earning another salary-or on the assumption that the residence can easily become an income property.
The stronger brief is a home that remains workable under three outcomes: retirement continues, work resumes from Florida, or work requires a move elsewhere. That means separating lifestyle preferences from financial commitments and, crucially, ownership from homestead eligibility. A seasonal retreat and a permanent residence are not interchangeable tax positions.
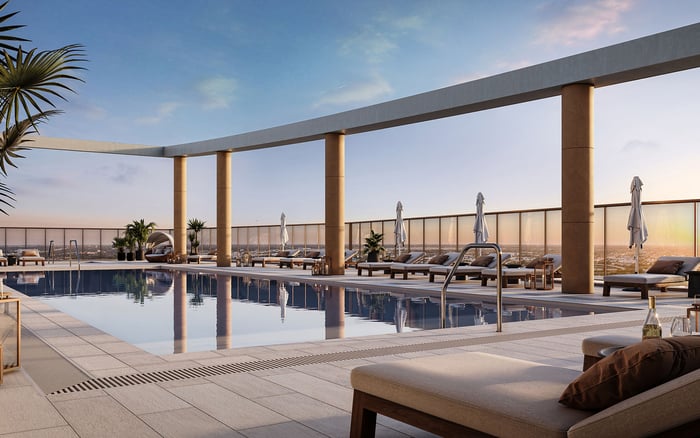
For a buyer considering Alba West Palm Beach, the first question is not simply whether West Palm Beach suits retirement. It is whether the purchase still makes sense if the next chapter includes a working week, extended absences, or two homes.
Build the initial ownership budget without assuming homestead treatment or rental income. Include acquisition costs, financing if applicable, taxes, insurance, association charges, maintenance, and a reserve for unexpected expenses. Obtain property-specific figures; a projected monthly payment is not the full cost of ownership.
Then test a return-to-work scenario. Could you carry the Florida residence while paying for accommodation elsewhere? Would a new role require travel or additional household support? How much liquidity would remain after closing and furnishing? These are planning questions, not forecasts of employment, insurance costs, or investment performance.
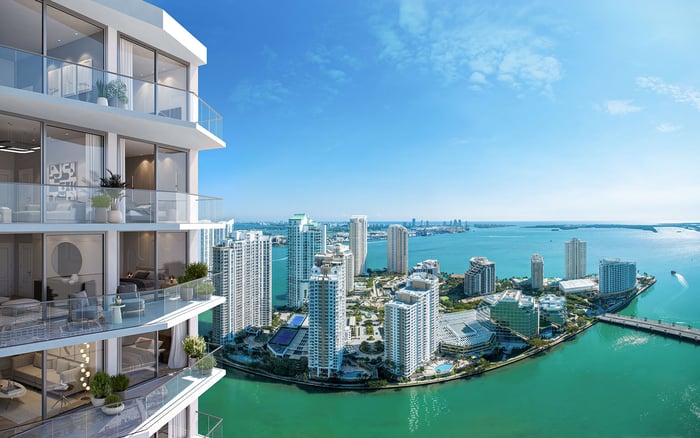
For a Brickell search that includes 2200 Brickell, assess the home against your possible working routine. Consider workspace, privacy, travel patterns, and the practicalities of leaving the residence unattended. An attractive retirement setting is no substitute for that assessment.
Florida homestead eligibility requires holding title and making the property a permanent residence. Buying a home for seasonal use during a retirement trial does not, by itself, qualify it. Permanent-residence status generally must be established by January 1 of the year for which the exemption is requested.
The distinction matters before closing, not merely when the tax bill arrives. If you are still deciding where to live permanently, have your adviser evaluate the intended use honestly. A preferred tax outcome should follow the facts of your residence, not determine how those facts are described.
A qualifying homestead may receive a property-tax exemption and the separate Save Our Homes assessment limitation. Confirm applicable exemption amounts and administrative requirements for the relevant tax year with the property appraiser.
Returning to work is not the same as changing permanent residence. Review whether the new arrangement changes how the home is occupied or used, rather than treating retirement itself as the basis for eligibility.
For someone moving between qualifying Florida homesteads, portability may preserve part of an existing tax advantage. It transfers the eligible accumulated homestead assessment difference, not the existing homestead exemption itself.
The maximum transferable assessment difference is $500,000. That is not $500,000 in tax savings. The distinction is essential when comparing the economics of staying, moving within Florida, or retaining a former home.
Portability does not bring another state's property-tax benefit into Florida. The replacement Florida homestead generally must be established within three assessment years after abandoning the previous homestead. Owners must apply for the new exemption and submit portability paperwork, generally by March 1 of the applicable tax year.
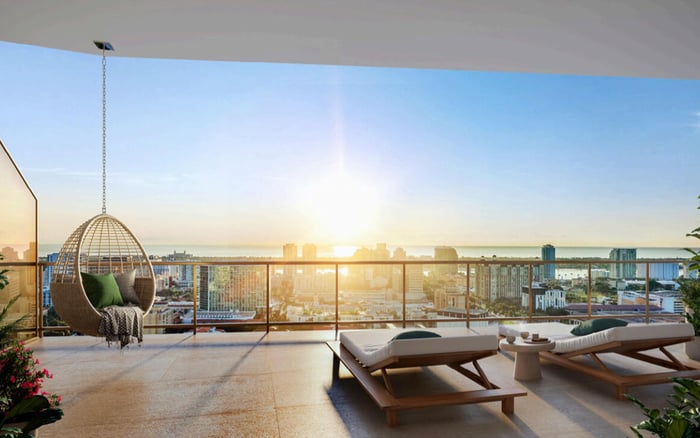
A buyer evaluating Alina Residences Boca Raton after an earlier Florida homestead should treat the Boca Raton purchase as a coordinated timing and filing exercise. Confirm eligibility and the available transfer before incorporating any benefit into the purchase budget.
“I can always rent it” is not a complete exit strategy. Turning a homestead into a rental can jeopardize its exemption. Do not assume rental income and continued homestead treatment can coexist simply because you intend to return eventually.
In Palm Beach County, renting a homestead for more than six months constitutes abandonment of the exemption. Rental use of 30 days or less per calendar year may be permitted, subject to other homestead conditions, but January 1 is excluded from permitted rental dates.
The middle ground requires particular care. Renting for more than 30 days but less than six months may be permitted in one year. Renting again for more than 30 days the following year causes loss of the exemption under the county's rules. These thresholds are neither statewide permission to rent nor confirmation that a particular building permits leasing.
Before relying on rental income, have the proposed dates and intended use reviewed for homestead consequences. Separately, verify association restrictions, applicable rental requirements, financing terms, and insurance arrangements. These are due-diligence questions, not assurances about any specific residence.
Preserving the option to sell is different from predicting appreciation or a quick transaction. Decide how much capital you are comfortable committing to a home you may own for less time than expected. Review purchase and potential sale costs with your advisers, without assuming a particular resale price or marketing period.
When considering Four Seasons Residences Coconut Grove, use Coconut Grove as the setting for that broader test: would the residence still suit you if work resumed, and could you afford to hold it if your plans changed? Neither question requires a promise about future demand.
Be equally deliberate about furnishing and customization. Set a budget that reflects the possibility of changing course, rather than treating the first year of retirement as a permanent commitment.
Put three scenarios on one page: remain in retirement, resume work while keeping Florida as your permanent residence, or relocate and reassess whether to retain, rent, or sell. For each, identify carrying costs, cash reserves, intended occupancy, and decisions requiring tax or legal review.
The objective is not to eliminate uncertainty. It is to prevent a beautiful home from making the next professional decision for you. Buy something you can enjoy without needing retirement, rental income, and tax benefits all to unfold exactly as planned.
Explore a South Florida residence that fits both your retirement ambitions and your alternatives with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility requires holding title and making the property a permanent residence; seasonal ownership alone does not qualify.
Permanent-residence status generally must be established by January 1 of the year for which the homestead exemption is requested.
Employment status alone is not the eligibility test described here. Review whether returning to work changes the home's permanent-residence status, occupancy, or rental use.
No. The homestead exemption and the Save Our Homes assessment limitation are separate benefits that may apply to a qualifying residence.
It represents up to $500,000 of transferable homestead assessment difference, not $500,000 in tax savings.
No. Florida portability applies between qualifying Florida homesteads, not to property-tax benefits from another state.
The replacement homestead generally must be established within three assessment years after abandoning the previous one. New homestead and portability applications are generally due by March 1 of the applicable tax year.
Rental use of 30 days or less per calendar year may be permitted, subject to other homestead conditions. January 1 is excluded from permitted rental dates, and separate property restrictions still need review.
More than six months constitutes abandonment of the exemption. Renting for more than 30 days but less than six months may be permitted in one year, but repeating rental use exceeding 30 days the following year causes exemption loss.
Test affordability without assuming homestead benefits or rental income. Include the possibility of carrying the Florida home while work requires accommodation elsewhere.