
A London-to-Palm Beach Gardens purchase calls for more than a dollar budget. Align sterling conversions with contractual deposits, closing costs and lender reserve requirements while protecting the liquidity needed to maintain two homes.
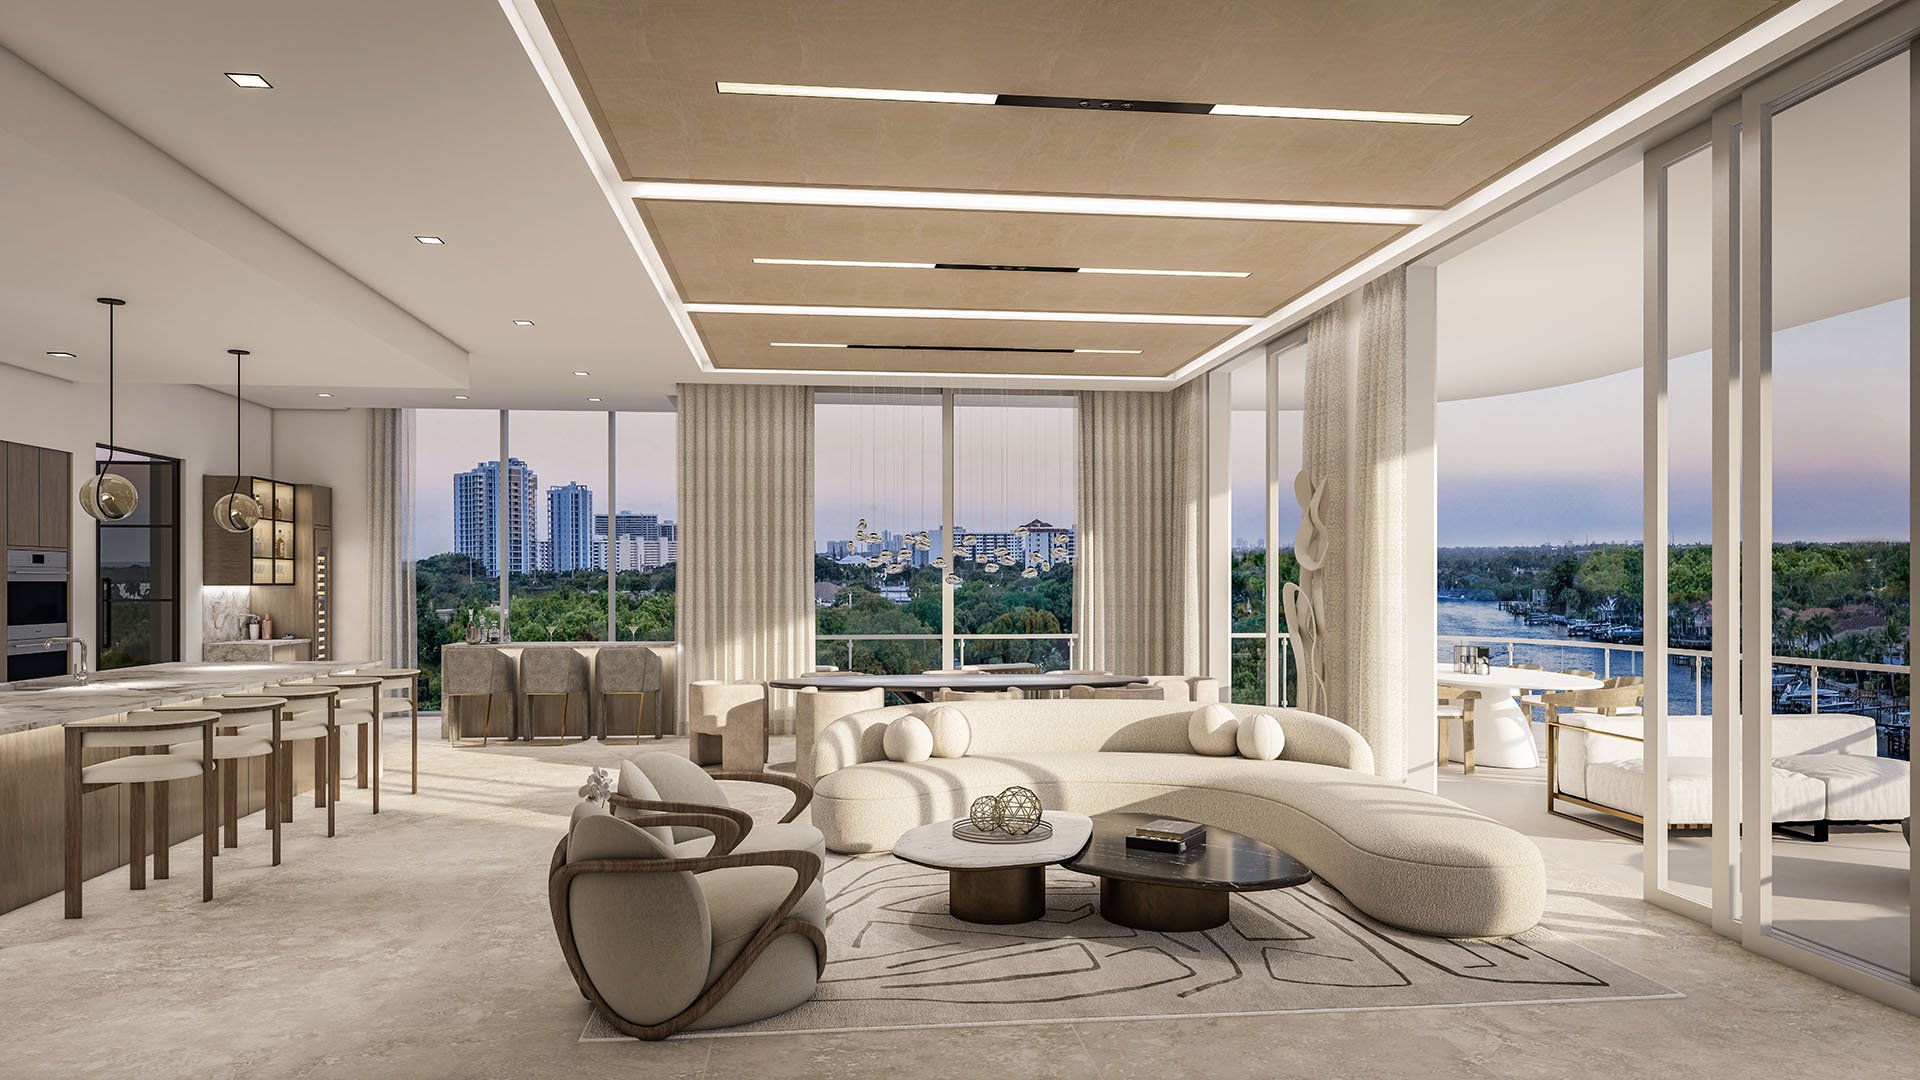
A life shared between London and Palm Beach Gardens should feel effortless once the front door closes. That ease begins with a funding plan that separates the residence’s price from the timing, currency and availability of the money used to acquire it. A fixed dollar purchase price does not fix the sterling cost.
For a buyer considering The Ritz-Carlton Residences® Palm Beach Gardens, the financial brief should sit beside the residential brief from the outset. Before committing, establish which funds will meet each contractual payment, which remain exposed to GBP/USD movements and which must remain accessible after closing.
The governing distinction is simple: money available to complete the purchase is not the same as money available to sustain ownership. A considered plan must satisfy both tests without assigning the same funds to two purposes.
Record the exchange rate when making an offer. Use it as a benchmark for subsequent funding decisions, rather than allowing each market movement to redefine the budget. Keep the property’s dollar price and indicative sterling equivalent visible together, then refresh the calculation using the actual FX quote available to you.
If sterling weakens against the dollar before a payment has been funded, the sterling required increases even though the seller receives the same dollar amount. That exposure persists between commitment and completion. A longer interval or staged payment arrangement makes the calendar particularly important.
There is no universal best day to exchange. The more useful question is how much uncertainty the household can comfortably retain before each payment falls due. Ask your FX adviser to compare funding approaches against those obligations, not a prediction of where sterling might trade next.
Separate initial escrow, additional contractual deposits, the closing balance, transaction costs, lender reserves and household operating liquidity. These are planning categories, not a universal contract structure. Assign each an amount, a deadline and an identified funding source.
Use the executed contract to establish each deposit amount and deadline. Do not assume that an indicative convention applies to a particular residence or that later deposits will follow a standard schedule.
If the search extends into West Palm Beach, a comparison with Alba West Palm Beach should include the proposed payment calendar alongside the residential considerations. Compare the documented obligations for each purchase; do not infer deposit terms from a project’s name or location.
For every contractual payment, identify when dollars must be available. Add any lender account-seasoning requirement as a separate entry. A calendar focused only on closing can miss an earlier deadline that determines whether financing is ready.
A forward contract can fix an exchange rate for a future payment, reducing exposure to sterling weakening before completion. In a property purchase, its purpose is budget certainty-not a guarantee of the most favorable eventual exchange rate.
That certainty carries its own liquidity obligations. A forward may require a deposit or collateral, and a delayed or cancelled purchase can create costs. Before agreeing to one, review the funding requirement and the extension and termination terms. Consider the FX arrangement and the property contract together, while recognizing that their obligations remain distinct.
Ask the adviser to explain what happens if a payment date changes, the purchase does not proceed or collateral is required. Cash committed to supporting the forward also belongs in the liquidity plan. It should not consume money intended for escrow, settlement or the household’s remaining reserves.
Closing costs require a separate allocation from the purchase price and, for financed buyers, the down payment. Obtain a transaction-specific written estimate rather than relying on a broad percentage allowance.
Ask the settlement professional to identify the applicable title and settlement charges, taxes, insurance items and prorations, including which party is responsible for each. For a financed purchase, reconcile that estimate with the lender’s charges so the funding plan neither omits nor double-counts an expense.
When comparing Forté on Flagler West Palm Beach with a Gardens option, use a separate settlement estimate for each contemplated transaction. Compare the complete funding requirements, not simply two asking prices with an identical percentage added.
Living between London and Palm Beach Gardens does not itself establish a buyer’s mortgage classification. Foreign-national financing terms depend on the lender, borrower and property. Obtain written confirmation of the applicable down payment rather than assuming a standard percentage.
Ask whether the lender requires reserves beyond the funds spent at closing. If reserves are expressed in months of principal, interest, taxes and insurance, known as PITI, confirm the dollar amount and how long the funds must remain available.
Also confirm which accounts are eligible, whether funds must be held in a U.S. account and whether an account-seasoning period applies. Put any required account-funding date on the calendar separately from the closing date.
These requirements create two distinct tests: having enough to close and retaining the required liquidity afterward. Do not treat lender reserves as available purchase-wire funds or leave an early account-funding requirement until the settlement balance is due.
The final plan should preserve financial room for both homes. Keep London household liquidity, Florida operating funds and lender-required reserves clearly identified rather than treating every accessible balance as interchangeable. Any overlap should be deliberate and consistent with the lender’s written conditions.
Before completion, reconcile the executed contract, settlement estimate, lender requirements and FX commitments. Confirm what has already been paid, what remains due, what must stay untouched and which future dollar obligations remain exposed to sterling movements. The objective is not to predict currencies perfectly. It is to arrive at ownership without making everyday flexibility dependent on the next exchange rate.
For a discreet conversation about a residence suited to your London and Palm Beach Gardens life, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes. GBP/USD movements change the sterling required for dollar payments that have not yet been funded or fixed through an exchange arrangement.
It establishes a benchmark for the sterling budget and later funding decisions. It does not lock the exchange rate.
There is no universal optimal exchange date. Funding decisions should reflect contractual deadlines, available liquidity and tolerance for currency uncertainty.
It can fix an exchange rate for a future payment, reducing exposure to sterling weakening. Deposit or collateral requirements and extension or cancellation costs must also be considered.
The executed contract determines the deposit amount and payment deadline. Do not assume a standard percentage or schedule applies to every residence.
Obtain a transaction-specific written settlement estimate separate from the purchase price. Confirm which charges, taxes and prorations are the buyer’s responsibility.
Keep closing costs separate from the down payment. Reconcile the settlement estimate with the lender’s charges to avoid omissions or double-counting.
No; terms depend on the lender, borrower and property. Obtain the applicable down-payment requirement in writing.
Ask the lender for the required dollar amount, eligible accounts and how long the funds must remain available. Distinguish these reserves from money spent to complete the purchase.
An account-seasoning condition can require funding before closing. Confirm whether one applies and record the lender’s written deadline separately.