A disciplined resale review at 2200 Brickell connects current condominium documents, a reconciled estoppel certificate, and carefully negotiated approval contingencies to the closing calendar.

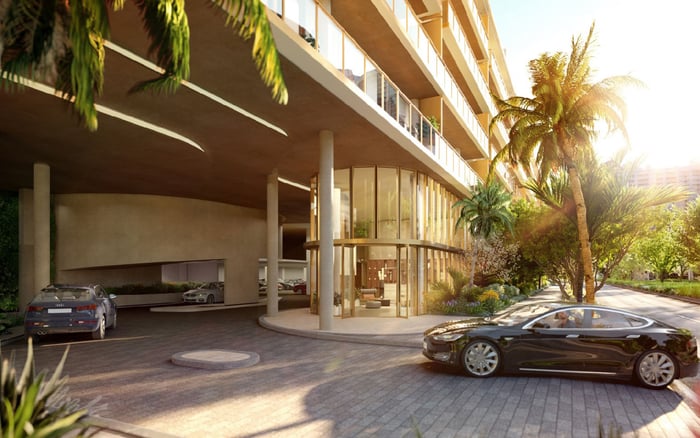
At 2200 Brickell, located at 2200 Brickell Avenue in Miami’s Brickell neighborhood, a five-story, 103-residence development offers a more intimate expression of urban luxury. Yet a resale purchase warrants scrutiny beyond proportions and finishes. The governing documents, association account, and any approval requirements deserve equal attention.
A beautifully resolved floor plan cannot compensate for an unresolved closing condition. For the buyer, the objective is to coordinate three distinct tracks: delivery of the current condominium documents, issuance and reconciliation of the estoppel certificate, and satisfaction of any applicable association-approval requirement. None substitutes for another.
The practical aim is to translate the appeal of an address into a purchase process with clear responsibilities, documented answers, and manageable deadlines.
Under Florida’s condominium resale-disclosure provisions, a purchaser who has entered into a purchase contract is entitled to specified current condominium documents at the seller’s expense. These include the declaration of condominium, association articles of incorporation, bylaws, association rules, specified financial information, and the condominium frequently asked questions and answers document.
Build a delivery log rather than accepting a folder as proof of completeness. Record each document’s title, date, amendments, and receipt date. Ask Florida condominium counsel to identify the applicable document-delivery and cancellation deadlines. A delivery acknowledgment should reflect what actually arrived-not what the parties expect to receive later.
Separate the statutory package from additional diligence requests. Ask for current budgets, financial statements, insurance information, minutes, assessment notices, and the application package, if applicable. These requests support a fuller review; they do not imply that every item carries the same statutory delivery requirement.
Applicable inspection disclosures can include a turnover inspection report for qualifying inspections performed on or after July 1, 2023. Have counsel determine applicability and request the relevant records. Do not infer developer-turnover status from the building’s scale or appearance.
For buyers also considering Una Residences Brickell, use the same document checklist while keeping each property’s governing provisions and transaction type separate. Marketing materials cannot establish the current obligations attached to a particular resale.
Florida condominium associations must issue an estoppel certificate within 10 business days after receiving a qualifying written or electronic request. Eligible requesters include the unit owner, the owner’s designee, a unit mortgagee, or the mortgagee’s designee. Coordinate the request through an eligible party; do not assume that any buyer inquiry starts the clock.
Each association must designate on its website a person or entity and an address for receiving estoppel requests. Confirm the designated recipient and preserve evidence of receipt. An unanswered message sent elsewhere is not a sound basis for the closing calendar.
The certificate generally has a 30-day effective period when delivered electronically or by hand, and a 35-day effective period when delivered by regular mail. Neither period should be confused with the issuance deadline. Ask the closing team to confirm the applicable expiration date and allow time for review and corrections.
Ordering too late compresses the audit; ordering too early risks a certificate that no longer covers the intended closing. Work backward from the target date with the closing agent, allowing for issuance, reconciliation, and any needed update. If closing moves, recheck the certificate’s effective period immediately.
Treat the estoppel as a document to reconcile, not merely an attachment to circulate. Ask the closing team to compare it with the seller’s association ledger and assessment notices. Confirm the unit identification and check whether the amounts to be collected at closing align with the written records.
A useful review separates three questions:
What amounts does the certificate identify for the transaction?
Do the ledger and assessment notices support those amounts?
Are proposed assessments or other unresolved matters being investigated separately?
Where figures or descriptions conflict, request written clarification and, where appropriate, a corrected certificate. A verbal assurance should not become the basis for an unexplained adjustment on the closing statement.
Investigate proposed assessments separately through current minutes, notices, and written questions. The absence of a charge on the certificate is not a complete answer about future financial exposure. Have counsel address assessment allocation in the contract and the handling of notices received between execution and closing. The commercial question is not only how much is owed, but which party bears it under the agreed terms.
Do not assume that association approval is required at 2200 Brickell, that it follows a particular timetable, or that submitting an application guarantees a decision before closing. Obtain the current governing provisions and written application instructions before structuring the contingency.
If approval is required, ask counsel to negotiate protections covering:
Who obtains, completes, submits, and pays for the application.
How receipt and completeness will be documented.
How additional-information requests affect the timetable.
The outside date for approval and any agreed extension mechanism.
Cancellation rights and deposit-return provisions if approval is denied or delayed.
These are proposed contractual protections, not automatic statutory rights or confirmed building policies. Their value lies in addressing foreseeable delays before the deposit and closing date become points of disagreement.
A comparison with The Residences at 1428 Brickell should likewise remain document-specific. Do not carry assumptions about approval procedures or contract protections from one address to another. The governing documents and negotiated purchase agreement should establish the requirements for the transaction under review.
Use one closing calendar with separate entries for document delivery, counsel’s review deadlines, estoppel issuance and expiration, and any application milestones. Assign a responsible party to each task. A date alone offers little protection when several advisers are working simultaneously.
Before authorizing closing, ask counsel and the closing agent to confirm that discrepancies have been resolved in writing, any required approval has been obtained, and the certificate remains effective for the scheduled closing. Review any new notices and ensure the final financial allocations reflect the contract.
The strongest buyer’s audit does not promise a frictionless transaction. It makes the remaining conditions visible early enough to address them. At 2200 Brickell, that discipline keeps the residence itself in focus without leaving the mechanics of ownership to assumption.
For a considered approach to South Florida luxury real estate, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversation2200 Brickell is located at 2200 Brickell Avenue in Miami’s Brickell neighborhood. The development contains 103 residences across five stories.
Under Florida’s condominium resale-disclosure provisions, a purchaser who has entered into a purchase contract is entitled to specified current documents at the seller’s expense.
Review the declaration of condominium, association articles of incorporation, bylaws, and association rules. The statutory package also includes specified financial information and the condominium frequently asked questions and answers document.
Ask counsel to identify applicable inspection disclosures, including a turnover inspection report for qualifying inspections performed on or after July 1, 2023. Applicability should be confirmed for the transaction.
The association must issue it within 10 business days after receiving a qualifying written or electronic request. Coordinate receipt with the designated recipient.
Eligible requesters include the unit owner, the owner’s designee, a unit mortgagee, or the mortgagee’s designee. Buyers should coordinate through an eligible party.
A certificate delivered electronically or by hand generally has a 30-day effective period; one delivered by regular mail generally has a 35-day effective period. Have the closing team confirm the applicable expiration date.
Compare the certificate with the seller’s association ledger and assessment notices, and seek written clarification of discrepancies. Investigate proposed assessments separately.
Do not assume approval is required or follows a particular deadline. Confirm the current governing provisions and written application instructions for the transaction.
The recommended cancellation and deposit-return provisions are proposed contractual protections, not automatic statutory rights. Have counsel negotiate their terms alongside application responsibilities and an outside approval date.