Five Sunny Isles Beach residences form a service-oriented shortlist for occasional occupancy. For buyers using trusts or entities, the decisive work is confirming ownership eligibility and aligning master-policy exposure, HO-6 coverage, loss-assessment protection, and association finances.
A lock-and-leave residence should make departure feel uncomplicated. Concierge support, controlled access, and staffed common areas can ease the practical demands of occasional occupancy. For buyers taking title through a trust or entity, however, convenience is only part of the acquisition. An equally important question is what financial exposure remains while the owner is elsewhere.
The five residences below form an editorial shortlist for lock-and-leave operations-not a ranking of insurance costs or deductible exposure. None should be assumed to offer predictable insurance exposure, stronger reserves, or confirmed eligibility for a particular trust or entity. Predictability is a diligence objective, not an amenity.
At Armani Casa Sunny Isles Beach, the documented service profile offers a compelling lifestyle starting point. The purchase decision still requires a separate review of association insurance, unit coverage, and financial capacity.
1. Residences by Armani/Casa - 18975 Collins Avenue
Concierge, valet, on-site management, and security place Armani/Casa first on this service-oriented shortlist. Its resort amenities include an oceanfront heated pool, hot tub, poolside food and beverage service, a two-story spa, and an ocean-view fitness center.
For an occasional resident, the appeal lies in the combination of staff support and extensive amenities. Neither establishes a smaller master deductible or lower assessment exposure. Evaluate the operating experience and insurance exposure separately.
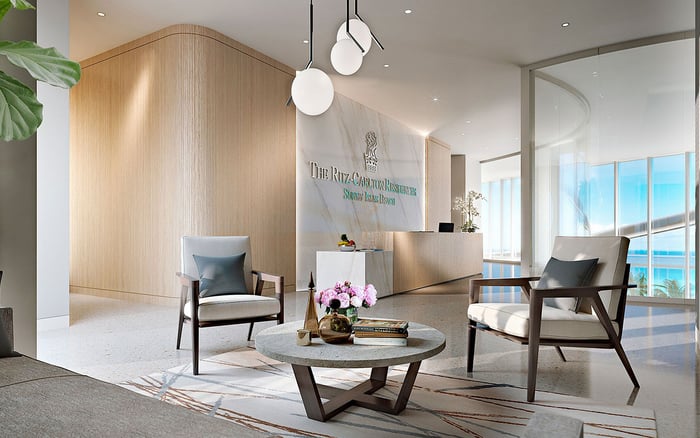
2. The Ritz-Carlton Residences, Sunny Isles Beach - 15701 Collins Avenue
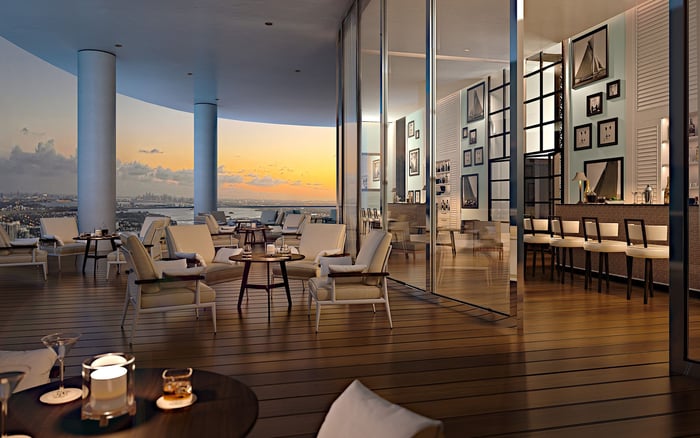
Branded concierge services and resident-support amenities earn the second position. Beachfront dining, pool facilities, private club-level dining and lounge areas, a full-service spa, fitness facilities, and a business center support its appeal for periodic stays.
The branding informs the lifestyle proposition; it does not prove favorable master-policy terms. Before selecting the residence for trust or entity ownership, confirm both association acceptance and the proposed insurance arrangement.
3. Ocean One - 19333 Collins Avenue
Near 194th Street, Ocean One offers a clearly defined operational package: 24-hour security, valet, concierge, and secure key-card elevators with private foyers. A private beach, heated pool and spa, fitness center, and tennis courts complete its documented amenities.
That specificity makes it a useful candidate for buyers prioritizing access control and staffed support. It does not establish how a storm deductible would be funded or allocated. Those questions require a review of association documents and policy terms.
4. Jade Signature - 16901 Collins Avenue
Jade Signature is a luxury oceanfront candidate for occasional occupancy. Its position is provisional: its service profile is less firmly established here than those of the leading candidates, while current insurance and reserve exposure remain unverified.
Consider it a residence to investigate, not a demonstrated insurance advantage. Confirm current staffing, owner-support arrangements, association finances, and policy terms before comparing it with the more clearly documented service packages above.
5. King David of Sunny Isles Condominium - Sunny Isles Beach
King David is a conditional candidate. Replacement-cost coverage and the possibility of reserve-funded deductibles warrant inquiry, but neither establishes current policy limits, deductible amounts, or financial resilience.
Its current service package also requires direct association verification. Resolve those questions before treating it as a lock-and-leave alternative to the other residences. No oceanfront designation or favorable insurance ranking is implied.
The appeal of The Ritz-Carlton Residences® Sunny Isles is clear for an owner who values concierge support and resident amenities. Yet neither staffing nor branding can substitute for a master-policy review.
An association can carry insurance and still need additional funding from owners. Substantial deductibles, insufficient policy limits, and uncovered losses may leave a funding gap. Associations may draw on reserves or impose special assessments to meet deductibles, so the monthly association fee is not a complete measure of exposure.
Request current master-policy declarations, coverage summaries, the deductible schedule, windstorm details, flood-policy information, and available claims documentation. Ask management how each relevant deductible would be funded and how any owner allocation would be determined. Compare actual documents, not amenity descriptions.
Association documents and master-policy terms define the boundary between association-insured property and the owner's responsibilities. An HO-6 policy can cover interior finishes, flooring, cabinetry, personal property, liability, loss of use, and qualifying loss assessments, subject to its terms.
Have an insurance broker evaluate the actual master policy alongside the proposed unit policy. Ask which interior elements require owner coverage, what limits suit the residence, and which exclusions or deductibles remain. A beautifully finished apartment deserves a coverage review that reflects its interior, not simply its purchase price.
Loss-assessment protection requires particular care. It does not automatically reimburse every association charge. Coverage depends on limits, exclusions, deductibles, and the cause of the assessment. Ask specifically whether it covers an assessment used to fund a master-policy deductible, and choose a limit informed by the potential owner share.
When considering Jade Signature Sunny Isles Beach, give the association's financial condition the same attention as the residence itself. Insurance exposure cannot be evaluated apart from reserves and anticipated work.
Reserve funds are separate from operating funds and support capital repairs and replacements, including roofs, elevators, pool decks, and structural components. A reserve study estimates component useful lives and replacement costs and recommends contributions. It is central to understanding future assessment pressure.
Review current budgets and year-to-date financials for insurance-cost increases, reserve contributions, operating deficits, and assessment exposure. Include recent engineering assessments, maintenance schedules, and special-assessment information. Structural work, storm damage, substantial deductibles, and litigation can generate assessments; insurance is not a universal solution to those costs.
Treat ownership eligibility as a separate approval track. Ask the association and legal counsel to confirm whether the intended trust, LLC, corporation, and occupancy arrangement are acceptable. Do not infer acceptance from a building's luxury positioning or service package.
Ask the insurance broker to confirm how the proposed owner and intended occupants should be reflected in the coverage. Then weigh three distinct considerations: service suitability, ownership acceptance, and residual financial exposure. A residence belongs on the final shortlist only when those answers work together.
The strongest lock-and-leave choice is not necessarily the most elaborate building. It is the one whose services suit the buyer and whose documented insurance and financial obligations the buyer can knowingly accept.
Explore your Sunny Isles Beach shortlist with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt ranks five candidates for lock-and-leave operations and service appeal. It does not rank verified insurance costs, deductibles, reserve strength, or trust and entity eligibility.
Residences by Armani/Casa ranks first for its documented concierge, valet, on-site management, security, and resort amenities. Those services do not establish lower insurance exposure.
No. Substantial deductibles, insufficient limits, and uncovered losses can leave an association needing additional funding from owners.
Request current master-policy declarations, coverage summaries, deductible schedules, windstorm details, flood-policy information, and available claims documentation.
An HO-6 policy can cover interior finishes, flooring, cabinetry, personal property, liability, loss of use, and qualifying loss assessments. Coverage depends on the policy's terms.
No. Coverage depends on policy limits, exclusions, deductibles, and the cause of the assessment, so master-deductible assessments require specific broker review.
Eligibility for a particular trust, LLC, corporation, or occupancy arrangement is unverified. Obtain confirmation from the association and legal counsel before proceeding.
Reserve studies estimate component useful lives and replacement costs and recommend contributions. They help buyers evaluate future assessment pressure alongside budgets and financial statements.
Ocean One documents 24-hour security, valet, concierge, and secure key-card elevators with private foyers. These operational features do not establish favorable deductible or reserve exposure.
Jade Signature's service profile is less firmly established in this comparison, while King David's current services and insurance terms need direct verification. Neither is presented as a proven insurance advantage.