A Hallandale Beach luxury condominium purchase deserves the same discipline as any significant family-office acquisition. Align escrow diligence, independently verified wire instructions, written approval authority, and a tailored retention policy before committing funds.
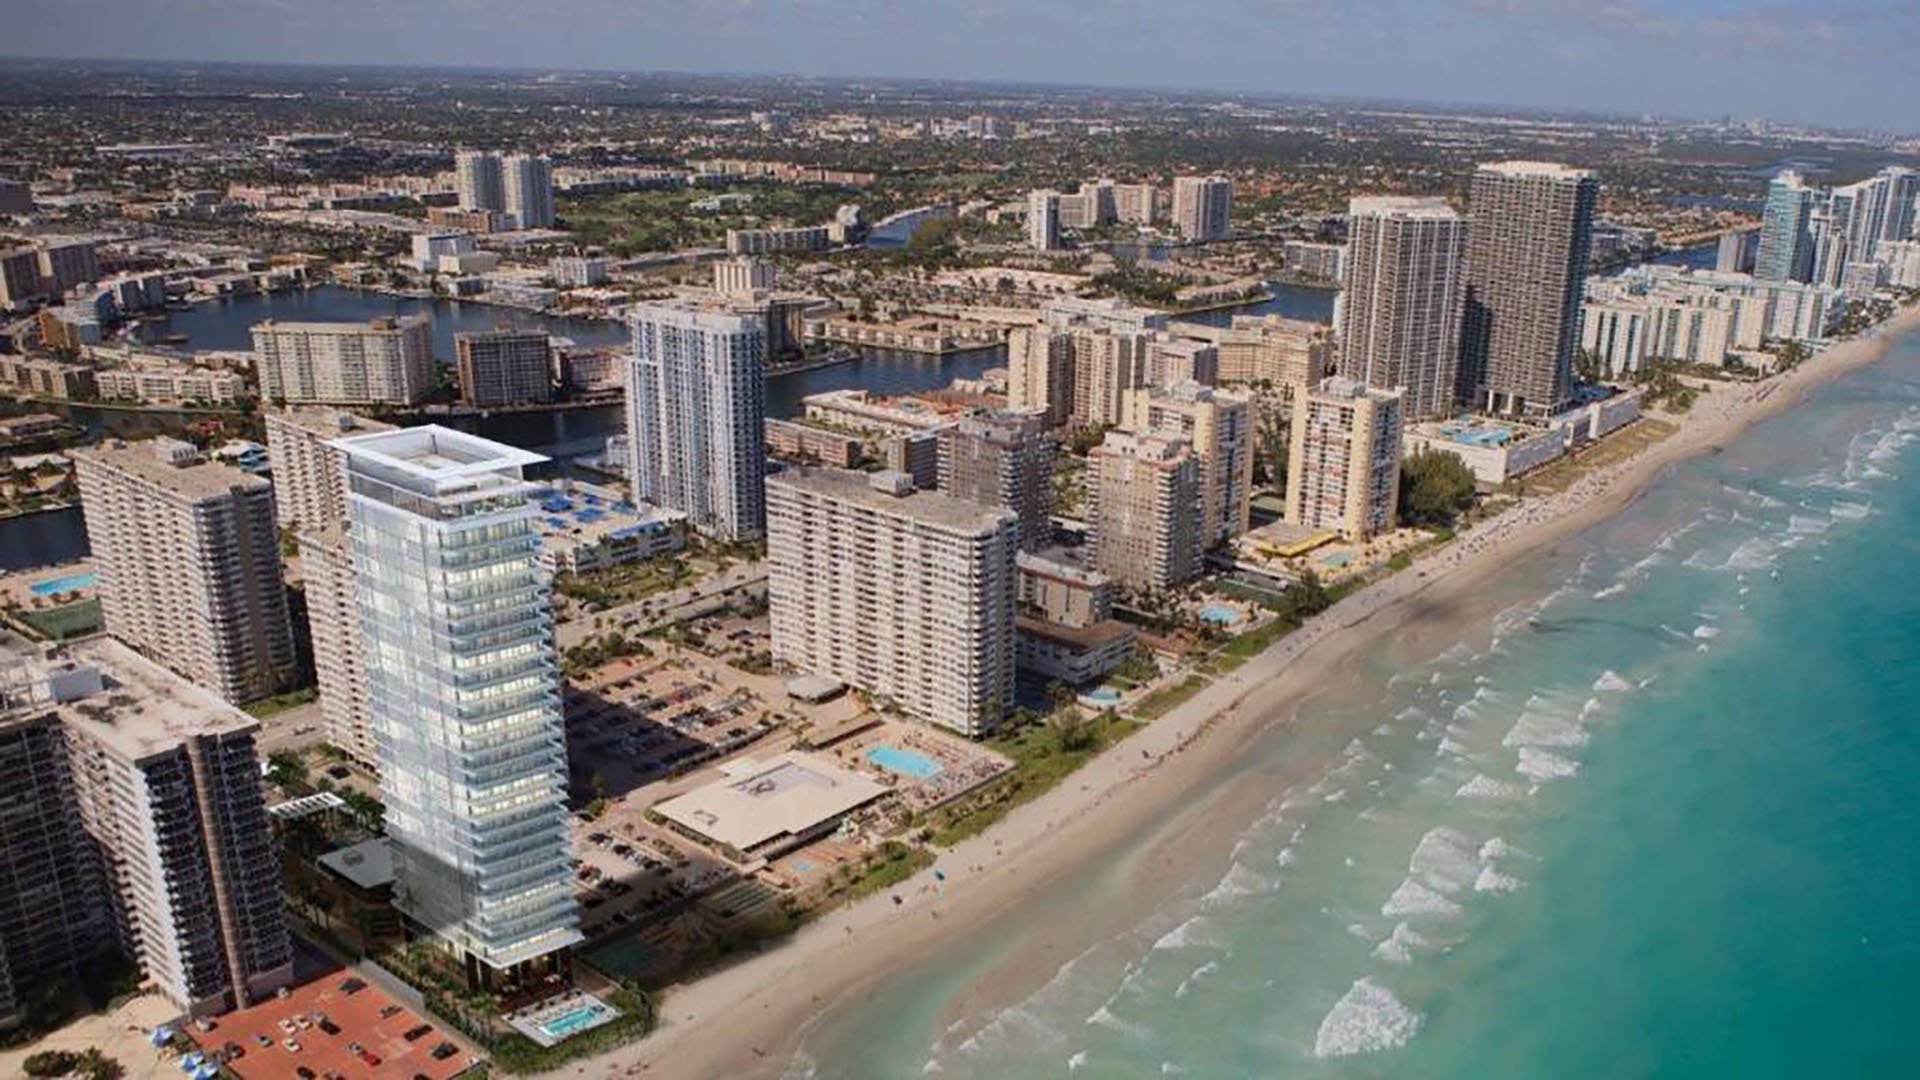
A luxury condominium purchase in Hallandale Beach is both a lifestyle decision and a capital commitment. For a family office, the residence must pass two distinct tests: suitability for the household and a transaction structure the office can approve, fund, and document with confidence. The second deserves attention before a contract becomes urgent.
Whether the shortlist includes 2000 Ocean Hallandale Beach or another residence, architectural appeal is no substitute for payment diligence. The questions are practical: Who holds the deposit? When can it be released? Who may authorize a wire? What evidence remains after closing? Luxury branding does not establish payment security.
Make satisfactory answers part of selection, rather than administrative work deferred until the closing calendar is fixed. A written transaction-control brief can align counsel, treasury, and the purchasing principal before money moves.
Begin by identifying the transaction being approved. Developer-sale condominium deposit rules should not be treated as identical to resale escrow requirements. A family's internal payment controls may remain consistent across acquisitions, but the legal analysis must follow the actual seller, contract, and construction circumstances.
Florida's condominium framework contains distinct deposit, disclosure, and association-record requirements. Review them together without assuming that compliance in one area resolves questions in another. Receiving disclosure documents, for example, does not replace an understanding of how purchase funds may be held or disbursed.
When evaluating Shell Bay by Auberge Hallandale, apply that transaction-specific inquiry rather than drawing conclusions from the project's name. Counsel should confirm the governing statutory version and applicable exceptions. The deposit provisions discussed here reflect the 2023 version of Section 718.202; they do not determine the law governing a particular purchase today.
Before signing, request written confirmation of the escrow holder, deposit schedule, applicable escrow arrangement, and contractual release terms. Have counsel explain the treatment of each installment, including the circumstances in which funds may leave escrow. Review the payment calendar and release provisions as one decision.
Florida's developer condominium deposit provisions require separate records for each condominium or proposed condominium for which deposits are accepted. Where one escrow account holds deposits, the escrow agent must maintain separate accounting for each purchaser and for amounts receiving different statutory treatment. Separate accounting is not a promise that every purchaser has a separate bank account.
Payments exceeding 10% of the purchase price and received before construction is completed are subject to special escrow requirements and statutory exceptions. Do not describe those amounts as unconditionally protected from developer use. Before approving the funding obligation, ask counsel to identify the treatment of each installment and any permitted use or release.
Agree on a verification procedure with the closing team before the office receives its first funding request. Establish a trusted telephone contact independently, then verbally confirm payment instructions before sending funds. A number included in an unexpected message should not become the sole basis for verification.
Recommended practice is to record who performed the callback, whom they reached, when verification occurred, and which version of the instructions was confirmed. Keep that evidence with the payment approval. If instructions change, pause payment and repeat independent verification rather than relying on the apparent continuity of an email conversation.
Ask how the closing team delivers sensitive documents, manages access, and confirms receipt of funds. Secure portals, multifactor authentication, role-based access, segregated trust accounts, and reconciliation procedures are useful diligence topics. Do not assume every provider uses them-or that a portal eliminates the need for a callback.
A prudent family-office policy separates payment preparation from authorization to release funds. Dual authorization, an approval matrix, an entity-authority file, and recorded approval times are recommendations for internal governance, not verified statutory mandates for every condominium buyer.
Identify the acquiring entity and authorized signers early. Ask counsel which authority documents the transaction requires, and keep approved versions accessible to those responsible for execution. Treasury should know who can approve a scheduled installment, a revised amount, or a change to the receiving instructions.
The approval record should connect the contract obligation, counsel's review, verified instructions, and final payment authorization. If a deadline approaches before these elements are complete, escalate to the designated decision-maker rather than allowing urgency to become an informal exception. Any approved exception should remain visible in the file.
A broader search may extend into Sunny Isles Beach, including Bentley Residences Sunny Isles. Compare more than the residence itself: examine whether the proposed transaction provides clear escrow terms, a workable approval timetable, and an agreed wire-verification process.
The same approach applies when considering Turnberry Ocean Club Sunny Isles. These are selection principles, not claims about either project's payment practices. Each proposed purchase deserves its own legal review and written control brief.
Consistency matters most when several family members, advisers, or entities participate. A common approval standard allows the office to compare transactions without mistaking a familiar brand or location for a verified funding arrangement.
Florida condominium association official records generally must be maintained within the state for at least seven years, unless another legal requirement applies. Certain official records must be maintained permanently from the association's inception. These association obligations do not establish a universal seven-year retention period for a purchaser's family-office transaction file.
Instead, ask legal and tax advisers to set a buyer-specific schedule reflecting ownership, tax, financing, audit, and litigation needs. Separate enduring ownership documents from payment evidence and routine correspondence; their purposes may differ. Preserve amendments and final executed versions so the approved transaction can be reconstructed.
A recommended closing package includes the signed contract and amendments, relevant escrow documents, deposit confirmations, wire-verification records, approvals, closing statements, and final ownership documents. Before closing, agree on who will collect the package, with access restricted to appropriate personnel.
Before committing, the family office should be able to explain where funds go, when they may be released, who authorizes them, and how the evidence will be retained. Unresolved items belong in the decision record, not in assumptions carried forward to closing.
For a considered approach to Hallandale Beach luxury residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationConfirm the escrow holder, deposit schedule, permitted releases, wire-verification procedure, and expected closing-document package. Counsel should review the transaction-specific terms before funds are committed.
No. The legal review must distinguish developer sales from resales, even if the family office applies similar internal payment controls to both.
Separate accounting should not be equated with a separate bank account. The developer deposit provisions contemplate one escrow account with separate accounting for purchasers and amounts receiving different statutory treatment.
No. Payments exceeding 10% received before construction is completed are subject to special escrow requirements and statutory exceptions, so counsel should review their permitted treatment.
The deposit discussion reflects the 2023 version of Section 718.202. Counsel should confirm the governing version and applicable exceptions for the proposed purchase.
Verbally confirm them through a previously established, trusted closing contact before sending funds. Do not rely solely on contact details supplied in an unexpected message.
Pause payment and repeat independent verification. Preserve the confirmed instruction version and verification record with the payment approval.
It is presented here as a recommended family-office control, not a verified statutory mandate. The office should define authority and document approvals for its own acquisition structure.
No. Association official-record requirements do not establish a universal retention period for a family office's ownership and transaction records.
A recommended package includes executed agreements, relevant escrow documents, deposit confirmations, wire-verification evidence, approvals, closing statements, and ownership documents. Legal and tax advisers should determine the applicable retention schedule.