For a family office planning a Brickell acquisition, disciplined ownership begins with clear approvals, verified signing authority, protected records, and payment controls that remain effective beyond closing.
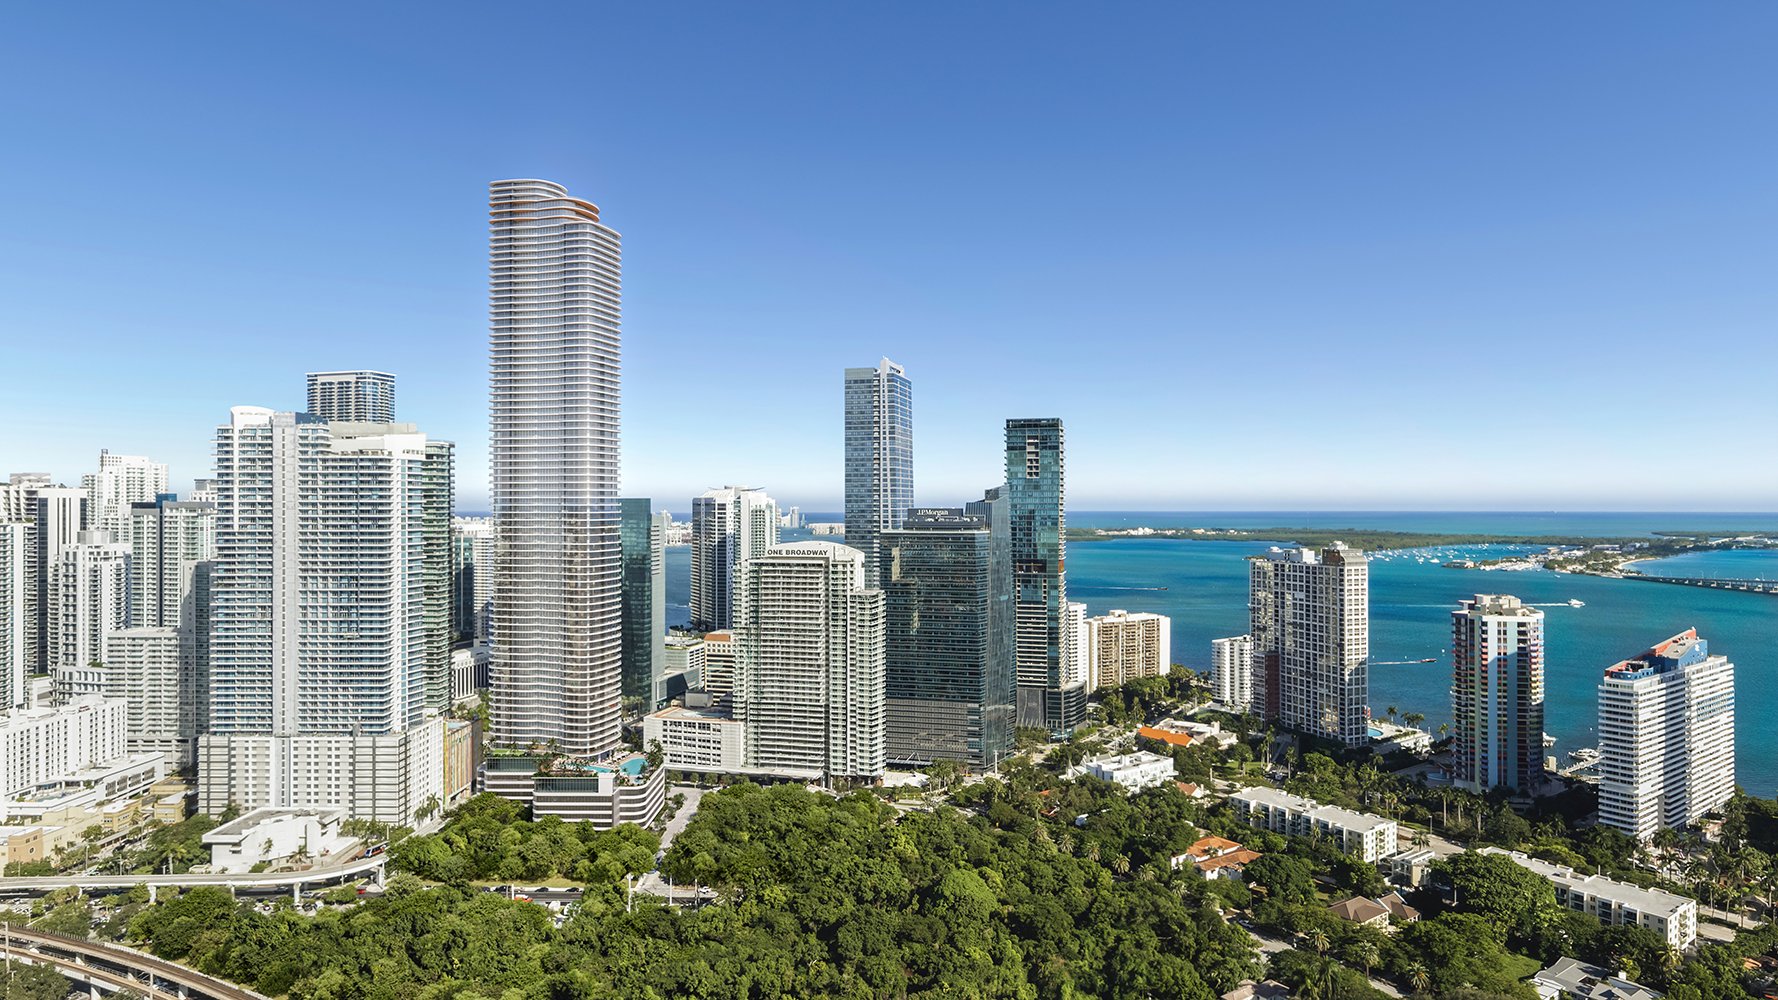
For a family office approaching Brickell from Aspen, the most consequential acquisition decisions may happen far from the residence itself. Who approves the purchase? Who can sign for the acquiring entity? Who releases the funds, and where will the evidence remain after closing?
A residence under consideration at The Residences at 1428 Brickell should prompt those questions alongside the family's preferences for the home. The operating framework should be clear before transaction deadlines dictate decisions.
The objective is not paperwork for its own sake. It is a discreet, durable structure that keeps decisions traceable and authority independent of who happens to be available. The controls discussed here are recommended operating practices for a South Florida acquisition, not a statement of universal legal mandates.
A written delegation-of-authority matrix should identify who approves acquisitions, sales, contracts, loans, capital calls, wires, vendor engagements, settlements, and exceptions. It should name the relevant family member, trustee, committee, manager, officer, or adviser rather than rely on an understanding that someone senior will decide.
Thresholds should reflect transaction type, dollar amount, entity, risk, and urgency. Routine repairs should not follow the same approval path as a major acquisition. A related-party transaction should not pass through an ordinary vendor workflow without separate scrutiny.
For each approval, record the entity or trust, property, amount, counterparty, date, approver, and conditions, and retain the supporting documents. For a potential purchase at 2200 Brickell, that means tying the decision to the specific purchasing entity and proposed transaction-not merely recording general family interest in the building.
Conditional approval also needs a clear place in the record. The file should distinguish what was authorized from what remains unresolved, so enthusiasm cannot be mistaken for an unconditional instruction to proceed.
Approval authority and signing authority are separate questions. A decision to purchase does not, by itself, establish who may execute documents for the buyer. Likewise, permission to release funds should not be treated as permission to sign every agreement associated with the transaction.
Before closing, the office should ask counsel to confirm the appropriate signer and supporting authority for the actual entity or trust. This is a transaction-specific review, not a generic checklist that establishes legal sufficiency. Ask counsel to confirm applicable entity-specific requirements and Florida execution formalities.
As an operating practice, keep the approval record, the basis for signing authority, and the executed documents connected in the repository. The protected audit trail should show who requested, reviewed, approved, executed, paid, and recorded each material action.
Emergency authority should remain accountable. Subsequent documentation should capture the rationale, amount, entity, approver, and required follow-up. An urgent decision should not become an undocumented exception that quietly governs the next transaction.
For the Brickell acquisition, establish a family-office retention policy with legal and tax advisers rather than relying on another transaction participant's files. The policy should address ownership, governance, and tax records as well as closing documents.
The office should maintain a controlled document repository with role-based permissions, version control, search, retention rules, and a clear property-and-entity filing structure. Its scope should extend beyond closing paperwork to trust documents, entity records, investment agreements, tax returns, and insurance policies.
The goal is continuity: a future trustee, manager, or family representative should be able to understand both the transaction and the authority behind it without reconstructing decisions from scattered correspondence.
Brickell condominium diligence should track applicable estoppel information, recorded association documents, assessments, required approvals, and liens. The office should also request and review the relevant association budget, inspection reports, and reserve studies with counsel before commitment, confirming which materials apply to the transaction and are available.
When considering Cipriani Residences Brickell, use those categories to frame transaction-specific questions, not assumptions about the project's documents or condition. Evaluate the relevant materials for the particular purchase.
As a recommended workflow, connect that diligence to the approval record. Identify which materials informed the decision, which questions remain open, and whether approval carries conditions. Diligence should inform the decision-maker, not simply complete the file.
Keep the distinctions clear: association-related approvals, internal family-office consent, and the buyer's signing authority are separate matters. None should substitute for another. A well-organized file allows counsel and the office to address each without blurring their respective purposes.
Payment controls should separate initiation, approval, fund release, account reconciliation, and vendor-record maintenance. A recommended dual-approval policy should cover acquisition deposits, closing wires, loan payoffs, large capital improvements, vendor changes, and related-party payments.
Small teams may not be able to assign every function to a different person. Compensating controls can include dual approvals, independent callback verification, monthly reconciliations, external review, and periodic audits. The purpose is meaningful oversight even when staffing is lean.
For an office considering Una Residences Brickell, these controls belong in both the acquisition plan and the subsequent ownership workflow. Vendor-record maintenance should remain separate from payment release, not be treated as a routine administrative detail.
Vendors should receive only the information and system access necessary for their work. Remove that access promptly when an engagement ends. Related-party leases, loans, service agreements, sales, and reimbursements should receive disclosure, independent review, and a separate conflict-approval process-even when everyone involved is familiar to the family.
The strongest handover is more than a collection of signed documents. It connects the approved transaction, confirmed signing authority, executed agreements, payment evidence, condominium diligence, and continuing access controls within the property's record.
For the family's Brickell residence, the governing principle is consistency without false uniformity. Apply a common operating discipline while confirming the legal requirements and documents relevant to each entity and transaction. That combination allows the residence to remain personal while its administration remains accountable.
For a discreet perspective on your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt should identify who approves acquisitions, sales, contracts, loans, capital calls, wires, vendor engagements, settlements, and exceptions. Thresholds should reflect the entity, transaction type, amount, risk, and urgency.
No. Internal purchase approval should be treated separately from authority to execute documents, which should be confirmed for the actual acquiring entity or trust.
Record the entity or trust, property, amount, counterparty, supporting documents, date, approver, and any conditions.
Legal and tax advisers should help establish the policy for the family's South Florida ownership records. It should address ownership, governance, and tax materials as well as closing documents.
A continuing ownership record should allow future trustees, managers, or family representatives to understand the transaction and the authority behind it. It should connect closing evidence with relevant governance and ongoing ownership documents.
Include trust documents, entity records, investment agreements, tax returns, insurance policies, and transaction evidence. Use role-based permissions, version control, search, and retention rules.
Review applicable estoppel information, recorded association documents, assessments, approvals, and liens. Request relevant budgets, inspection reports, and reserve studies, confirming applicability and availability with counsel before commitment.
A recommended policy should cover acquisition deposits, closing wires, loan payoffs, large capital improvements, vendor changes, and related-party payments.
Use compensating controls such as dual approvals, independent callback verification, monthly reconciliations, external review, and periodic audits when full separation of duties is impractical.
Limit vendor information and system access to what the work requires, and remove access promptly when the engagement ends. Related-party transactions should receive disclosure, independent review, and separate conflict approval.