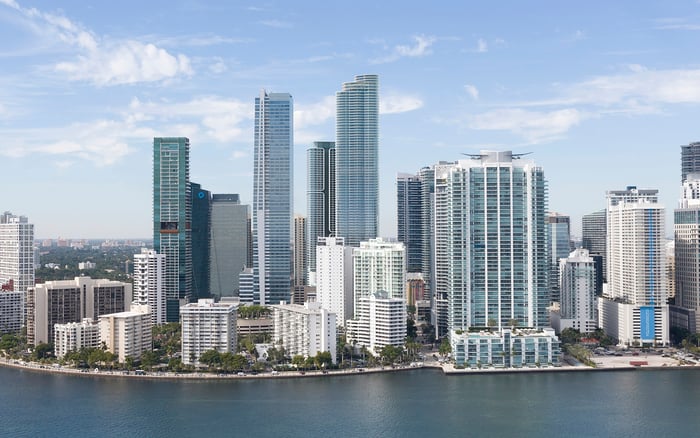
A Manhattan-to-Brickell purchase involves three distinct questions: domicile, New York statutory residency, and Florida homestead eligibility. A disciplined evidence file and a purchase-date-driven tax calendar help buyers separate lifestyle decisions from tax assumptions.
For a Manhattan buyer, a Brickell residence may begin as a seasonal retreat and gradually become the center of daily life. The legal transition, however, does not happen simply because the purchase closes. A person may maintain several residences but only one domicile: the permanent home to which they intend to return after an absence.
Whether the search centers on 2200 Brickell or another residence, the first decision is not architectural. It is whether Florida will remain a second-home destination or become the buyer’s permanent home. Ownership alone does not answer that question.
Three tests require separate attention: New York domicile, New York statutory residency, and Florida homestead eligibility. Evidence relevant to one may help explain another, but the tests are not interchangeable. A successful purchase and a defensible state exit are different accomplishments.
New York requires clear and convincing evidence that the former domicile was abandoned and a new permanent domicile established. The inquiry examines the overall pattern of life: residences, business ties, time spent in each location, significant personal possessions, and family connections.
A Florida declaration of domicile or voter registration can support the record, but neither alone proves abandonment of New York domicile. Administrative changes should document a genuine relocation, not substitute for one.
For a buyer considering Cipriani Residences Brickell, the central planning question is how the intended residence will function within the household. Where will ordinary life take place? What happens to the Manhattan home? Where will meaningful possessions and family connections be centered?
Create a domicile file recording actual changes in home use, business activity, family location, and personal belongings. Maintain a clear chronology of the transition, with supporting records where available. The objective is not the largest collection of Florida addresses, but a coherent account of where permanent life has moved.
This matters especially when the transition is gradual. The evidence should describe what actually happened, not compress a season of changing arrangements into a convenient closing date.
Establishing Florida domicile does not eliminate New York statutory-residency exposure. Maintaining a New York permanent place of abode for substantially all the year and spending more than 183 days in the state can trigger resident taxation.
An available Manhattan apartment can therefore remain consequential even after a genuine domicile change. Retaining it does not automatically defeat the move, but its availability and the owner’s New York presence require separate review.
New York generally counts any part of a day as a New York day. Arrival and departure dates matter; a calendar based only on overnight stays can misstate the count. Keep a contemporaneous travel calendar and supporting records rather than reconstructing the year from memory.
Staying below the statutory threshold is not proof that New York domicile has ended. The day-count test and the domicile inquiry address different issues. Review both with a qualified tax adviser before relying on the move’s anticipated tax treatment.
Florida homestead exemption requires an application. Eligibility generally depends on ownership and permanent residence on January 1, including qualifying permanent residence by a legal or natural dependent. A Brickell home used only for vacations or as a second home generally does not meet that requirement.
For a prospective purchase at The Residences at 1428 Brickell, separate the acquisition calendar from the intended occupancy calendar. Planning to make Florida home is not the same as meeting the ownership and permanent-residence conditions on the relevant January 1.
Purchasing after January 1 generally prevents buyers from qualifying for their own homestead exemption for that tax year, even if they move in before year-end. The next January 1 becomes the key eligibility checkpoint. The ordinary application deadline is March 1; confirm the applicable year’s filing arrangements locally.
The first $25,000 of homestead exemption applies to all property taxes, including school taxes. The additional exemption applies above $50,000 of assessed value and excludes school taxes. Confirm the applicable year’s additional amount rather than assuming a fixed total exemption.
A seller’s property-tax bill is a historical record, not a reliable projection of the buyer’s future carrying costs. It may reflect assessment benefits the purchaser will not retain.
Following a change of ownership, the seller’s Save Our Homes benefit generally ends, and the property is assessed at just value on the following January 1. Homestead exemption can qualify the property for Save Our Homes, which limits future annual increases in assessed value after the benefit is established. That protection does not promise that the seller’s assessment will continue.
When comparing a potential acquisition at Una Residences Brickell with other options, budget for taxes using an expected post-acquisition assessment. Keep that estimate distinct from both the current bill and any hoped-for exemption.
Portability is a separate consideration for buyers with a prior Florida homestead. It transfers an eligible Florida homestead assessment difference-not a New York property-tax benefit-with a maximum transferable benefit of $500,000.
The new homestead must be established within three years of January 1 of the year the old homestead was abandoned, not three years after its sale. Form DR-501T accompanies the homestead application. A Manhattan departure alone creates no portability benefit.
Maintain a separate property-tax file with ownership records, evidence of January 1 permanent residence, applications, exemption decisions, TRIM notices, and bills. Keeping it distinct from the domicile file makes the different tests easier to track.
For a purchase after January 1, organize the calendar around the next January 1 assessment and eligibility checkpoint, the ordinary March 1 homestead deadline, the August TRIM notice, and the November bill. Review purchase-year notices and bills as well, without assuming they reflect the following year’s position.
Miami-Dade mails TRIM notices by August 24. These show proposed property taxes; they are not tax bills. Review market and assessed values, exemptions, assessment benefits, proposed tax rates, and amounts proposed by each taxing authority. The notice estimates what the November bill is likely to contain, but the proposed amounts are not final.
If a value or exemption appears incorrect, contact the property appraiser and promptly review the Value Adjustment Board process. Use the applicable annual deadline rather than a date remembered from an earlier year.
The most orderly transition aligns three things: the home the household actually uses, the evidence supporting its domicile, and the assessment used in its ownership budget. Treat each as a distinct planning responsibility, supported by individualized legal and tax advice.
Explore your next Brickell residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. New York requires clear and convincing evidence that the former domicile was abandoned and a new permanent domicile established.
No. A declaration or voter registration alone does not prove abandonment of New York domicile; the overall pattern of life matters.
Yes. Maintaining a New York permanent place of abode for substantially all the year and spending more than 183 days in the state can trigger resident taxation, even after a domicile change.
Keep a contemporaneous travel calendar with supporting records. New York generally counts any part of a day, so arrival and departure dates matter.
Generally not. Florida homestead eligibility requires qualifying permanent residence, not merely ownership of a vacation or second home.
The buyer generally cannot qualify for their own homestead exemption for that tax year. The next January 1 becomes the key ownership and permanent-residence checkpoint.
The ordinary deadline is March 1. Confirm the applicable year’s filing arrangements with the local property appraiser.
It may reflect assessment benefits the buyer will not retain. After a change of ownership, the seller’s Save Our Homes benefit generally ends and assessment resets to just value on the following January 1.
No. Portability transfers an eligible prior Florida homestead assessment difference, up to $500,000, subject to timing and application requirements.
No. It shows proposed taxes and estimates the likely November bill; review values, exemptions, and assessment benefits promptly and check the applicable annual dispute deadline.