
For families moving from Riyadh to Las Olas, a considered purchase begins with clear decision-making authority, a traceable funding history, and realistic expectations about title privacy. These three disciplines should be planned together, before the residence is selected.
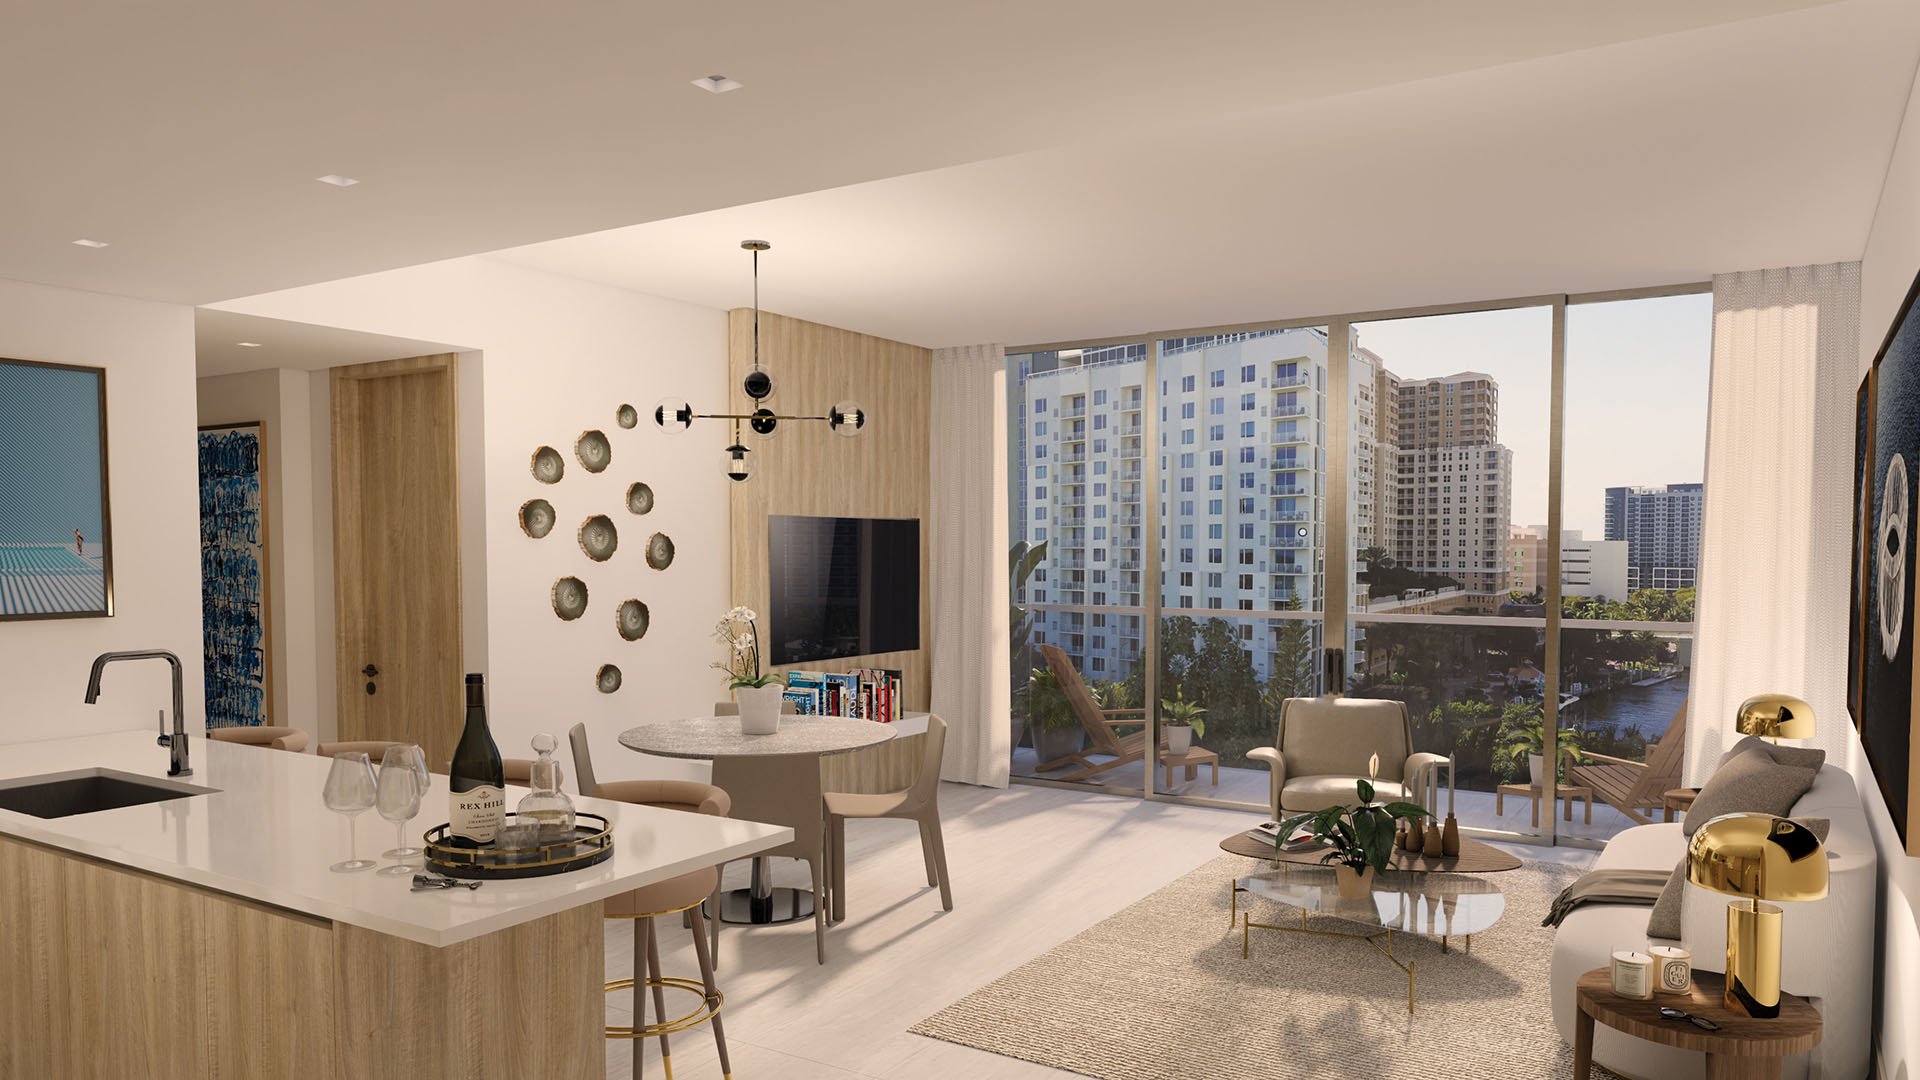
For a family leaving Riyadh and choosing Las Olas, the purchase calls for two parallel conversations. One concerns the residence and how it will serve the household. The other concerns who will own it, who may commit the family's capital, and how that capital will be documented. The second conversation should not wait for the first to conclude.
The meaningful distinction is not between Saudi and domestic buyers, but between a purchase with clearly documented authority and funding and one assembled under deadline pressure. A move from Riyadh should not, in itself, be treated as grounds for enhanced scrutiny or a special Las Olas documentation standard.
Whether the search centers on Sixth & Rio Fort Lauderdale or another residence, the family office should organize three connected workstreams: governance, source-of-funds evidence, and title privacy. Each answers a different question. Together, they help align the family's intentions with the transaction documents.
A family may agree on the purchase while leaving important questions of authority unresolved. Approval of the expenditure is not the same as authority to sign the contract, direct a trustee, or release a wire. A practical governance plan should distinguish these roles explicitly.
Before committing, consider a written authority schedule covering:
Who approves the purchase and its financial parameters.
Who signs transaction documents and in what capacity.
Who authorizes and executes the movement of funds.
Who controls the purchasing entity and holds distribution rights.
Who may approve later refinancing or changes to title.
This is a planning recommendation, not a statutory checklist. Its purpose is to make the family's decision-making clear to its advisers and the parties reviewing the purchase.
The supporting file should explain ownership and control, relevant family relationships and beneficiaries, board or shareholder decisions, and the rationale for the proposed ownership structure. Where responsibilities are divided, document that division rather than assuming a senior family member's involvement resolves every question of authority.
Source of wealth describes how the family accumulated its overall assets. Source of funds identifies the origin of the specific money used for this transaction. A persuasive account of a successful family business does not, by itself, explain the purchase money held in a particular account.
The distinction matters even when the available balance comfortably exceeds the purchase price. Evidence of accumulated savings can include statements showing how the balance developed, rather than merely a snapshot of the final amount. Other funding sources may call for inheritance records, business-sale documents, or tax returns.
For a family considering Four Seasons Hotel & Private Residences Fort Lauderdale, the administrative principle is the same as for any other contemplated purchase: build the explanation around the actual funding source, not the prestige of the address or the family's broader financial standing.
A useful preparation exercise is to write two short narratives. The first explains the family's wealth history. The second traces the intended purchase money from its origin to the account that will fund the transaction. Supporting documents should substantiate each narrative without conflating the two.
Money moved between accounts may require a more complete documentary trail than money held continuously in one account. Reviewers may request statements tracing those transfers rather than accepting the receiving account's balance alone.
The aim is continuity: what generated the money, where it was received, and how it reached the proposed funding account. A family office can prepare an account-by-account chronology and organize the corresponding evidence before documents are requested.
Different origins suggest different supporting materials. Gift-funded purchases may require the donor's identity, a gift letter, bank statements, and evidence of the donor's source of funds. Property-sale proceeds can be supported by a closing statement or a solicitor's confirmation of net proceeds, together with evidence tracing the money afterward.
These examples illustrate possible reviewer practices, not a uniform Florida checklist. Do not assume a particular statement period or certification format will satisfy every participant. Ask the relevant reviewers what they need for the transaction, and identify gaps before setting the funding timetable.
Privacy begins with a specific question: whose name should appear on the public title record? That is different from asking who must be identified to banks, advisers, or compliance reviewers.
A Florida land trust holds real estate in the trustee's name and can keep the beneficiary's name off the public title record. The beneficiary's interest is documented in a private trust agreement that generally does not need to be recorded. An LLC can instead place the entity's name, rather than the individual buyer's name, on title.
Neither approach guarantees anonymity. Deed-level privacy does not justify withholding information from parties entitled to review ownership, control, or funding. The family should be prepared to explain the structure while keeping its public-facing privacy objective appropriately narrow.
For a Broward purchase, have counsel evaluate the proposed title arrangement against the family's governance and documentation needs. Do not choose a structure solely because it keeps an individual's name off the deed.
If the search expands to St. Regis® Residences Bahia Mar Fort Lauderdale, apply the same ownership questions to the new candidate. These are family-level planning disciplines, not statements about any project's purchasing requirements.
Before signing, compare the proposed buyer, documented decision-makers, funding narrative, and intended title holder. Where different people or entities are involved, the file should clearly explain their relationships and authority. The objective is consistency, not unnecessary complexity.
The plan should extend beyond closing. Document who controls the entity, who holds distribution rights, and who may approve refinancing or a later title change. A residence intended to support family life should not leave future decisions dependent on unspoken understandings.
For Las Olas buyers, discretion is best served by precision: clear authority within the family, traceable capital for the transaction, and realistic expectations about what title privacy accomplishes. Coordinate the details with qualified legal, tax, and transaction advisers before committing.
Explore your South Florida residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA move from Riyadh should not itself be treated as establishing a special documentation standard or automatic enhanced scrutiny. Confirm the requirements applicable to the actual transaction with its reviewers.
Source of wealth explains how the family accumulated its overall assets. Source of funds explains the origin of the specific money used for the purchase.
A final balance may not explain how the savings developed. Reviewers may request bank statements showing the accumulation of the money.
Reviewers may request statements tracing the transfers. An account-by-account chronology can help organize the evidence connecting the original funds to the intended funding account.
Reviewers may request the donor's identity, a gift letter, bank statements, and evidence of the donor's source of funds. The precise request depends on the transaction review.
A closing statement or solicitor's confirmation of net proceeds can support the origin of the money. Evidence may also be needed to trace its movement afterward.
A Florida land trust holds title in the trustee's name and can keep the beneficiary's name off the public title record. The beneficiary's interest is documented in a private agreement that generally does not need to be recorded.
No, an LLC can place the entity's name rather than the individual's name on title, but deed-level privacy does not guarantee anonymity. It is not a basis for withholding information from parties entitled to review ownership, control, or funding.
It should distinguish purchase approval, signing and wire authority, entity control, distribution rights, and authority for later refinancing or title changes. This is a planning recommendation, not a statutory checklist.
Yes, document who controls the entity, holds distribution rights, and may approve refinancing or later title changes. Clear responsibilities help avoid reliance on unspoken family understandings.