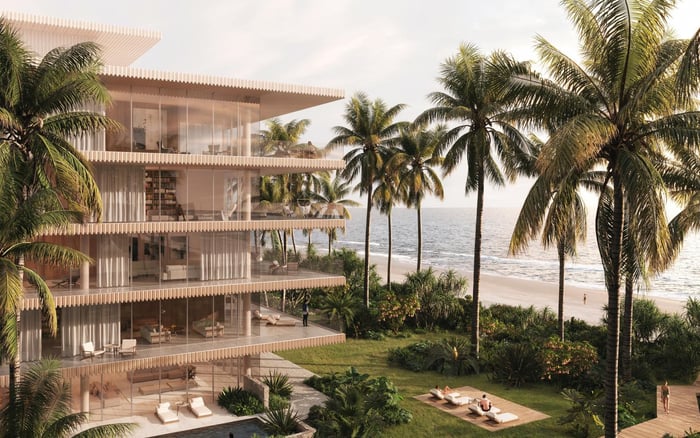
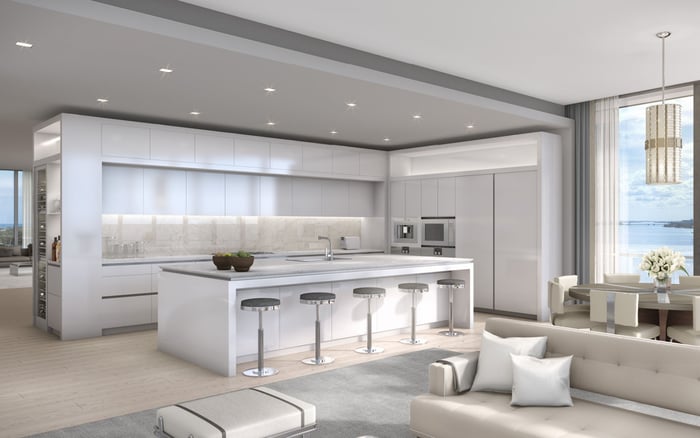
For buyers relocating from Copenhagen to South Flagler Drive, a residence is the foundation of a new life, not an automatic tax-residency solution. A credible Florida domicile position connects genuine household relocation, consistent documents, corroborated travel records, and separate advice on Danish departure obligations.
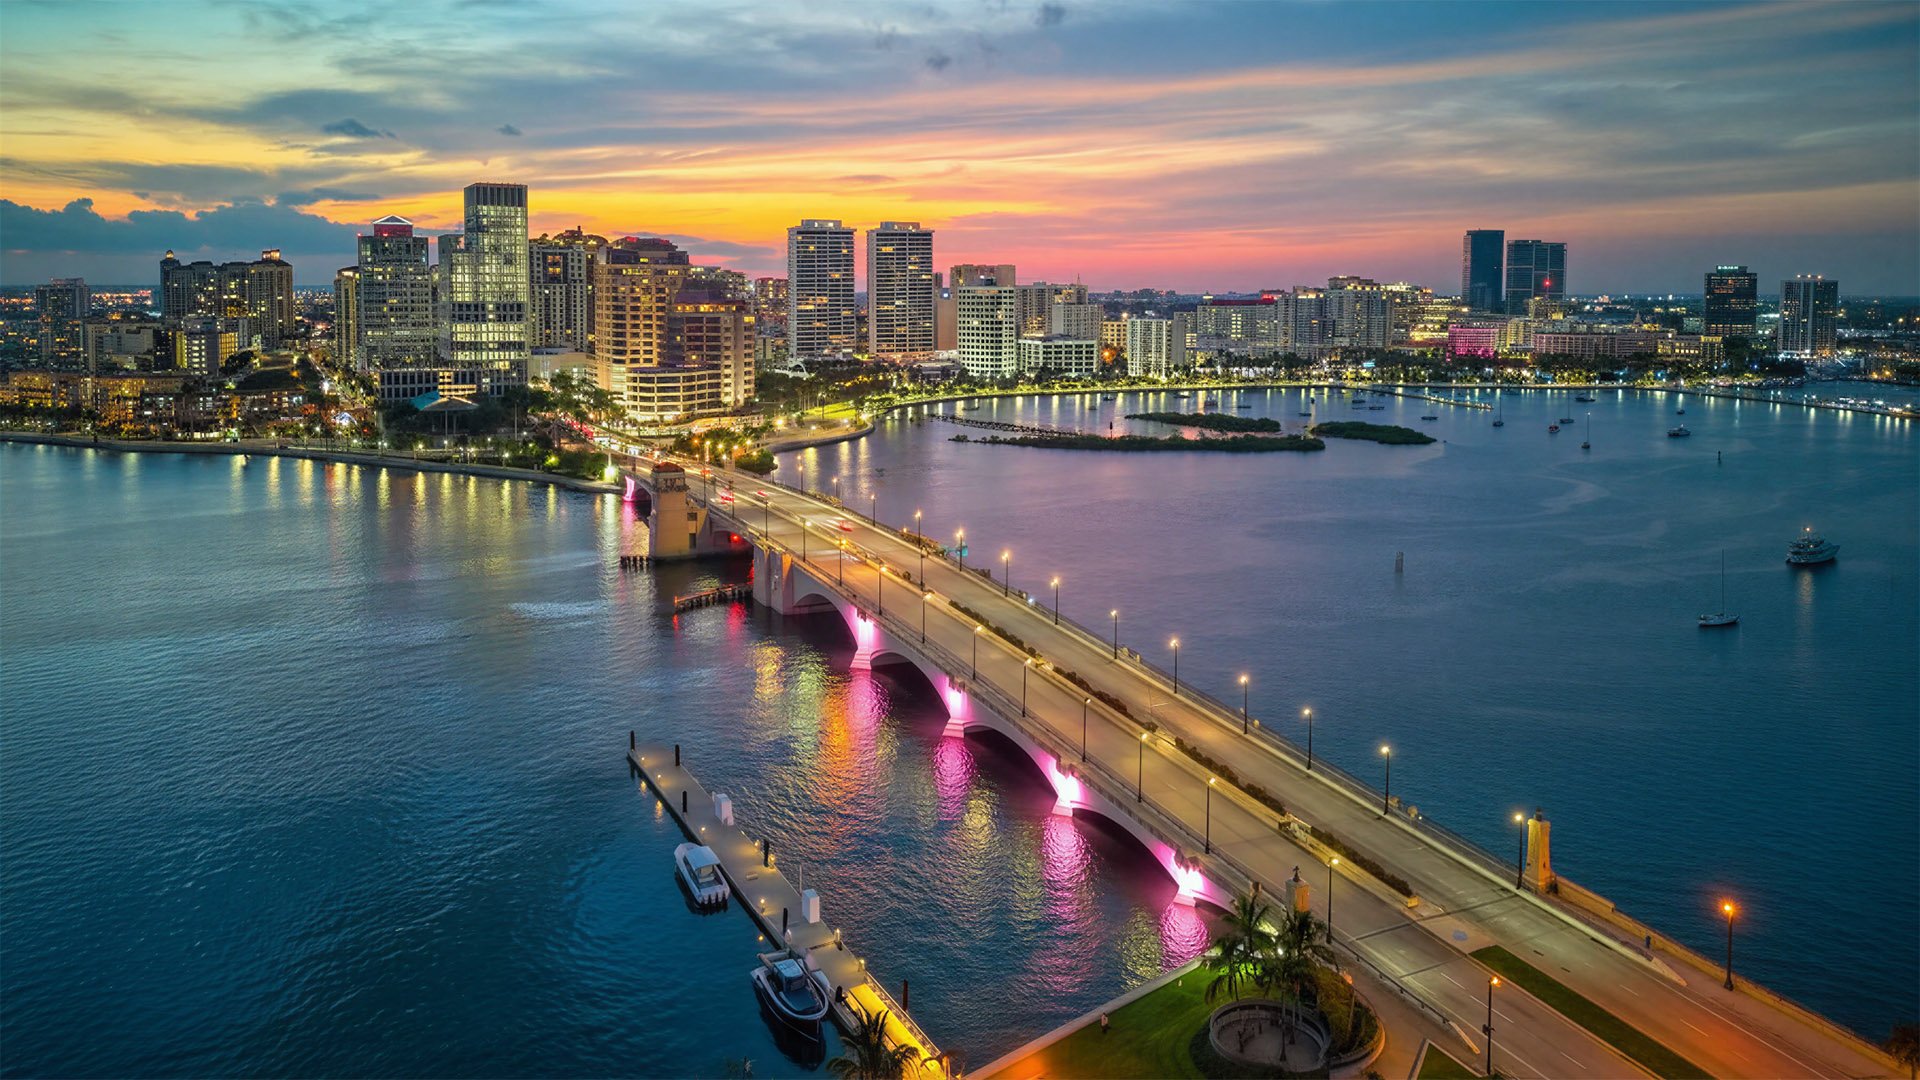
For a buyer leaving Copenhagen, a South Flagler Drive residence can mark a decisive change in daily life. Yet acquiring a beautiful home and establishing Florida domicile are distinct steps-ones to address before the purchase timetable becomes the relocation timetable. The residence supports evidence of a genuine move; the transaction does not settle every residency question.
When considering Forté on Flagler West Palm Beach, the planning question is not simply whether the home suits the household. It is whether the household intends to make Florida its principal and permanent home-and whether its conduct will demonstrate that intention.
The strongest approach coordinates three separate matters: Florida domicile, physical-presence evidence, and obligations in the jurisdiction being left. For a Copenhagen departure, Danish advice belongs alongside Florida planning, not after it.
Florida has no personal state income tax. There is therefore no Florida income-tax “183-day rule” that a buyer must satisfy to establish domicile, nor a general six-month waiting period. Domicile rests on making Florida the genuine principal and permanent home, supported by intention and objective ties.
Travel days still matter, but 183 Florida days is not a universal safe harbor. Have Danish counsel determine residence-termination requirements, any departure-tax exposure, applicable thresholds, and treaty treatment. Florida domicile also does not establish U.S. immigration status or determine federal tax treatment; those questions require separate analysis.
A closing statement establishes an acquisition. A lease documents a housing arrangement. Neither, standing alone, proves that the household has made Florida its permanent home. A more useful file connects those records to actual move-in, household relocation, and continuing use as the principal residence.
For buyers comparing broader West Palm Beach options such as Mr. C Residences West Palm Beach, the same distinction applies. Evaluate the home against the intended daily routine rather than expecting the address or purchase price to substantiate the domicile position.
Keep acquisition and occupancy dates distinct in the relocation timeline. If they differ, document the sequence accurately. The objective is not to place every event on one convenient date, but to preserve a truthful account of how the move unfolded. No single document conclusively proves domicile; the overall pattern of household life matters.
A Declaration of Domicile is a sworn statement filed with the county clerk where the Florida home is located. It can form part of the evidence, alongside a Florida driver's license, Florida vehicle registrations, and-only where legally eligible-Florida voter registration.
For a home genuinely used as the principal residence, consistent address records across federal tax returns, banking, insurance, and estate documents help document the relocation. Review these records with the appropriate advisers so that changes reflect the facts, not merely a desire for uniform paperwork.
The Florida homestead property-tax exemption requires permanent-residence status as of January 1. Where applicable, its documentation can support the principal-home position, but the exemption does not replace the wider domicile record. It should not be confused with automatic creditor protection.
Conflicting addresses and competing principal-residence claims warrant particular attention. A Florida filing is less persuasive when other records continue to describe another property as the household's main home without a coherent explanation.
The personal details of relocation can be as important as formal filings: where family members live, where children attend school, where valuable possessions are kept, and where medical care and community activities take place. Together, these details help show whether the Florida home is the center of ordinary life.
The practical question is whether they support the same account. If the residence is described as permanent while the family's established routine remains elsewhere, additional Florida paperwork does not erase that tension.
Keeping the former main home and substantial family or social ties in the old jurisdiction can weaken the claim that Florida has become the permanent home. That does not justify assuming a particular Danish tax outcome. It does warrant discussing retained Copenhagen connections explicitly with counsel and recording what changed, what remained, and when. Documentation should describe real choices, not manufacture appearances.
A detailed calendar is useful; one supported by independent records is stronger than recollection alone. Maintain a travel log and preserve boarding passes, credit-card statements, and phone records that can corroborate physical presence. Record travel as it happens rather than reconstructing an entire year when questions arise.
Ask advisers to specify the counting rules in each relevant jurisdiction, including how travel days should be treated. A single household calendar can organize the underlying facts without assuming that every jurisdiction interprets them identically.
The record should make departures, returns, and inconsistencies easy to examine. If a calendar entry and a supporting document appear to differ, review the discrepancy while the details remain accessible. The purpose is an accurate chronology, not merely a favorable total. Have counsel set retention periods based on the applicable jurisdictions rather than adopting a universal audit window or storage rule.
Whether the search centers on South Flagler Drive or includes Shorecrest Flagler Drive West Palm Beach, the central decision remains the same: is this another residence, or the household's permanent home? The documentary plan should follow the answer.
Organize the residency file around a dated timeline connecting acquisition or lease, actual move-in, domicile filings, identification changes, homestead documentation where applicable, travel evidence, and changes to former-jurisdiction ties. Keep supporting records accessible so that an adviser can follow the sequence without relying on memory.
Audit-ready does not mean audit-proof. It means the household can explain its position through consistent records and evidence of an actual relocation. For a Copenhagen buyer, that discipline keeps the property decision focused on living well while qualified advisers address the separate legal and tax questions.
For a discreet conversation about choosing a residence that fits your relocation plans, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The purchase supports a relocation, but domicile requires making Florida the genuine principal and permanent home, supported by intent and objective ties.
Florida has no personal state income tax and no Florida income-tax 183-day domicile rule. Physical presence can still matter under another jurisdiction's rules.
There is no general six-month waiting period. The position depends on the actual relocation, intention, and supporting evidence rather than waiting a fixed period.
Do not treat Florida domicile as resolving Danish tax residence. Danish counsel should assess residence termination, any departure-tax exposure, applicable thresholds, and treaty treatment.
It is a sworn statement filed with the county clerk where the Florida home is located. It is supporting evidence, not conclusive proof by itself.
Review federal tax returns, banking, insurance, and estate documents for addresses consistent with the actual relocation. Conflicting addresses or competing principal-residence claims can weaken the position.
Boarding passes, credit-card statements, and phone records can corroborate a detailed travel log. Ask advisers which counting rules apply in each relevant jurisdiction.
It requires permanent-residence status as of January 1 and can support evidence that the Florida property is the principal home. It does not replace the broader domicile record or establish automatic creditor protection.
Keeping the former main home and substantial family or social ties elsewhere can weaken the claim that Florida is the permanent home. The Danish consequences require separate advice.
No. U.S. immigration status and federal tax treatment are separate questions that should be assessed independently of Florida domicile.