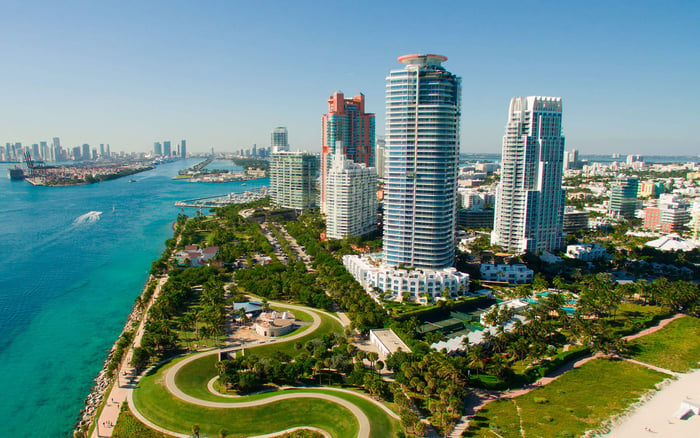
Selling a professional practice can open the door to a South Florida home, but the purchase should follow a clear view of after-tax proceeds, payment timing, and homestead eligibility. A disciplined transition-year plan keeps the residence aligned with the wealth available to support it.
Selling a professional practice can make a South Florida home feel like the natural next chapter. The more important question is not what the practice sold for, but how much of that value is available for a residence without compromising the years ahead. A signed sale agreement, cash received, and spendable wealth are three distinct measures.
Build the purchase budget from proceeds remaining after estimated taxes, debt repayment, transaction costs, and contingent obligations. Keep a separate reserve for the transition itself. The objective is a home that feels effortless after the closing celebration, not merely affordable on the day the practice changes hands.
For a buyer considering Una Residences Brickell, the address should follow that calculation. Establish the capital available for housing first; then decide how much belongs in the purchase and how much should remain accessible.
A professional-practice asset sale can produce both capital gain and ordinary income. Treating the entire purchase price as capital gain can distort the home budget before the property search begins.
Allocation matters. Goodwill, other intangibles, equipment, receivables, and other assets can carry different tax consequences for the seller. Buyers and sellers generally must report the purchase-price allocation for a qualifying business-asset sale on Form 8594. The allocation is more than a closing-document detail; it belongs in the household’s liquidity planning.
Ask the tax adviser to translate the proposed allocation into an estimated after-tax outcome before making a binding home commitment. If the allocation remains under negotiation, consider a conservative spending ceiling until it is settled. A purchase should not depend on the most favorable unresolved interpretation of the practice transaction.
An installment sale involves receiving at least one payment after the tax year in which the sale occurs. Eligible gain can generally be recognized as payments arrive rather than entirely in the closing year. That may change the timing of taxable income, but it does not make future payments available to spend today.
Nor does installment reporting defer every component of a business sale. Inventory and certain receivables follow separate rules, while interest received under an installment arrangement is treated separately from gain on the property sold. A useful planning document is a year-by-year schedule of expected cash receipts, estimated taxable amounts, and reserves.
A buyer comparing homes in Coconut Grove, including Four Seasons Residences Coconut Grove, should place anticipated housing commitments alongside that schedule. Test whether the purchase remains comfortable if a future receipt arrives later than expected. Do not assume that a tax deferral and a cash receipt occur together.
Before selecting a residence, ask the advisory team to compare immediate gain recognition, eligible installment reporting, and delayed contingent-payment scenarios. These are planning comparisons, not interchangeable tax treatments. The agreement and the character of the assets determine which treatments are available.
For each scenario, distinguish cash already received from fixed future payments and amounts dependent on future events. Then test the proposed home purchase against the most conservative workable case. A residence funded by money already available presents a different decision from one dependent on an uncertain later payment.
A seller can generally elect out of installment reporting, but revoking that election generally requires approval. Resolve that decision with tax counsel rather than treating it as a choice that can be casually reversed after the home contract is signed. Compare the consequences before committing capital, and obtain a separately verified tax-payment calendar for the actual transaction.
The acquisition price is only one part of the household decision. Separate the money assigned to the purchase from reserves for taxes, insurance, association obligations where applicable, maintenance, and personal spending. Obtain property-specific figures rather than carrying over assumptions from a previous home.
For a search in Fort Lauderdale that includes Andare Residences Fort Lauderdale, request the relevant ownership documents and current cost information before setting the final budget. The same discipline applies whether the buyer intends to finance the purchase or pay cash.
If financing is part of the plan, obtain transaction-specific guidance on how the lender will evaluate the post-sale financial picture. Do not assume that prior practice earnings, sale proceeds, or installment receipts will be treated identically. Preserve flexibility until the financing approach and the funds needed at closing are clear.
Florida’s homestead exemption reduces the assessed value subject to property tax for an eligible permanent residence. The exemption itself does not transfer when an owner moves; a new application is generally required for the new residence. Distinguish a permanent-residence plan from a second-home plan before assuming any benefit.
Save Our Homes portability is separate. It can transfer all or part of an existing assessment benefit to another qualifying Florida homestead. The portable assessment difference reflects the gap between the former homestead’s market value and assessed value, subject to eligibility requirements and a cap.
The maximum assessment difference eligible for portability is $500,000. That is not a $500,000 reduction in the tax bill, and the maximum should not be assumed for every move.
For a West Palm Beach search that includes Alba West Palm Beach, put eligibility and timing on the acquisition checklist. In Palm Beach County, the new homestead must be established on or before January 1 of the third year after abandoning the previous homestead to qualify for portability. Confirm how that rule applies to the household’s dates before relying on a projected benefit.
Waterfront living may be the reward for years spent building a practice, but financial flexibility belongs in the brief alongside setting and design. Decide which lifestyle priorities justify committing capital and which can wait until the transition-year picture is settled.
Before signing, bring the sale agreement, allocation, receipt schedule, tax estimates, home budget, and homestead questions into one coordinated review. The strongest purchase is not necessarily the largest residence the sale could support. It is the one that remains comfortable when income timing changes and the next chapter becomes everyday life.
Explore a South Florida home search shaped around your next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUse proceeds remaining after estimated taxes, debt repayment, transaction costs, and contingent obligations rather than the headline price. Keep transition and ownership reserves separate from purchase capital.
Not necessarily. A practice asset sale can produce both capital gain and ordinary income, depending on the assets and purchase-price allocation.
Allocations among goodwill, other intangibles, equipment, receivables, and other assets affect the seller’s tax treatment. Buyers and sellers generally must report the allocation for a qualifying business-asset sale on Form 8594.
An installment sale involves receiving at least one payment after the tax year in which the sale occurs. Eligible gain can generally be recognized as payments are received.
No. Inventory and certain receivables follow separate rules, and interest received is treated separately from gain on the property sold.
A seller can generally elect out, but revoking that election generally requires approval. Review the consequences with a tax adviser before committing the proceeds to a home.
Model a delayed-payment scenario and distinguish contingent amounts from cash already received. Consider whether the home remains comfortable without relying on uncertain future receipts.
The exemption itself does not transfer; a new application is generally required. Save Our Homes portability is a separate benefit with its own eligibility requirements.
No. The $500,000 maximum applies to the assessment difference eligible for portability, not to the tax bill, and the actual benefit depends on eligibility.
The new homestead must be established on or before January 1 of the third year after abandoning the previous homestead to qualify for portability. Confirm eligibility against the household’s specific dates.