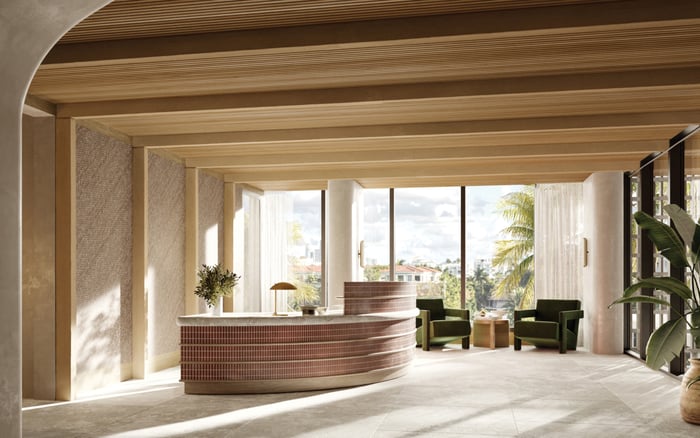
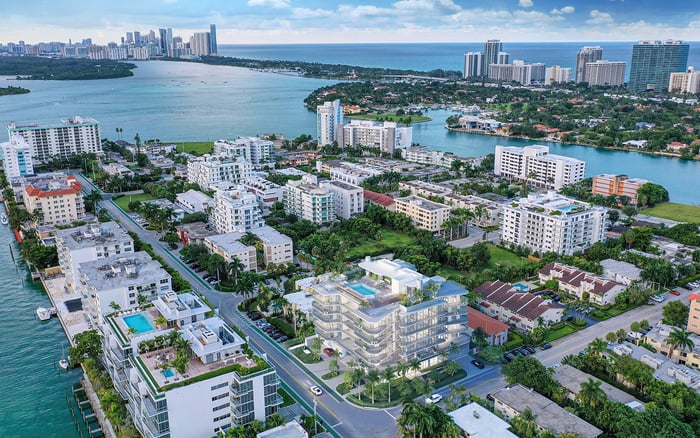
For Sydney buyers considering Bay Harbor Islands, a second-home purchase and a change of domicile are distinct decisions. A disciplined travel calendar, consistent records, and coordinated Australia-U.S. advice help keep the property’s actual use aligned with residency planning.
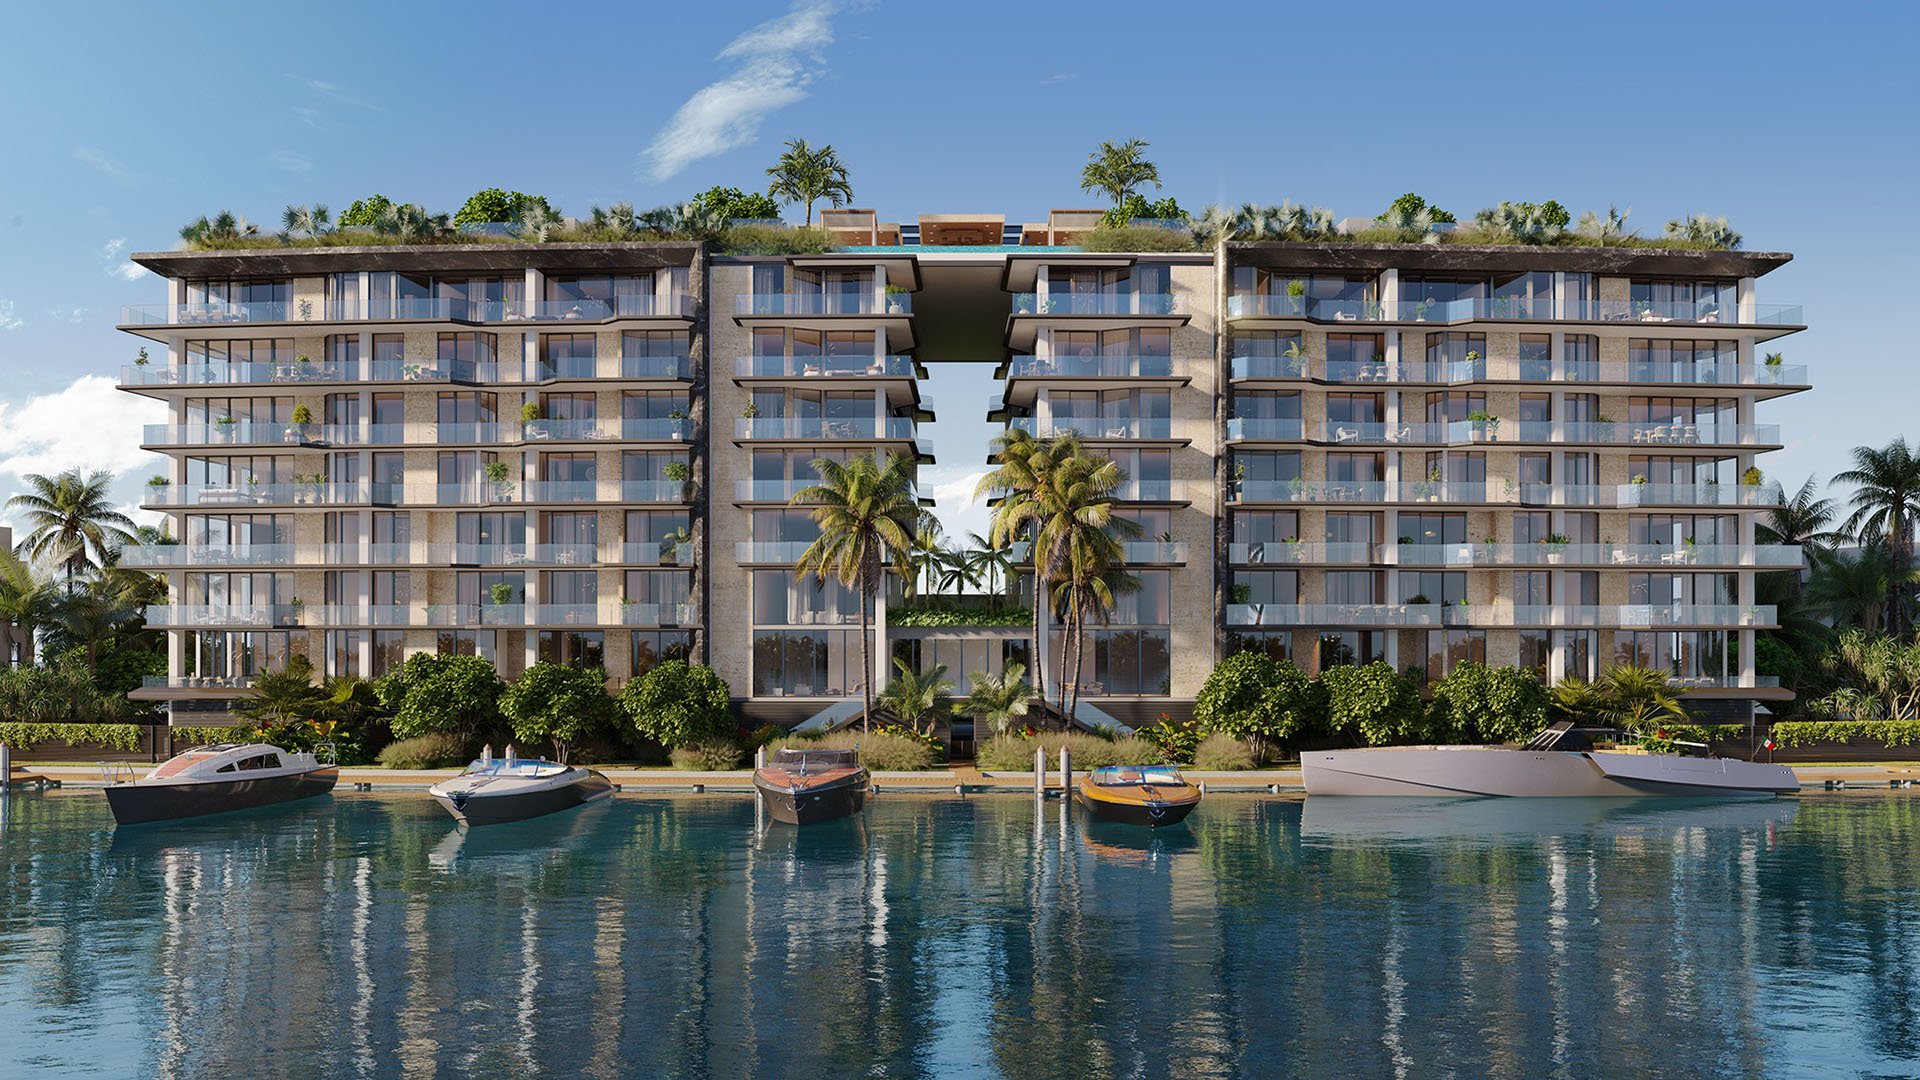
For a Sydney household considering Bay Harbor Islands, the first distinction is not architectural. It is whether the residence will serve as a seasonal retreat or become the intended permanent home. Both are legitimate choices, but they call for different planning. A purchase establishes ownership; it does not, by itself, establish Florida domicile.
That distinction belongs at the start of a property search. When considering Alana Bay Harbor Islands, for example, ask how the residence would fit into the household’s actual life. Would it remain a place for selected visits, or would meaningful possessions and everyday routines move there?
The address, travel history, and administrative records should tell the same truthful story. Changing paperwork cannot turn a seasonal home into a permanent one. Nor should a buyer feel compelled to describe an enjoyable second home as anything more than it is.
Florida domicile centers on a true, fixed, permanent home and principal establishment. There is no general six-month or 183-day minimum for establishing it, and time spent in Florida is not the sole test. A calendar matters, but it cannot substitute for the underlying facts.
Florida imposes no individual state income tax. That does not automatically end another state’s ability to tax someone as a resident. Domicile and statutory residency are separate concepts: a genuine Florida domicile can coexist with exposure to resident taxation elsewhere.
For a Sydney buyer, this calls for distinct questions rather than a single presumed answer: What is the intended permanent home? Which U.S. states have relevant connections? What Australia-U.S. issues require specialist analysis? Australian tax residency, U.S. federal substantial presence, and treaty treatment need coordinated advice. A Florida property purchase does not resolve those questions.
New York is a useful example for a Bay Harbor Islands buyer who retains a dwelling there or spends meaningful time in the state. Its rules are not universal rules for someone arriving from Sydney. If New York remains a person’s domicile, the state generally treats that person as a resident, subject to specified exceptions.
A separate statutory-residency test can apply to someone domiciled elsewhere. Generally, maintaining a permanent place of abode in New York for substantially all the tax year and spending 184 days or more in the state can create statutory residency.
The counting rules matter: New York generally counts any part of a day, subject to limited exceptions. Days need not be spent at the retained dwelling to count. Calling a property a vacation home does not settle whether it is a permanent place of abode; its characteristics and use matter.
Staying below the statutory day threshold does not, by itself, establish that New York is no longer the person’s domicile. Buyers with these connections should review both tests, not simply work toward a day-count target.
A useful travel calendar records where each person was, not merely where the household slept. Overnight-only tracking can miss partial days relevant to New York residency. For a household moving between Sydney, Florida, and other destinations, the daily record should be detailed enough for advisers to apply the relevant rules.
Record each day’s locations, arrival and departure details, partial-day movements, supporting evidence, and unresolved discrepancies. Reconcile each person’s record separately. Shared accommodation or a joint itinerary should not replace individual records when travel diverges.
Preserve contemporaneous calendars alongside supporting travel and transaction records. Review them regularly rather than reconstructing an entire year from memory. If an itinerary and a transaction appear inconsistent, flag the discrepancy for clarification instead of silently choosing the more convenient version.
Keep planned travel distinct from completed travel. An intended departure is not evidence that the journey occurred. The objective is a reliable account of presence, not a calendar arranged to support a preferred conclusion.
A Declaration of Domicile can support a Florida residency position, but it carries more weight when accompanied by actual relocation and consistent conduct. Qualifying for a homestead exemption or registering to vote in Florida can also provide evidence, subject to applicable eligibility requirements. None should be treated as an automatic entitlement or a standalone solution.
Review driver’s-license, vehicle-registration, banking, insurance, tax, and estate-planning records with the appropriate advisers. The purpose is to reflect a genuine change accurately, not to manufacture uniformity while daily life remains elsewhere. For an international household, check eligibility before making any administrative step part of the plan.
Meaningful personal possessions matter, too. Moving them to Florida can help demonstrate which residence functions as the permanent home. If The Well Bay Harbor Islands is under consideration, think beyond furnishing the apartment: which belongings would accompany a real relocation, and which would remain in Sydney?
The property decision should remain grounded in how the household wants to live. Evaluate a residence at Bay Harbor Towers against an honest personal brief, without assuming that ownership determines residency. Separate the appeal of the home from the legal significance of occupying it.
Write that brief before committing to a domicile narrative. Identify anticipated periods of use, possessions that would move, residences that would remain available elsewhere, and each person’s expected travel patterns. Treat those expectations as planning assumptions to revisit, not as completed facts.
If the home remains seasonal, describe it that way. If its role genuinely changes, review the records and advice then. Precision protects the distinction between a desirable purchase and a supported residency position.
Bring the property’s intended use, individual travel calendars, retained-home details, and existing records into one coordinated Australia-U.S. review. Where another U.S. state is relevant, include its domicile and statutory-residency questions rather than assuming Florida settles them.
This is a planning framework, not an individual residency determination. The strongest approach pairs consistent conduct with accurate records, while specialist advice addresses the cross-border questions separately.
For a considered approach to your Bay Harbor Islands property search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Ownership alone does not establish domicile; the property must genuinely function as the intended permanent home.
Florida has no general six-month or 183-day minimum for establishing domicile. Time spent there is not the sole test.
No. However, moving to Florida does not automatically end another state’s ability to tax you as a resident.
No. They are separate concepts, and establishing Florida domicile does not necessarily prevent residency taxation in another state.
For someone domiciled elsewhere, it can generally arise when the person maintains a permanent place of abode in New York for substantially all the tax year and spends 184 days or more there.
New York generally counts any part of a day spent in the state, subject to limited exceptions. The day need not be spent at the retained dwelling.
Not necessarily. Staying below the statutory threshold does not, by itself, resolve whether New York remains your domicile.
Record daily locations, partial-day movements, supporting travel or transaction evidence, and unresolved discrepancies. Reconcile each person’s travel separately.
It is stronger when supported by actual relocation and consistent conduct. Administrative records and meaningful personal possessions should reflect the genuine use of the home.
A Florida domicile position should not be treated as resolving those separate questions. Australian residency, U.S. federal substantial presence, and treaty treatment require coordinated Australia–U.S. advice.