For a Doha-based family buying a Bay Harbor Islands second home, a considered acquisition begins with clear signing authority, coordinated closing documents, and disciplined family-office controls.
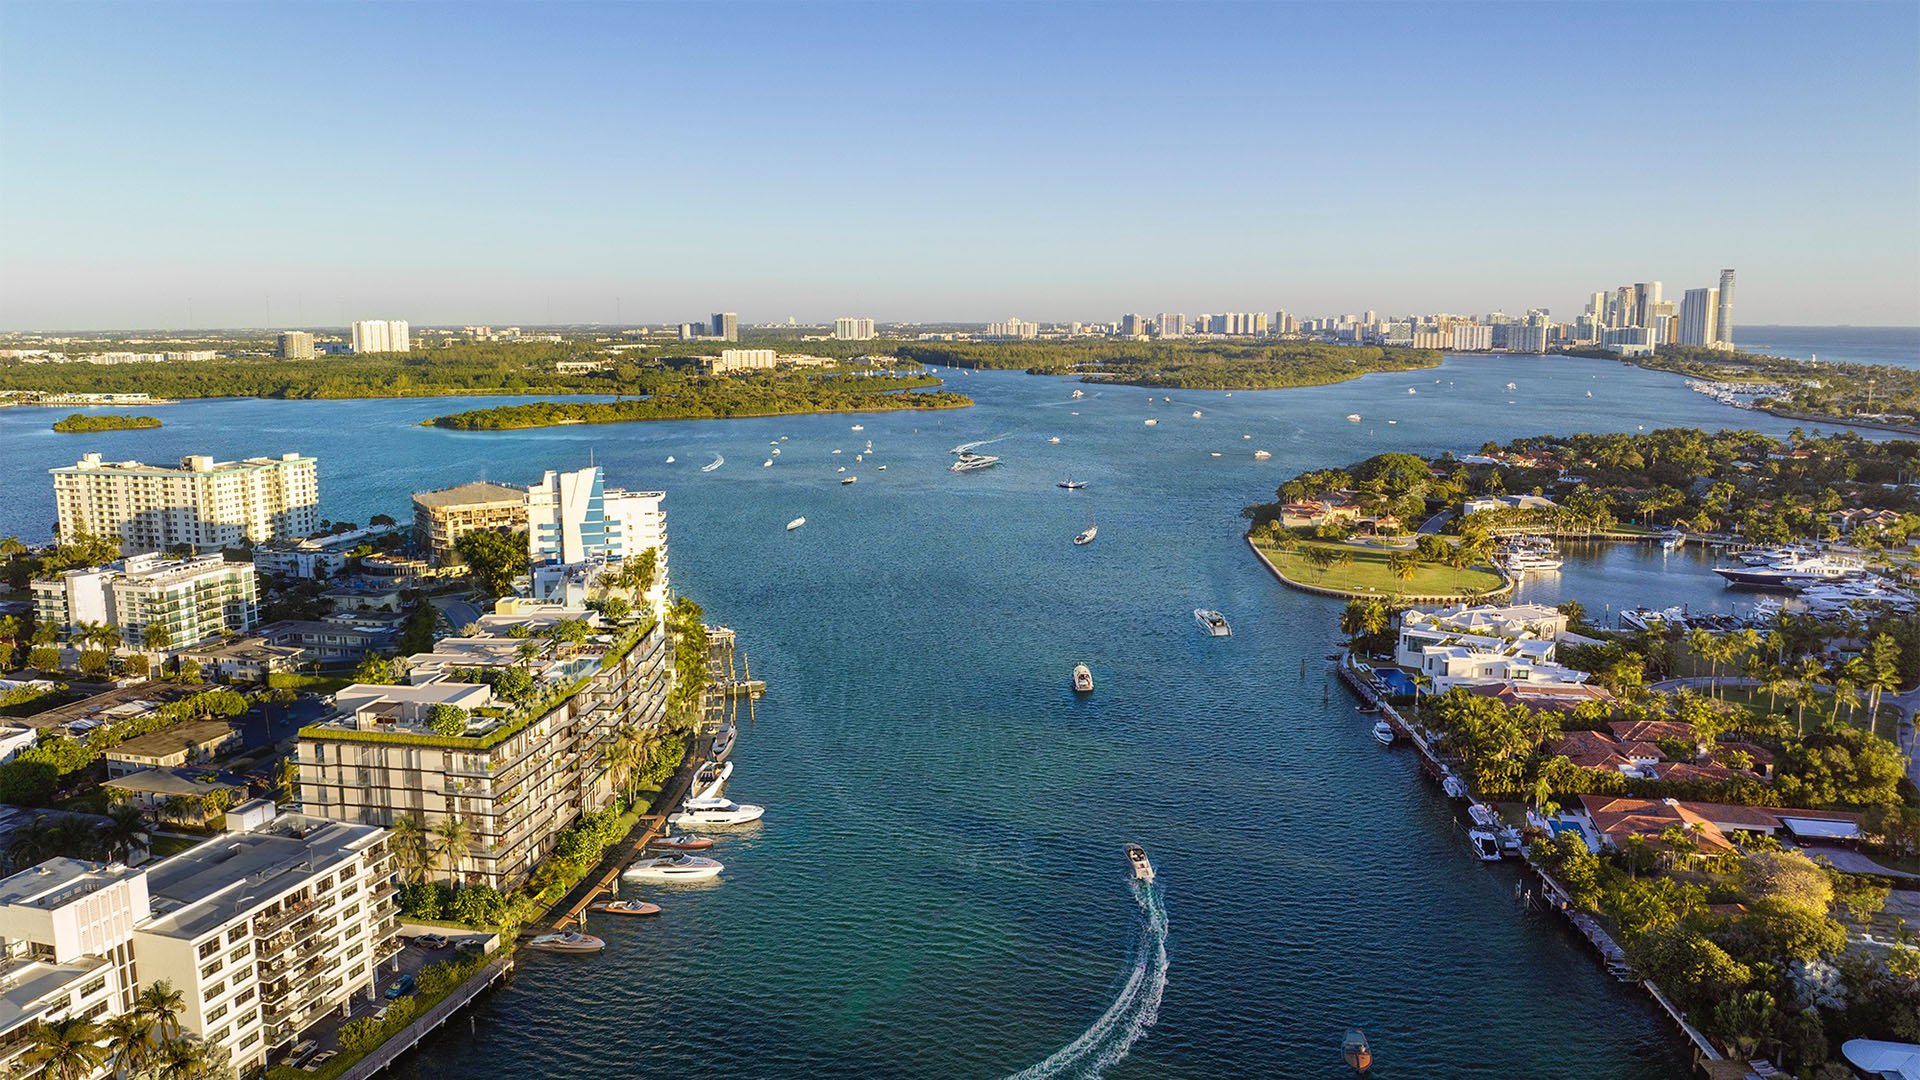
A Bay Harbor Islands second home should offer a change of pace, not a second administrative life. For a family based in Doha, the purchase deserves two parallel briefs: one defining the residence the family wants, the other establishing who may approve commitments, sign documents, release funds, and manage the home after closing.
Whether the search includes Bay Harbor Towers or another address, the operating brief should precede a binding commitment. If the search extends to Bal Harbour, maintain a separate property file rather than carrying building-specific assumptions from one location to another.
The central distinction is simple: family-office approval is not legal signing authority. Neither, by itself, establishes who should release a payment. Treat these as separate decisions, each with a named owner.
For an entity purchase, the closing team may need organizational records, resolutions, and evidence that the proposed representative can bind the purchaser. Gather those materials early so counsel and the title company can assess them before signatures become urgent.
As an internal policy, consider a concise approval matrix covering the purchase contract, deposits, financing, material amendments, closing funds, and post-closing expenditure. For each category, identify the decision-maker, authorized signer, payment approver, and alternate. Set monetary limits deliberately; do not assume a principal's broad approval extends to every subsequent instruction.
A useful acquisition memo should record the approved property, purchasing entity, budget, funding plan, and unresolved conditions. If Alana Bay Harbor Islands enters the shortlist, attach the documents for the specific transaction under consideration, not just the marketing material that prompted interest.
These are recommended governance practices, not prescribed Bay Harbor Islands approval rules. Their purpose is to make the family's intent clear to everyone responsible for carrying it out.
Remote closing may be possible, including through a power of attorney. Acceptance, however, depends on the title company, lender, document type, and applicable notarization requirements. Do not assume a document signed in Doha will be accepted merely because the family has used a similar instrument elsewhere.
Ask the closing team to confirm the proposed signing route before execution. Establish who will sign, in what capacity, which documents can follow that route, and what execution formalities and delivery arrangements apply. If a power of attorney is contemplated, have the proposed form reviewed before relying on it.
Identification requests also vary. A lender or title company may request a passport, relevant immigration documentation, and tax-identification information. Financial requests may include bank statements, proof of funds and reserves, income verification, and U.S. or foreign tax returns.
The objective is a closing calendar built around accepted documents, not a travel calendar built around an unconfirmed assumption about remote signing.
Document retention should answer three questions: what establishes ownership and authority, what explains the movement of money, and what supports future administration or disposition. Have counsel and tax advisers set the retention schedule rather than treating a single period as sufficient for every record.
A useful internal structure separates entity and authority records; contracts and amendments; identification and financial submissions; closing and tax documentation; and ongoing property administration. Keep executed versions distinct from drafts, with a clear index identifying the documents that governed the transaction.
For a prospective purchase at La Maré Bay Harbor Islands, the same discipline would keep the property's transaction file separate from the family's wider financial archive. Give each adviser access to the material needed for their role rather than circulating the entire archive.
As an elective policy, the office may consider retaining core ownership and authority records indefinitely, subject to professional advice. This is not a stated local retention requirement. Sensitive identification records warrant separate access and deletion decisions, while counsel should determine whether originals must be preserved.
FIRPTA turns on the seller's U.S. tax status, not simply on the buyer being foreign. A Doha-based purchaser can nevertheless have withholding responsibilities when acquiring property from a qualifying foreign seller. The closing team should verify the seller's status before disbursing funds.
The general withholding rate is 15% of the amount realized on a foreign person's disposition of U.S. real property, subject to exceptions and reduced-withholding procedures. A seller's nonforeign-status certification, an IRS withholding certificate, or a documented exception can affect whether withholding is required and its amount.
When withholding applies, funds generally must be withheld at closing and remitted to the IRS within 20 days afterward, subject to applicable withholding-certificate procedures. Assign responsibility for the determination, remittance, and supporting records before closing day.
Do not confuse FIRPTA's $300,000 residence exception with Florida homestead eligibility. The former has qualifying-use conditions; the second-home label alone neither establishes nor defeats it. Florida homestead benefits require permanent Florida residence and domicile, not ownership alone. A Doha-based family's budget should not assume those benefits.
After closing, the control problem shifts from acquisition to stewardship. As a family-office policy, distinguish permission to enter the residence, permission to order work, and permission to approve or pay an invoice. One appointment need not confer all three.
If The Well Bay Harbor Islands is under consideration, request the applicable property and association documents before designing vendor arrangements. Confirm the relevant access and work procedures rather than assuming another building's practices apply.
Consider written scopes, office-selected quote thresholds, documented change approvals, and independent payment review. Verify payment-detail changes through an established contact channel before releasing funds. These are proposed safeguards, not asserted municipal or association mandates.
As an internal practice, the vendor file should connect the approved scope to the invoice and evidence of completion. Establish a separate emergency authorization route so urgent work can proceed without making unlimited spending authority the default.
Before funds move, consolidate the open issues into one closing-readiness record: purchaser authority, accepted signing arrangements, requested identification and financial documents, seller tax-status treatment, and payment authorization. Record who has cleared each item and what remains conditional.
Then give the property administrator a deliberately narrower operating file: approved vendors, spending permissions, applicable property procedures, and escalation contacts. The residence can feel effortless to the family precisely because the responsibilities behind it are explicit.
For a discreet conversation about your South Florida second-home search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. An entity purchaser may need organizational records, resolutions, and other evidence that its representative can bind it, separate from the family's internal approval.
Remote closing may be possible, including through a power of attorney. Acceptance depends on the title company, lender, document type, and applicable notarization requirements.
No automatic acceptance should be assumed. Have the closing team review the proposed form and confirm the execution requirements before signing.
Requests may include a passport, relevant immigration documentation, tax-identification information, bank statements, proof of funds and reserves, income verification, and U.S. or foreign tax returns. Requirements vary by lender and title company.
Do not assume a single local period governs the entire file. Have counsel and tax advisers establish a document-specific retention schedule, including decisions about originals and sensitive identification records.
No. FIRPTA turns on the seller's U.S. tax status, although a foreign purchaser can have withholding responsibilities in a qualifying foreign-seller transaction.
The general rate is 15% of the amount realized, subject to exceptions and reduced-withholding procedures. Funds generally must be withheld at closing and remitted within 20 days afterward, subject to applicable withholding-certificate procedures.
No. The $300,000 residence exception has qualifying-use conditions, and the second-home label alone neither qualifies nor disqualifies the purchase.
No. Eligibility requires permanent Florida residence and domicile, rather than ownership alone, and is distinct from FIRPTA's residence-use exception.
They are presented here as elective family-office safeguards, not local mandates. Set internal thresholds deliberately and confirm applicable property and association procedures separately.