A private-client framework for distinguishing condominium reserve requirements from HOA and club obligations, reconciling capital funding with the approved budget, and addressing notices and assessments before closing.
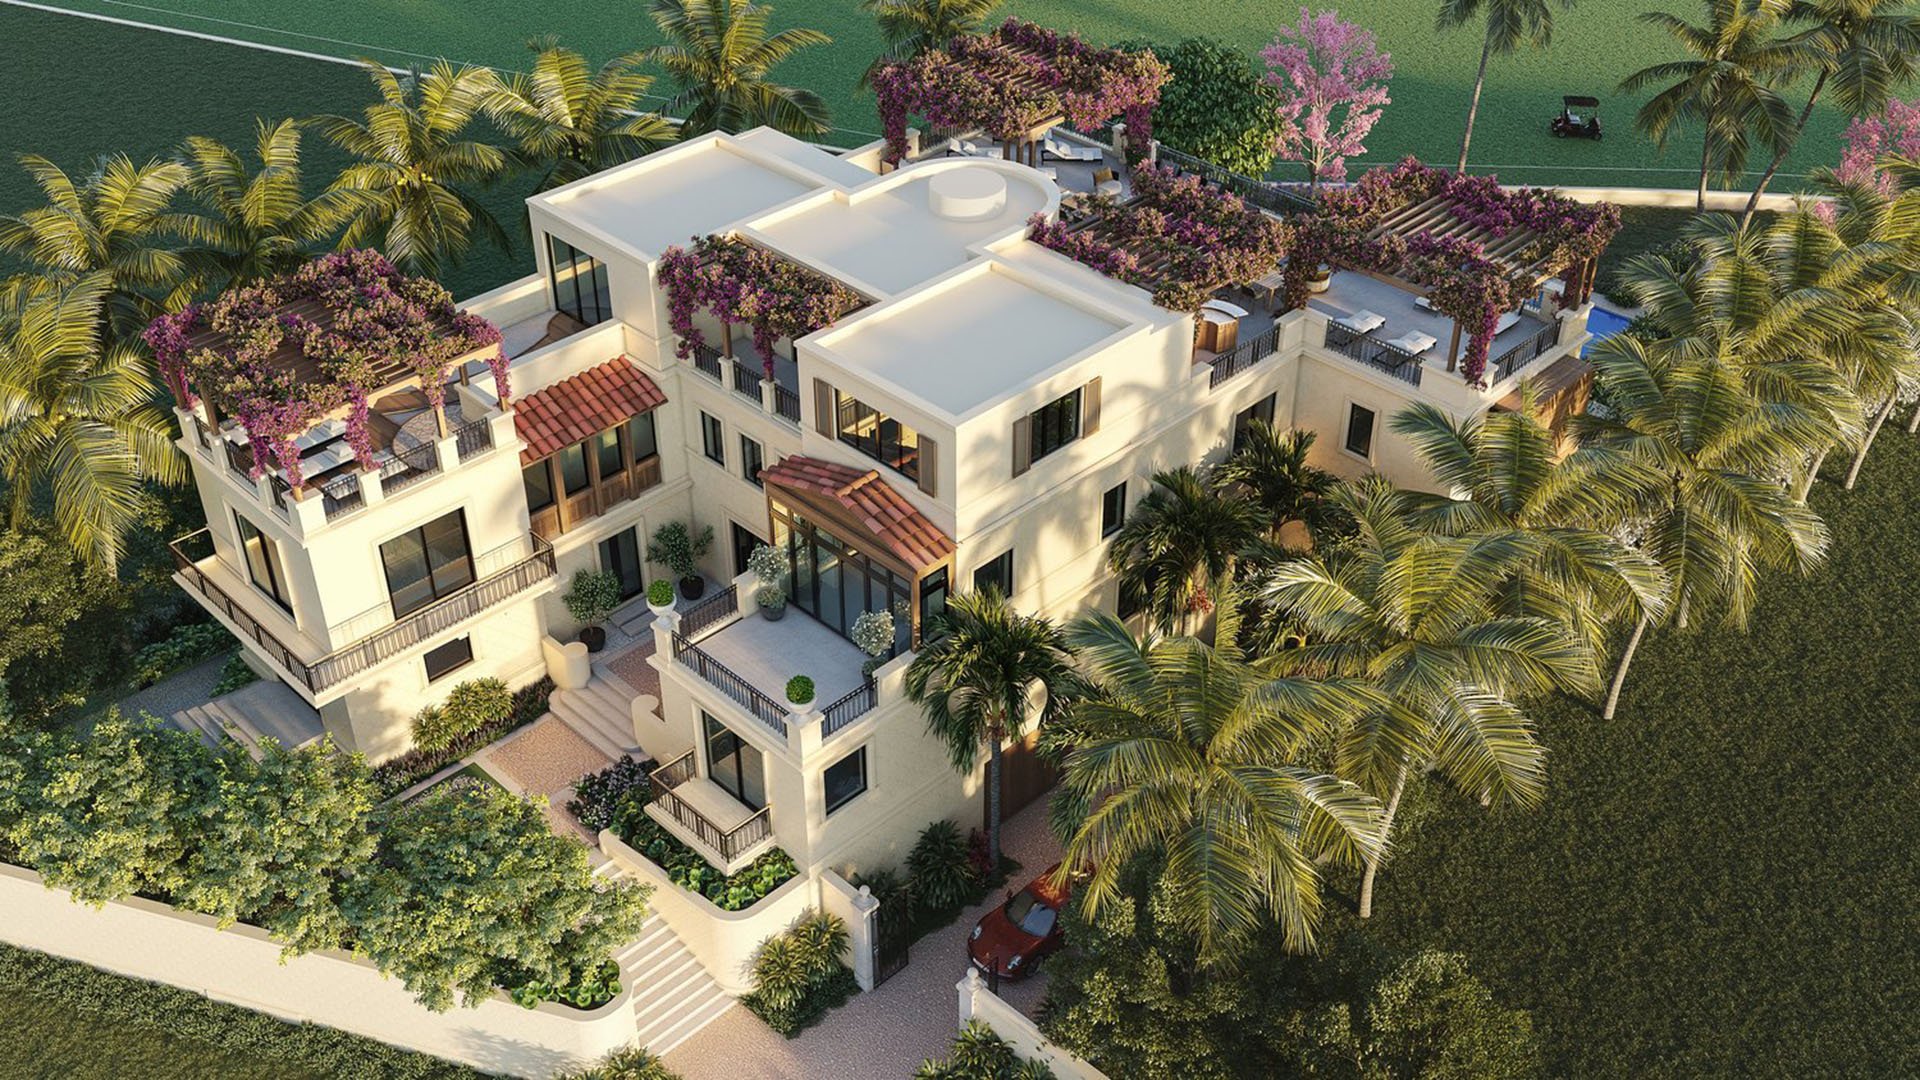
A residence in a private club community is both a lifestyle acquisition and a commitment to shared capital obligations. For a purchasing household, the financial question extends beyond annual dues: which entities can impose charges, what work must they fund, and does the current budget support that work?
The central distinction is straightforward. A reserve study, an approved budget, a financing arrangement, and an assessment notice serve different purposes. None substitutes for the others. Nor should a loan or special assessment be assumed to create a universal obligation to update a reserve study immediately or distribute it within a fixed period.
For a household considering The Links Estates at Fisher Island, the first diligence request should identify the legal and contractual obligations attached to the specific purchase. An address on Fisher Island does not, by itself, determine the applicable reserve regime.
Start with the residence’s ownership structure. Determine whether the acquisition involves a condominium, cooperative, or home governed by an HOA, then identify any separate master association or private club relationship. The governing documents should establish which obligations attach to ownership and which arise through membership.
Request each relevant entity’s approved budget, capital plan, assessment notices, and applicable membership documents. Do not assume an association’s reserve study captures a separate club’s capital obligations. Distinguish association contributions from club dues, membership payments, and any separately authorized capital charges.
When evaluating Shell Bay by Auberge Hallandale in Hallandale Beach, apply the same entity-by-entity review rather than drawing conclusions from its club-oriented presentation. This is a diligence framework, not a statement about the project’s reserves, assessments, or membership terms.
Florida residential condominium buildings with three or more habitable stories generally require a Structural Integrity Reserve Study, or SIRS, at least every 10 years. That requirement should not be extended automatically to every residence within a private club community.
For applicable unit-owner-controlled associations existing on or before July 1, 2022, the initial SIRS deadline was December 31, 2025, subject to a milestone-inspection coordination exception. Counsel should verify any claimed exception and the applicable completion date rather than accept a general assurance that the study can wait.
Milestone inspections are a separate obligation. Qualifying condominium and cooperative buildings generally require one at age 30 and every 10 years thereafter. A local enforcement agency may require the initial inspection at age 25 when local circumstances warrant it.
Request the applicable study and inspection documentation, their completion dates, and the association’s response to identified work. A reserve funding analysis and a building inspection answer different questions; receiving one does not resolve the other.
The acquisition question is not simply whether the reserve study carries a recent date. It is whether the study’s assumptions still align with the association’s approved financial plan after a financing decision, special assessment, or change in known project costs.
Ask management to explain how the latest study connects to the current budget and funding decisions. If circumstances have changed, request a written reconciliation and ask the reserve professional whether the study’s assumptions or funding recommendations need revision. This is a prudent review step, not a universal statutory update trigger.
The reconciliation should distinguish cash already available, assessment amounts approved, amounts collected, financing committed, and financing actually accessible for the work. It should also show where borrowing costs and repayment obligations appear in the budget. Assessment approval alone is not proof that all required cash is on hand.
The objective is a clear account of project costs, funding sources, payment timing, and continuing reserve contributions. Any unresolved difference should remain an acquisition issue until the household’s advisers can explain its consequences.
For condominium loans subject to Full Review reserve-study criteria, the analysis covers major common-area components requiring repair, maintenance, or replacement, including their condition and remaining useful lives. It also addresses projected costs, existing reserve balances, annual contributions, and a recommended funding plan.
Compare the recommended contributions with the approved budget. Contributions below the recommendation signal a potential funding gap that warrants explanation. Ask whether the comparison covers the same components and period, and whether later project decisions have been incorporated.
A household considering Turnberry Ocean Club Sunny Isles in Sunny Isles Beach should request the applicable documents for its transaction rather than rely on another purchaser’s financing outcome. This general review framework supports no conclusion about the project’s funding position.
Underwriting also requires attention to timing. A transition from a 10% to a 15% annual-budget minimum reserve requirement for Full Review is scheduled to begin in January 2027. Revised reserve-study standards also call for the budget to reflect the highest recommended reserve allocation when that route is used. Have the lender confirm the precise effective-date trigger and requirements applicable to the purchase. These figures are not universal reserve rules for every club-community home.
Florida’s HOA disclosure framework warns purchasers that they will be obligated to pay association assessments. For an HOA board meeting considering a special assessment, at least 14 days’ notice is generally required through the applicable delivery method and conspicuous posting on the property. The notice must state that assessments will be considered and identify their nature.
That rule concerns the assessment meeting. It does not establish an automatic reserve-study update after financing or a universal deadline for notifying owners of such an update. Condominium procedures and private-club contractual obligations require their own review.
Milestone-inspection notice is distinct: the local enforcement agency must provide written notice by certified mail to the association and owners of portions of the building. Keep each notice obligation tied to its event, recipient, and governing framework.
Before waiving relevant contingencies, reconcile the latest study, approved budget, known project costs, assessments, and available cash or financing. Request current notices and decisions, not merely the documents available when the residence was first marketed.
Counsel should address who bears any assessment, considering approval dates, payment dates, closing, and assessments approved between signing and closing. Do not assume that approval before closing or installments afterward settle the allocation. The purchase contract should address responsibility explicitly.
The final household briefing should set out ongoing obligations, known capital charges, unresolved funding questions, and matters requiring lender or legal confirmation. The goal is not to eliminate shared obligations, but to enter them with clarity.
For a discreet perspective on South Florida residential acquisitions, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida’s SIRS requirement generally applies to residential condominium buildings with three or more habitable stories, not every residence in a private club community.
Generally, at least every 10 years. Counsel should also verify the applicable initial deadline and any claimed coordination exception.
A financing event should not be treated as establishing a universal immediate-update requirement. Request a reconciliation of the study, budget, project costs, and financing, and confirm any applicable legal obligations.
No. The assessment should be reconciled with projected costs, available cash, and continuing reserve contributions to determine whether a funding gap remains.
Compare recommended reserve contributions with budgeted contributions, checking that they cover the same components and period. A lower budgeted contribution signals a potential funding gap requiring explanation.
Qualifying condominium and cooperative buildings generally require an inspection at age 30 and every 10 years afterward. Local circumstances may justify an initial inspection at age 25.
Generally, at least 14 days’ notice through the applicable delivery method and conspicuous property posting is required. The notice must state that assessments will be considered and identify their nature.
No. Buyers should identify each charging entity and request its applicable budget, capital plan, assessment notices, and membership documents.
The lender should confirm the precise effective-date trigger and whether the revised Full Review reserve requirements apply to the transaction. A previous purchaser’s approval is not a substitute for that confirmation.
That responsibility requires contract-specific legal review. Counsel should address approval dates, payment dates, closing, and assessments approved between signing and closing.