For an international buyer, a new condominium requires two distinct insurance reviews: the association’s building coverage and the owner’s protection for interiors and possessions. Understanding replacement cost, statutory exclusions and ordinance-and-law provisions is essential before closing.
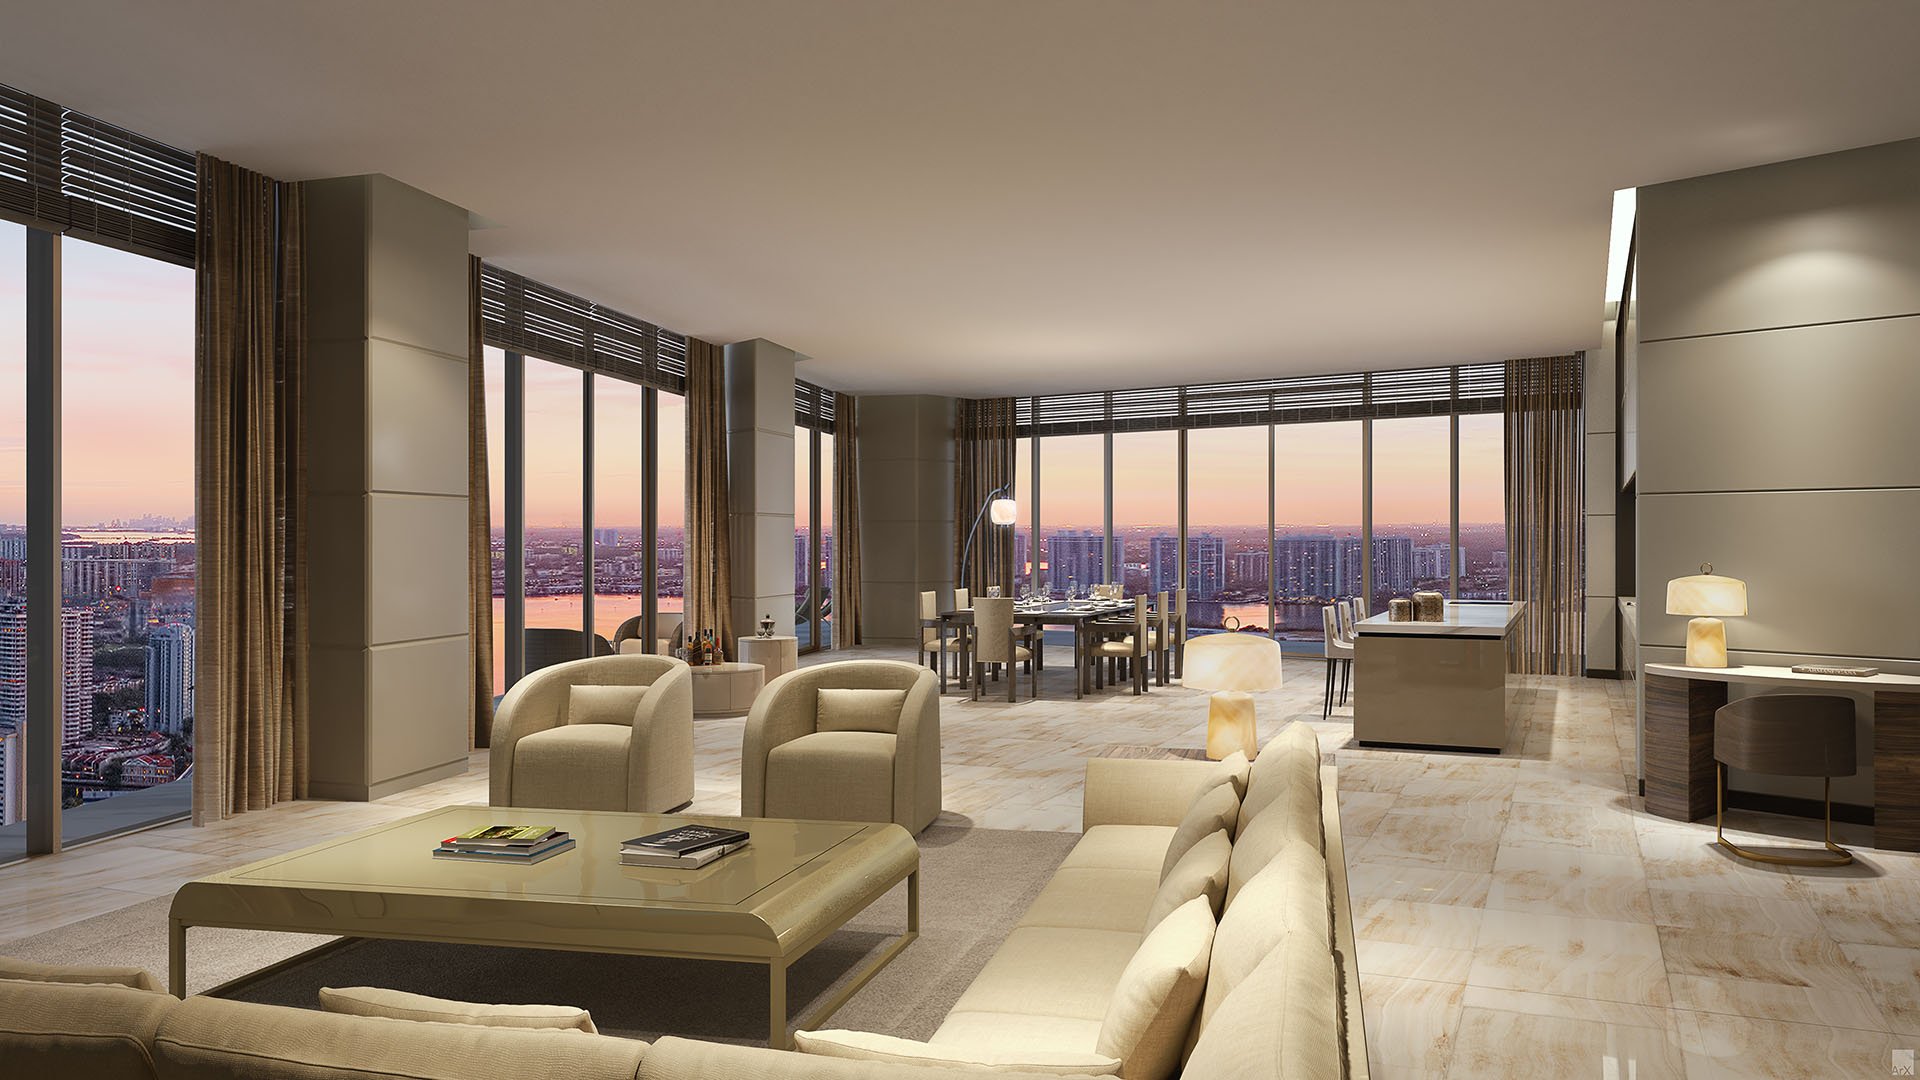
A new South Florida condominium can arrive with an elegantly resolved interior and still require a separate insurance strategy. For a foreign buyer, the central question is not simply whether the building is insured. It is whether the association’s policy and the owner’s policy together address the property that would need to be restored after a covered loss.
New construction does not erase the boundary between those policies. Florida condominium associations must maintain adequate property insurance, but their statutory obligation does not encompass everything within a residence. Master-policy adequacy therefore does not resolve the owner’s separate coverage needs.
For an international household, remote ownership and seasonal occupancy should shape the practical review: who holds the documents, who can coordinate locally, and whether the broker understands the intended use. Nationality is not the organizing principle of this coverage analysis. The allocation of property responsibilities and the policy wording are.
Before closing, request the association’s master policy, declarations, endorsements, deductibles and latest insurance appraisal. An insurance certificate alone cannot replace a review of the provisions that determine what is insured and how a claim would be adjusted.
Florida requires replacement cost to be determined at least once every three years through an independent insurance appraisal or an update of a previous appraisal. Ask when that valuation was completed, and have the broker explain how it relates to current policy limits.
The association’s appraisal and the owner’s interior replacement-cost estimate serve different purposes. The former supports insurance for association-insured property; the latter should address property allocated to the owner. Neither substitutes for the other.
A buyer considering The Residences at 1428 Brickell should undertake the same document review before treating the insurance file as complete. This is not a judgment about any particular building’s coverage. It is a disciplined approach to evaluating a Brickell acquisition through its actual documents.
The phrase “developer standard” can create misplaced reassurance. Under Florida’s statutory allocation, standard finishes are not automatically included in the association’s required property insurance simply because the developer installed them.
The listed exclusions include floor, wall and ceiling coverings; electrical fixtures; appliances; water heaters and filters; built-in cabinets and countertops; and window treatments located within and serving only one unit. Personal property inside the residence is also excluded from the association’s required coverage.
Insurance for these excluded items is the owner’s responsibility, typically addressed through an HO-6 condominium policy. The review should therefore begin with the entire owner-responsible interior, not just the upgrade package.
Ask the broker and legal adviser to organize the residence into four categories:
Association-insured property identified through Florida law and the master policy.
Owner-responsible standard finishes and equipment.
Upgrades and owner-installed improvements.
Personal property and furnishings.
Keep those categories distinct, even when a single purchase contract includes several of them. The purpose is to clarify the boundary before selecting limits.
For a Miami Beach purchase, including a residence under consideration at The Perigon Miami Beach, reconcile the developer’s finish schedule with upgrade invoices and an owner-specific replacement-cost estimate. This is a valuation exercise, not an assumption about that project’s insurance arrangements.
Ask a qualified adviser to estimate the cost of replacing the owner-responsible property specified for the residence. Separate cabinetry, countertops, surface finishes, fixtures and appliances from furniture and other possessions so each category can be matched to the appropriate coverage.
Owner-installed improvements deserve particular attention. The association is not obligated to fund reconstruction of improvements benefiting only one unit when they were not part of the developer’s standard improvements across the development. That rule does not reverse the statutory exclusions for standard flooring or cabinetry.
Avoid using a generic luxury-interior cost per square foot as the sole basis for limits. Retain specifications, invoices and photographs, and ask the broker to reconcile the estimate with the proposed policy. Revisit that comparison when the interior specification changes.
HO-6 policies generally provide building-property, personal-property, personal-liability and loss-of-use coverage, subject to their terms and limits. Review those categories separately rather than treating them as an interchangeable pool of protection.
Replacement-cost coverage does not mean unlimited reimbursement. Florida’s dwelling replacement-cost provision expressly contemplates settlement within policy limits. Even a sound valuation can leave the owner inadequately protected if the selected limit is too low or the loss falls outside the policy’s coverage.
Ask the broker to identify which provisions address attached interiors, which address possessions, and which deductibles and exclusions apply. Confirm the covered causes of loss rather than assuming every HO-6 contract responds identically.
For a buyer evaluating Bentley Residences Sunny Isles, the useful question is not whether an owner’s policy is available. It is whether the proposed contract matches the intended residence and its owner-responsible replacement costs.
Ordinance-and-law coverage helps pay additional rebuilding costs required to comply with current building codes. It warrants a separate review; do not presume it is included within a replacement-cost description.
Florida’s homeowners statute addresses options of 25% or 50% of the dwelling limit. Those figures should not be applied automatically to every HO-6 policy or condominium association master policy. Ask for the actual endorsement and a written explanation of the applicable limit under each contract.
The association review should address its insured property; the owner review should address the owner’s insured property. Ask how each policy would respond if covered reconstruction also required code-related work. New construction is not a reason to omit that question.
Request three practical illustrations from the broker: a partial interior loss, extensive water or fire reconstruction, and rebuilding involving code requirements. For each, ask which policy responds, what property it addresses, and which limits, exclusions and deductibles affect the outcome. These are hypothetical tests, not assurances that every water or fire event is covered.
For an owner living abroad, designate a local contact and keep the policy file, finish schedule and valuation records accessible to those expected to assist. Explain the planned occupancy pattern to the broker before binding coverage, and ask whether it affects the proposed terms.
The closing objective is clarity: a documented building valuation, a separate interior estimate, and policy provisions tested against both. This briefing is a due-diligence framework, not a substitute for advice on a specific contract from a licensed insurance professional and Florida counsel.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida’s required association coverage excludes specified interior items and personal property, so the owner needs a separate coverage review.
Replacement cost must be determined at least once every three years using an independent insurance appraisal or an update of a previous appraisal.
No. Statutory exclusions for items such as flooring, cabinetry and countertops remain relevant even when the developer supplied them as standard finishes.
It generally provides building-property, personal-property, personal-liability and loss-of-use coverage. The actual protection depends on the contract’s terms, limits and exclusions.
The association is not obligated to fund reconstruction of owner-installed improvements benefiting only one unit when they were not part of the developer’s standard improvements across the development.
Yes. Adequate association coverage does not eliminate exclusions for owner-responsible interiors and possessions or compensate for insufficient owner-policy limits.
No. Replacement-cost coverage remains subject to policy limits and other applicable terms.
It helps pay additional rebuilding costs required by current building codes. Verify its scope and limit separately under the association and owner policies.
No. Florida’s homeowners statute addresses those options, but they should not be assumed to apply automatically to every HO-6 or association master policy.
Obtain the complete master-policy documents and latest appraisal, then reconcile the finish schedule and upgrades with an owner-specific replacement estimate. Discuss occupancy with the broker and arrange accessible records and a local contact.