A West Palm Beach address is only the beginning of a Florida domicile strategy. For Malibu owners, the stronger position aligns an actively occupied primary home, a clear change in California ties, contemporaneous travel records, and consistent departure-year tax filings.
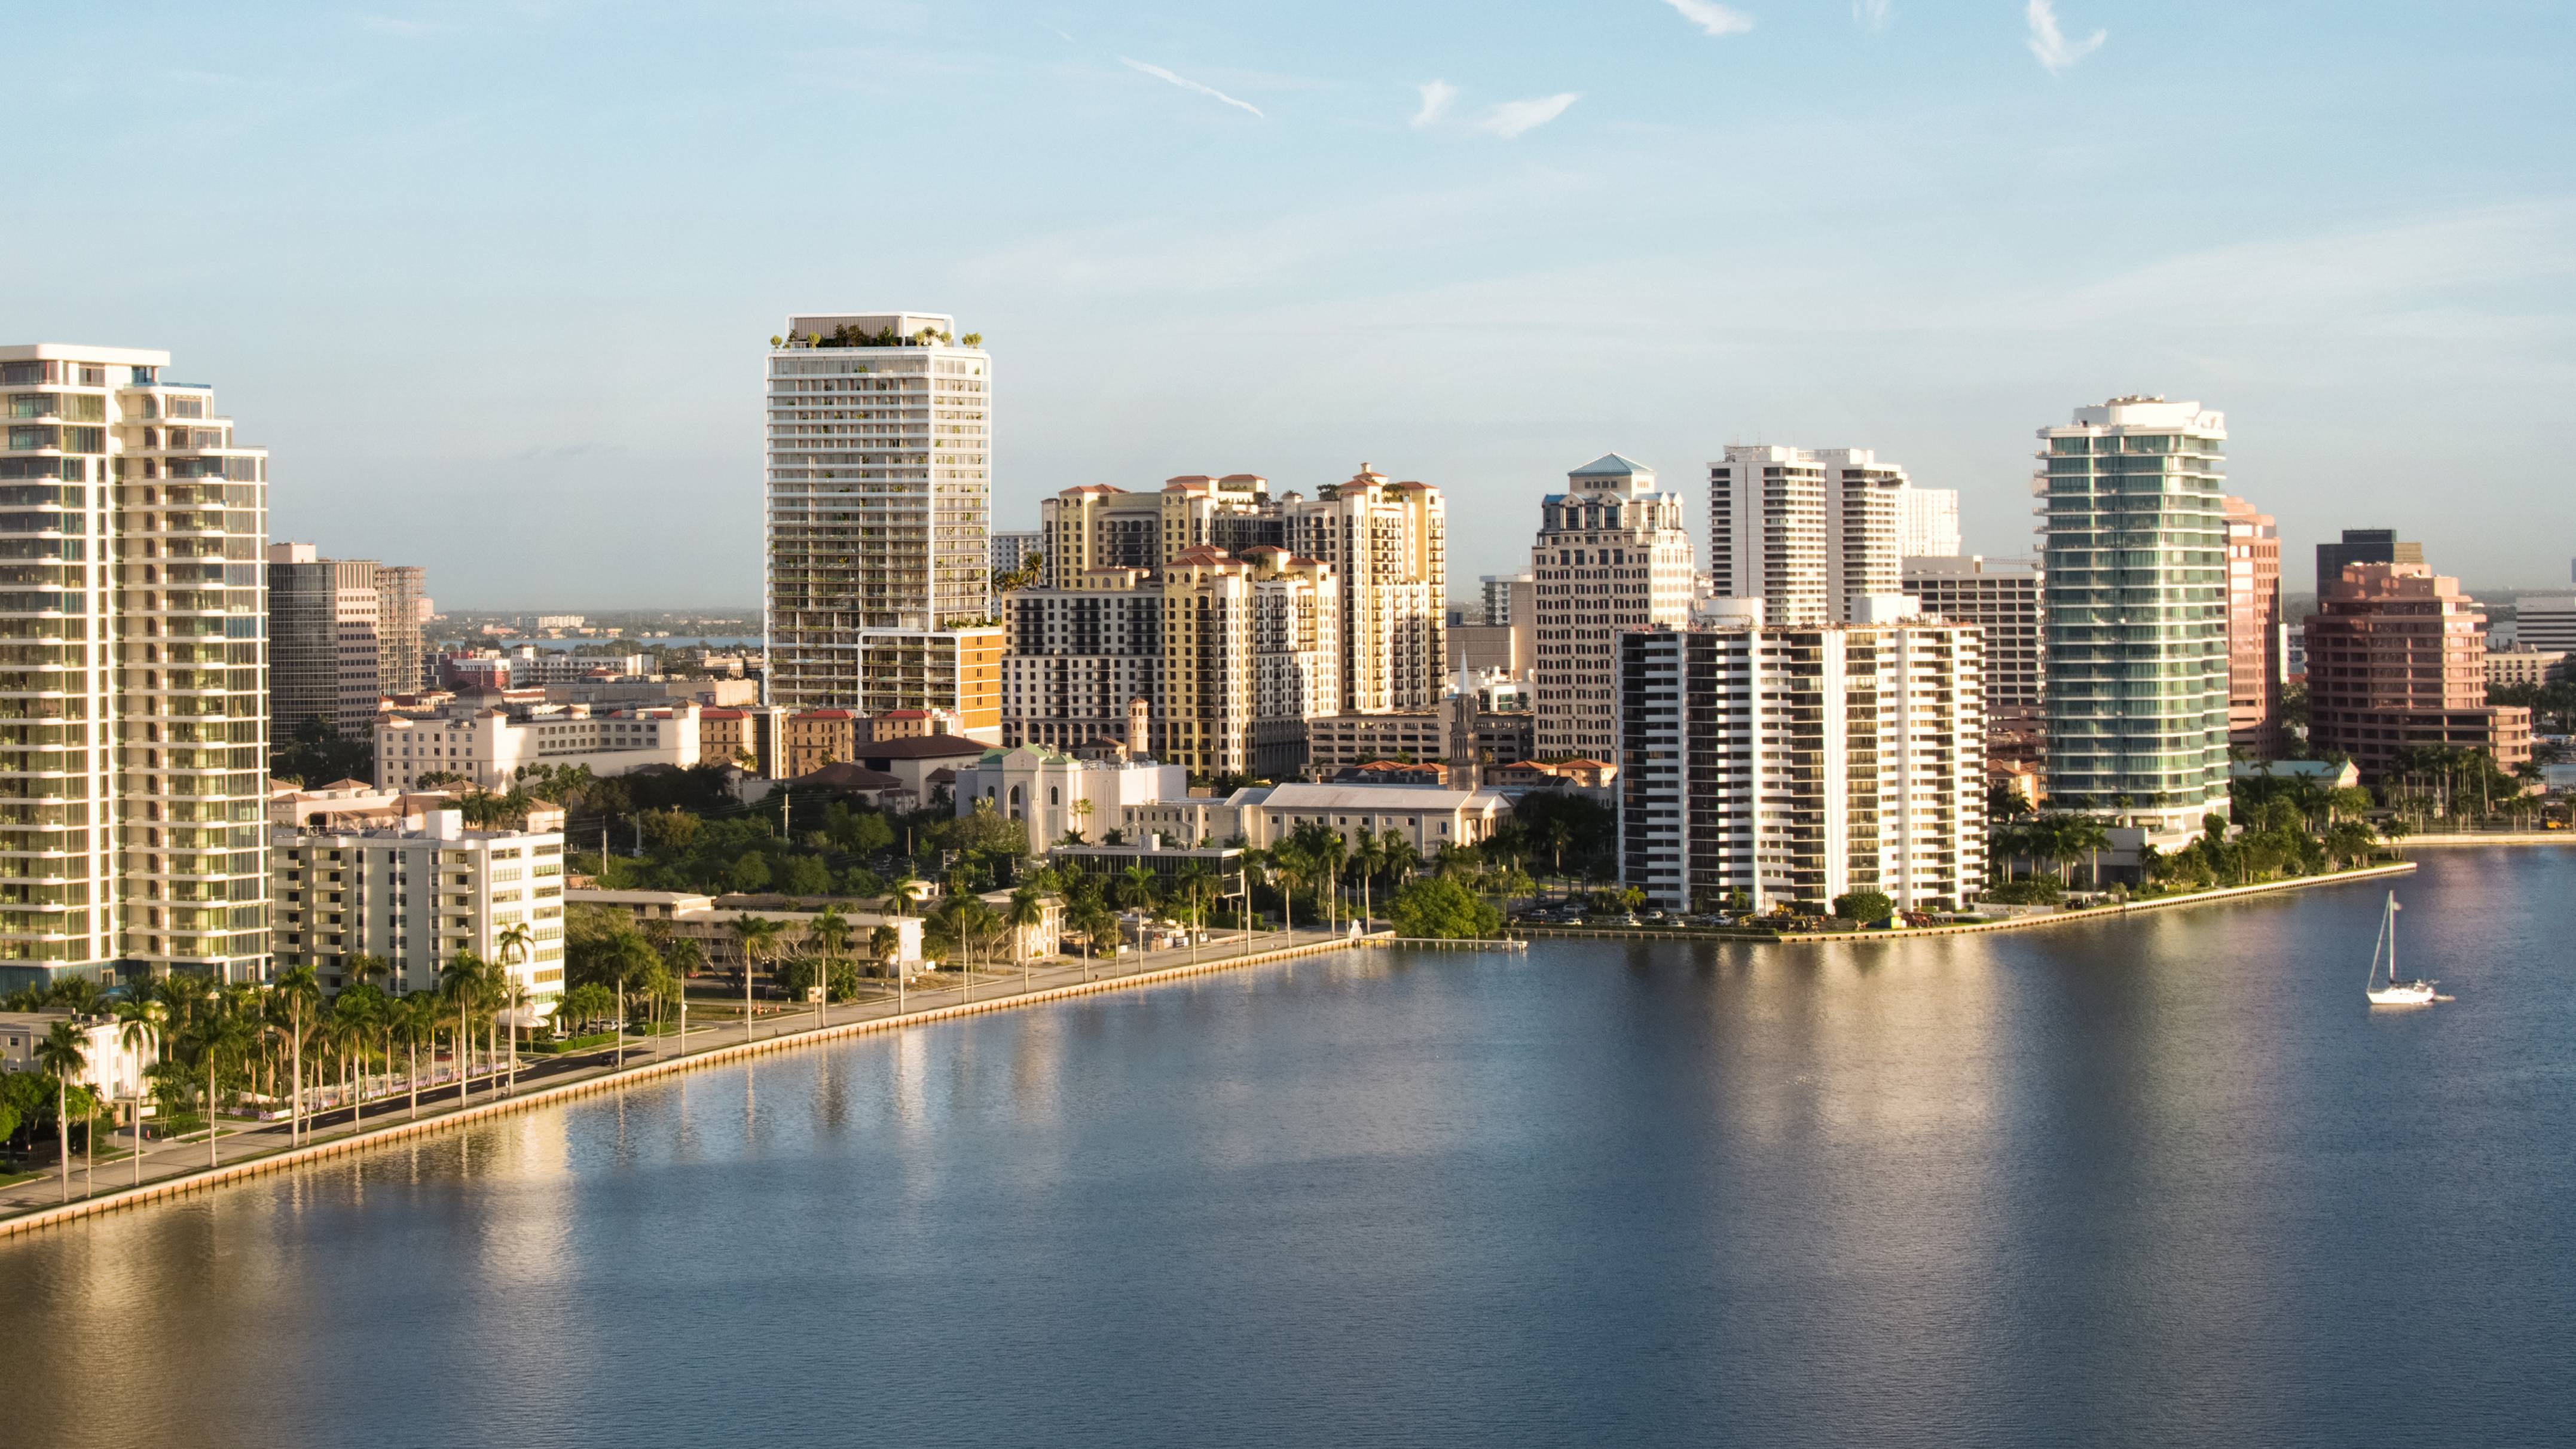
For a Malibu owner considering West Palm Beach, the essential question is not simply which residence to acquire, but where life will genuinely be centered after the move. Florida has no individual income tax, but leaving California requires more than purchasing a property elsewhere. California evaluates the full factual record and the taxpayer’s closest connections.
Domicile concerns a permanent home and the intention to remain, supported by actual living arrangements, family location, employment, and financial ties. The residence provides the setting for those connections. An elegant address cannot compensate for a household that continues to operate primarily from Malibu.
The objective is consistency: a Florida home used as a primary residence, a documented change in California ties, and records that reflect both. This is a planning framework, not individualized tax or legal advice; departure timing and filing positions should be reviewed with qualified advisers.
Whether purchased or leased, the West Palm Beach residence should support everyday life. Evaluate it against the household’s actual routines: working at home, keeping personal belongings, accommodating family, and returning between trips. A larger or more expensive Florida property is not a legal requirement.
When considering Alba West Palm Beach, ask whether the particular residence fits those routines. The relevant distinction is not prestige versus simplicity, but primary use versus occasional use. Confirm that the home can be occupied when the relocation plan requires it; selecting a future residence is not evidence of living there today.
Keep the geography precise. The destination here is West Palm Beach in Palm Beach County, not the separate Town of Palm Beach. Residence documents, correspondence, and the relocation timeline should consistently identify the actual home.
Waterfront living may shape the search, but the domicile analysis remains grounded in occupancy. For a buyer evaluating Forté on Flagler West Palm Beach, the residence strategy should begin with how the household intends to use the selected home-not what its name or purchase price might communicate.
Utility bills and household-service records help distinguish an occupied residence from a property that is merely owned. Moving records can document the relocation of personal belongings. Together, these materials substantiate the claimed move, although no single bill or delivery establishes domicile.
Family location, children’s schools, physicians, clubs, and community affiliations also contribute to the picture. Preserve records of genuine changes rather than assembling nominal connections. The file should describe the life being lived, not an idealized version of it.
Retaining the Malibu property does not eliminate the need to explain its continuing role. Selling, renting out, or fully vacating it can help demonstrate a decisive relocation rather than the addition of a seasonal Florida residence. No one action should be treated as a guarantee.
If Malibu remains in the portfolio, document its secondary use through actual personal-use patterns, rental arrangements where applicable, and the movement of belongings to Florida. Continued availability and use deserve careful review with advisers, especially when family or business ties remain in California.
Create a contemporaneous timeline recording the relocation decision, Malibu departure, Florida arrival, and genuine family, business, or lifestyle reasons. Non-tax motives are not mandatory, and a written narrative cannot override contrary conduct. Its value lies in accurately connecting decisions with actions and dates.
A 183-day target is not a California exit safe harbor. Florida has no individual-income-tax residency day test, yet travel records remain important when California questions a claimed departure. Day counts belong within the broader factual record, not above it.
Maintain a contemporaneous daily location log supported by boarding passes, receipts, toll records, and calendar entries. Record travel as it occurs rather than reconstructing a year from memory. A practical log can identify the date, location, travel movements, and supporting documents to make later reconciliation easier.
Do not assume that every jurisdiction counts travel days identically. Where another state’s statutory residency rules apply, confirm those rules with advisers and leave a margin below the applicable threshold. The maximum should not become a travel budget. Neither a fixed number of California nights nor a predetermined period in Florida guarantees the end of California residency.
An audit-ready file is organized and consistent, not immune from challenge. Residency audits can involve requests for multiple years of location logs, statements for all bank accounts and credit cards, travel records, and cellphone records. Plan for a review that extends beyond one Florida account or one calendar.
Organize the file into practical categories:
Residence and move: purchase or lease documents, moving records, utility bills, and household-service records.
Identity and administration: Florida identification, vehicle and voter registration, address changes, and any Declaration of Domicile.
Presence and daily life: location logs, travel evidence, financial statements, and relevant family or community records.
Tax and chronology: relevant returns, eligible homestead documentation, and the relocation timeline.
Grocery, restaurant, fuel, and personal-service spending can help test whether the reported Florida pattern matches third-party records. Review discrepancies while events are still fresh and preserve accurate explanations. Ask advisers to establish an appropriate records-retention approach rather than relying on a universal fixed period.
Obtain Florida identification and vehicle and voter registration promptly, as applicable. Align financial, employer, and tax correspondence with the Florida address. A Declaration of Domicile and a Florida homestead claim, where eligible, support the position but do not substitute for establishing the home.
California Form 540NR is the nonresident or part-year resident return used for the relevant departure-year filing position. California-source income can remain taxable after residency ends. Ending residency therefore does not necessarily end California tax obligations. The move date should be evaluated alongside income sourcing and the actual record.
For someone considering Mr. C Residences West Palm Beach, the final selection should connect personal preference with a credible occupancy plan. The same discipline applies to any purchase or lease: where will the household actually live, what remains in Malibu, and which records will show the transition?
The strongest residence strategy does not ask a property to prove more than it can. Ownership or a lease establishes access to a home; daily use and the wider pattern of ties give the domicile position substance.
Explore a West Palm Beach residence suited to your next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. California evaluates the overall facts and closest connections, so ownership alone does not establish that residency has ended.
No. A purchased or leased residence can serve as the primary home when actual occupancy and everyday living patterns support the claimed domicile.
No. A 183-day target does not guarantee the end of California residency; the full factual record matters.
Florida has no individual income tax and no individual-income-tax residency day test. Travel records still matter when the departing state examines the move.
If retained, its secondary role should be documented through actual use, rental arrangements where applicable, and the relocation of belongings. Continued California ties warrant review with advisers.
Preserve boarding passes, receipts, toll records, and calendar entries alongside the log. Record locations contemporaneously rather than relying on later recollection.
Utility bills, household-service records, and moving documents help substantiate household use. They contribute to the broader record rather than proving domicile on their own.
No. A Declaration of Domicile and an eligible homestead claim are supporting documents, not substitutes for actually establishing the new home.
An audit can request statements for all bank accounts and credit cards, alongside travel and cellphone records. Everyday spending can be compared with the reported location pattern.
Yes. California-source income can remain taxable after departure, and Form 540NR is the nonresident or part-year resident return for the relevant filing position.