For a family office choosing between Coconut Grove and Coral Gables, combined-market liquidity is only the starting point. Building-specific approvals, leasing permissions, financial condition and transaction timing should shape the eventual exit strategy.
For a family office, a residence in Coconut Grove or Coral Gables can serve two mandates: a private setting for family life and a capital allocation that remains manageable when priorities change. The acquisition decision should accommodate both, without letting the appeal of an address substitute for an exit plan.
The central distinction is straightforward: the available luxury-condominium statistics combine Coconut Grove and Coral Gables. They do not establish that one neighborhood sells faster than the other. A defensible choice therefore requires two separate judgments: which residence best suits the family, and which property's documented conditions support the intended holding period.
Treat neighborhood liquidity as context, not a promise. The more consequential comparison is between specific residences, their ownership requirements and the evidence supporting a future resale.
In Q3 2025, the combined Coconut Grove-Coral Gables luxury-condo market averaged 56 days on market, versus 81 days across the broader Miami luxury-condo market. That was the fastest pace among the Miami submarkets reviewed. Approximately 10 months of inventory also marked the lowest level among those neighborhoods.
Yet the same combined market had slowed materially: average days on market increased 75% year over year, from 32 to 56 days. Inventory declined 16.7% over that period. A favorable relative position, in other words, does not assure a short selling window.
The annual 2025 figures require a different reading. The combined area recorded a 74-day median selling period and approximately 11 months of inventory. An annual median is not interchangeable with a quarterly average, and neither establishes when a particular owner will receive sale proceeds.
By March 2026, combined inventory stood at 11 months, compared with nine months in March 2025, a 22.2% increase. That later snapshot reinforces the need to refresh assumptions before listing. Months of inventory measures market supply relative to sales activity; it is not an individual property's projected marketing period.
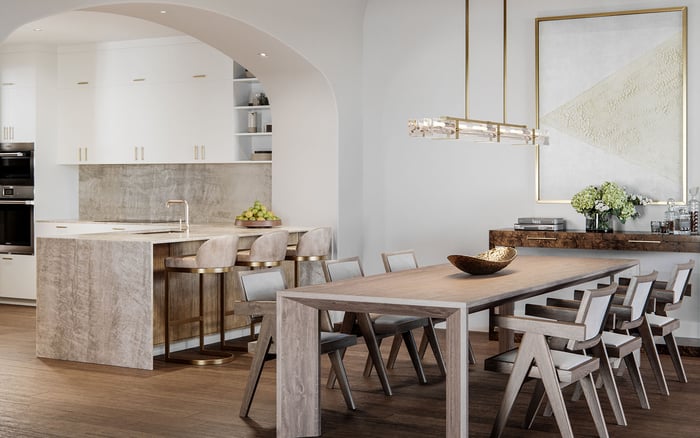
A family considering Park Grove Coconut Grove should seek recent, genuinely comparable resales rather than apply the combined area's average directly to a prospective purchase. Compare the residences by size, condition and pricing, and examine their marketing histories before adopting a selling-time assumption.
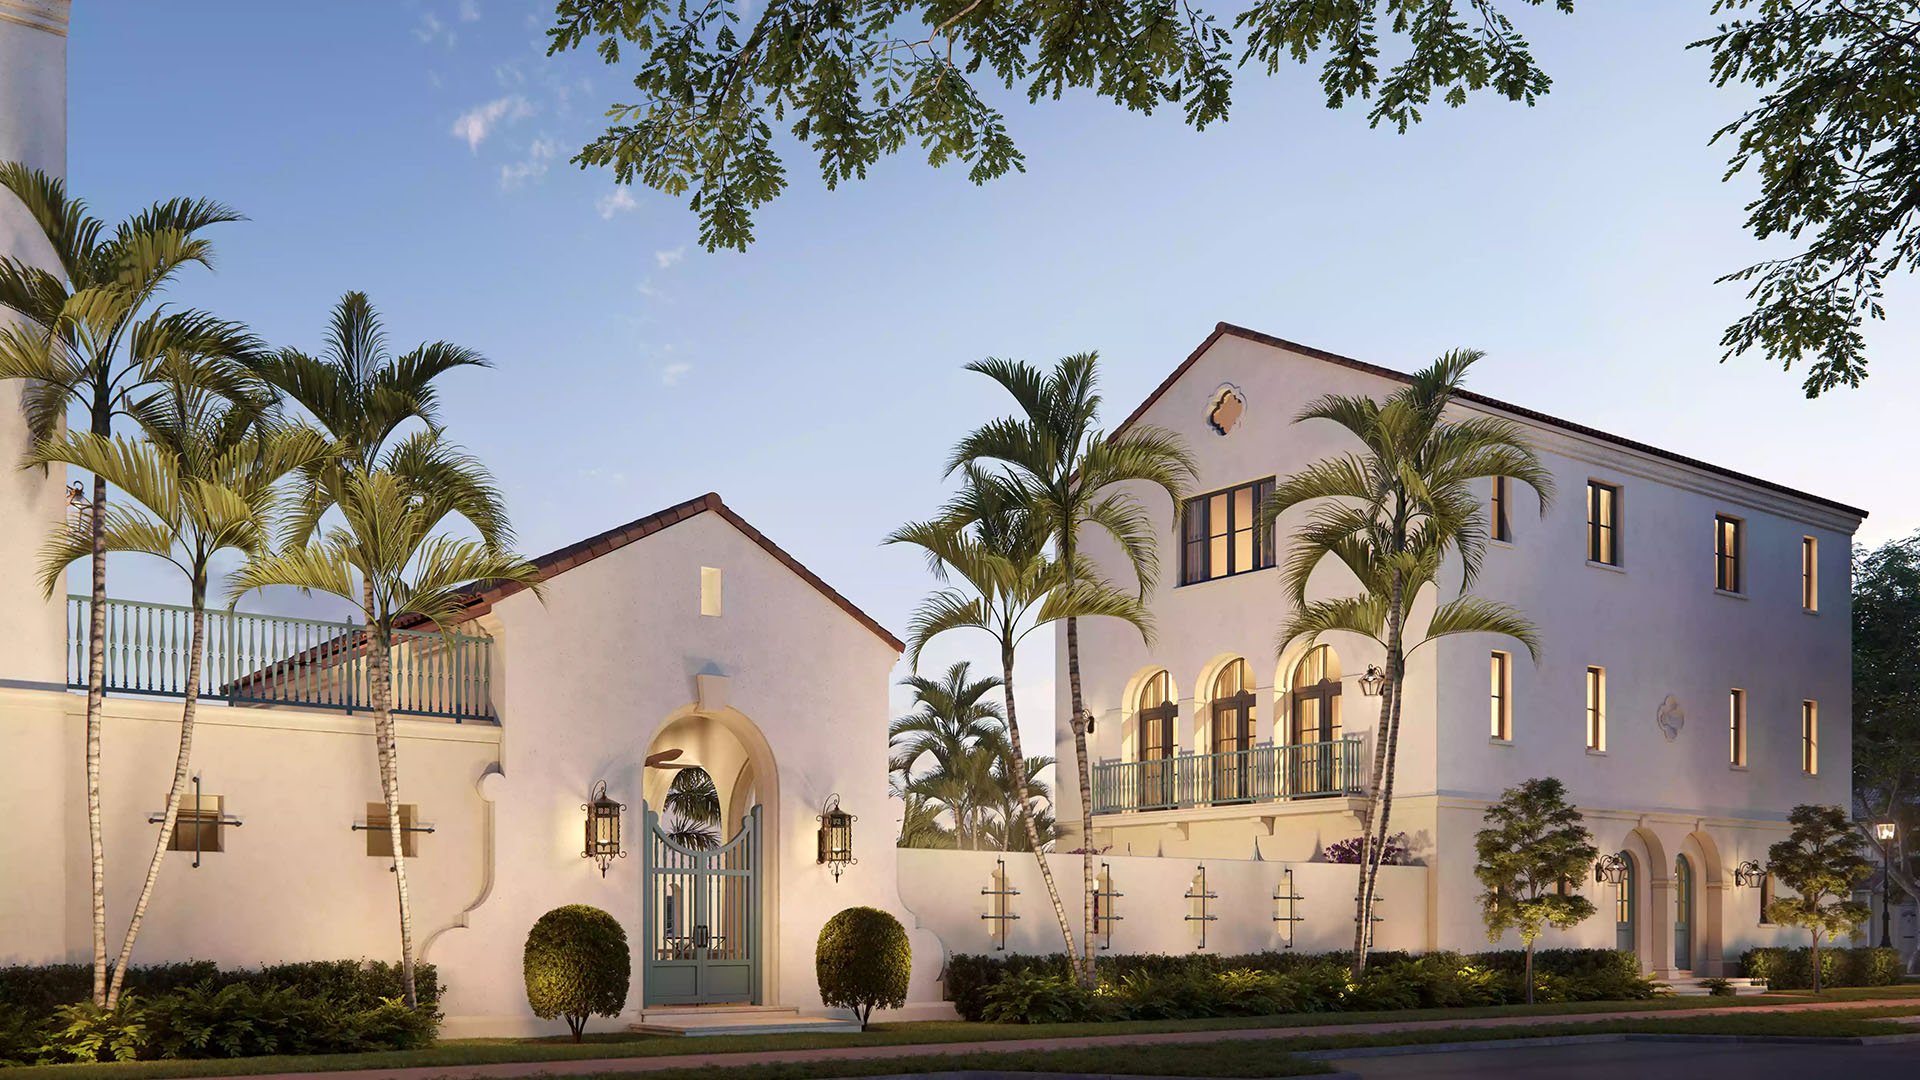
Apply the same standard when evaluating Ponce Park Coral Gables. First establish the nature and status of the contemplated purchase, then determine which transaction evidence is relevant. An anticipated future resale is not equivalent to a completed comparable transaction.
Neither project reference implies a verified resale pace, approval policy or leasing entitlement. The objective is a property-level comparison that separates family preference from financial assumptions. Where direct comparisons are weak, preserve more flexibility in the exit schedule rather than borrow confidence from neighborhood-wide statistics.
Buyer-approval requirements belong in the acquisition review, but should not be presumed identical across buildings. Have counsel obtain the target association's governing documents and confirm whether approval is required, what materials must be submitted and how the applicable timetable works.
For a family office, the proposed ownership structure deserves explicit attention. Ask whether the contemplated individual, trust or entity ownership requires particular documentation or consent. These are diligence questions, not statements that any specific restriction applies in Coconut Grove or Coral Gables.
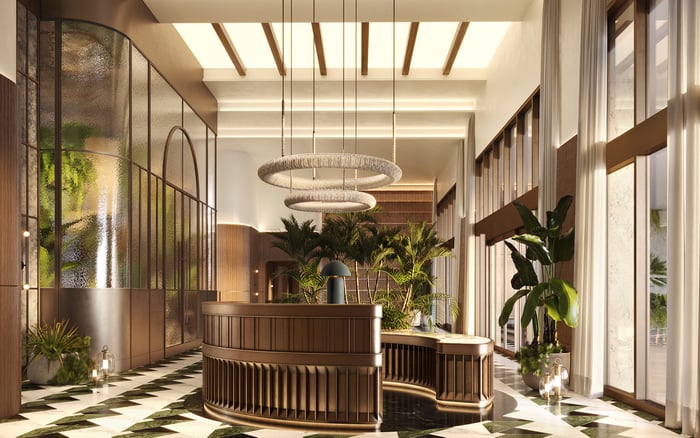
If Four Seasons Residences Coconut Grove enters the shortlist, use the same document-led approach. A project's identity does not establish its transfer requirements, and a purchaser should not infer administrative simplicity from positioning alone.
For eventual resale planning, request written confirmation of the applicable process and identify who is responsible for completing the application. Keep any approval timetable separate from the marketing assumption, and ask counsel which steps can overlap with other closing work. This avoids turning a market statistic into an unsupported transaction deadline.
An interim lease may be worth evaluating when a family's departure precedes its preferred sale date. Do not include rental income in the financial model until the property's leasing permissions and applicable requirements have been checked.
Request the governing provisions addressing minimum lease terms, rental frequency, any waiting periods, tenant approvals and other applicable conditions. Confirm their current status with counsel and the association rather than rely on a general description of the neighborhood. None of these restrictions should be assumed to apply universally.
For a prospective purchase at Cora Merrick Park, the same test applies: does the documented arrangement accommodate the family's intended use and potential rental strategy? The question is permission first, economics second.
If leasing is permitted, assess the proposed lease alongside the intended sale window. Ask counsel how possession, showings and contractual commitments would be managed. A conservative holding model should remain workable without rental income, rather than depend on an unconfirmed fallback.
Financial health, rental policies and ongoing repairs can affect liquidity. Request reserves information, insurance documentation, assessment details, inspection records and the status of ongoing work. Review those materials alongside recent resales, not after selecting an exit assumption.
The useful question is not simply whether an expense exists, but whether the family office can understand the exposure, budget for it and explain it clearly to a future purchaser. Ask advisers to distinguish known obligations from unresolved items and identify documentation that needs updating before a sale.
Carry those findings into the ownership budget. Test a longer holding period, potential additional expenditure and a sale without rental support. These are planning scenarios, not forecasts of a particular building's performance.
Build the exit plan in stages: preparation for sale, marketing, purchaser diligence, any applicable approvals and closing. Establish which stages may overlap and which depend on prior completion. Historical days on market should inform only the part of that schedule they actually describe.
Before acquisition, agree on a review cadence and decision triggers, such as a change in family use, updated carrying costs or materially different comparable sales. Refresh building documents and pricing evidence before deciding whether to hold, lease where permitted or sell.
A pooled liquidity figure does not establish the better choice between Coconut Grove and Coral Gables. That choice is the residence whose documented conditions align most closely with the family's use, capital commitments and tolerance for timing uncertainty. These condo statistics should not be extended to single-family homes.
Explore residences aligned with your family's ownership and exit priorities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe combined-market statistics do not establish a separate resale-speed advantage for either neighborhood. Compare individual properties and relevant resale histories instead.
Coconut Grove–Coral Gables averaged 56 days on market, compared with 81 days across the broader Miami luxury-condo market. That historical average is not a guaranteed selling timetable.
No. Average days on market increased 75%, from 32 to 56 days, despite the combined area's relative strength.
It represents the combined area's median selling period for annual 2025. It should not be treated as equivalent to a quarterly average or a deadline for receiving sale proceeds.
Combined inventory reached 11 months, versus nine months in March 2025, a 22.2% increase. Months of inventory does not predict an individual residence's marketing period.
No universal requirement should be assumed. Counsel should review the target association's documents to establish any approval obligations, ownership-structure requirements and timetable.
Only after applicable leasing permissions and requirements are confirmed should rental income enter the model. A conservative ownership budget should also be tested without that income.
Obtain governing documents, approval and leasing requirements, reserves information, insurance, assessment details, inspection records and information about ongoing repairs. Evaluate these alongside recent comparable resales.
No. These market figures concern luxury condominiums and should not be extended to single-family homes.
Separate sale preparation, marketing, purchaser diligence, applicable approvals and closing, identifying any overlap. Update the schedule with property-specific evidence rather than treating historical marketing averages as a liquidation promise.