A family-office framework for separating exchange qualification, rental permission, legal access, and title coverage before acquiring a South Florida residence intended for investment use.
For a family office acquiring a South Florida residence through a tax-deferred exchange, desirability is only the starting point. The decisive question is whether the intended investment use, permission to rent, enforceable access, and title coverage align. Each requires a separate inquiry. A favorable answer to one does not resolve the others.
Section 1031 applies to real property held for investment or productive business use, not property held primarily for personal use. A residence selected with future family enjoyment in mind therefore requires a disciplined acquisition plan-not an assumption that rental availability establishes investment purpose.
An effective checklist follows the transaction from intended ownership through post-closing operation. Its purpose is to expose mismatches before the family office accepts them.
The replacement-dwelling safe harbor requires ownership for at least 24 months immediately after the exchange. Within each of the two post-exchange 12-month periods, the residence must actually be rented to another person at fair rental value for at least 14 days. Advertising the property or keeping it available is not enough.
Personal use during each qualifying period cannot exceed the greater of 14 days or 10% of the days rented at fair rental value. Evaluate each period separately, not as a combined two-year average.
Before acquisition, ask the tax adviser to document:
The intended investment use and how the operating plan supports it.
The rental calendar needed for each qualifying 12-month period.
A personal-use tracking protocol and responsibility for maintaining it.
The remaining exchange requirements beyond this dwelling-use safe harbor.
The safe harbor addresses investment or business-use qualification. It neither approves the entire exchange nor replaces the other Section 1031 requirements.
A federal rental-day threshold does not confer permission to execute a particular lease. Before relying on an income plan, obtain and review the property's applicable rental restrictions, minimum lease terms, and approval procedures. Counsel should evaluate municipal requirements and association documents against the proposed occupancy pattern.
For a Brickell search that includes Una Residences Brickell, the question is whether the current governing terms for the specific acquisition support the intended rental schedule. A project name or residential designation cannot answer it.
Apply the same discipline when considering Alina Residences Boca Raton. Neither property's inclusion here establishes rental eligibility or exchange suitability. Underwriting should rest on the documents applicable to the actual residence, not a general impression of flexibility.
Treat Schedule A of the title commitment as a reconciliation exercise. Check the proposed insured, policy amount, ownership interest, vesting, and legal description against the intended acquisition. Ask counsel to resolve inconsistencies; a familiar street address is no substitute for the legal description.
For a family office, a useful internal control is a single written ownership instruction shared among the legal, tax, and closing teams. It should identify the intended acquiring party and interest, then be compared with the commitment and closing documents. This coordinates the teams; it does not replace tax advice about ownership structure.
Next, distinguish requirements from exceptions. Requirements identify conditions for issuing coverage; exceptions identify matters that may remain outside it. A commitment contemplating an issued policy does not establish that every relevant risk will be covered.
Request the underlying instruments for recorded exceptions and read them for practical consequences. An exception's brief description may not reveal the full restriction affecting occupancy, transfer, privacy, or usable space.
For each item, prepare a short decision record: what right or restriction exists, whom it benefits, how it affects the intended use, and whether the proposed policy excludes it. Ask counsel to identify any needed clarification or cure, and obtain the insurer's position on coverage.
The same review applies to a Miami Beach acquisition, including a residence under consideration at The Perigon Miami Beach. This is a review framework, not a statement that any particular exception burdens that project.
Look beyond ordinary easements. Recorded restrictions can include purchase options, rights of first refusal, purchaser or occupant approval rights, and re-entry or reverter provisions. Evaluate each against the acquisition and operating plan.
Do not dismiss exceptions labeled standard. They can encompass unrecorded possessory rights, survey-disclosed encroachments, and easements absent from public records.
A visible driveway does not, by itself, establish an enforceable right to travel between the parcel and a public road. Where the route crosses another owner's land, confirm a clearly defined roadway right or ingress-egress easement.
Ask counsel to trace the documented access route and compare it with the physical route used to reach the property. Review the instrument's scope against the intended use; an attractive entrance does not resolve the access question.
Florida's ways of necessity are conditional. The law recognizes distinct common-law and statutory rights, not an unconditional access entitlement for every landlocked parcel. Do not treat a potential necessity claim as equivalent to a confirmed access right in the acquisition file.
Public records cannot replace a survey. A commitment may exclude rights, interests, or claims that a correct survey would disclose but the records do not show. Boundary lines, improvements, and encroachments therefore warrant a coordinated title-and-survey review.
Ask the reviewing professionals to determine whether improvements cross boundaries or occupy easement areas. Utility, drainage, conservation, and shared ingress-egress easements can grant others rights over portions of the property, affecting usable space and privacy.
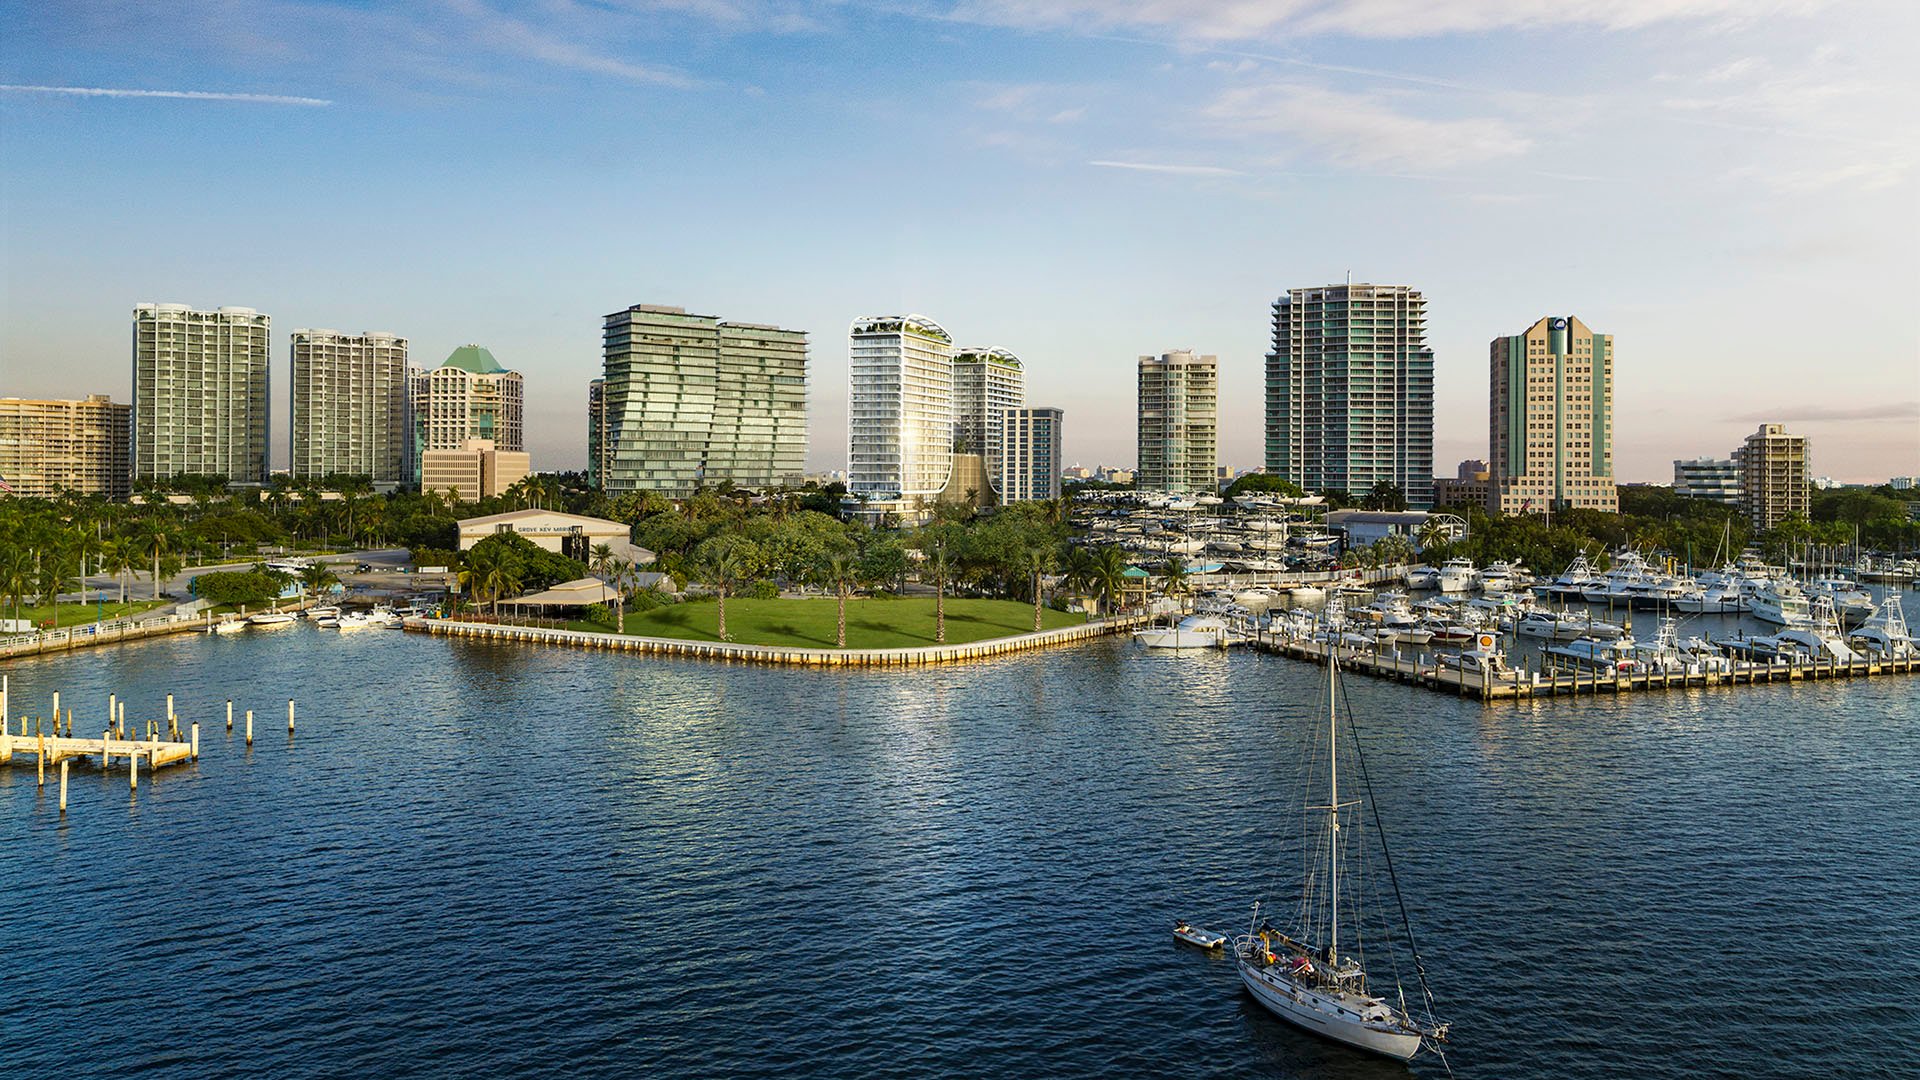
For a Coconut Grove search involving Park Grove Coconut Grove, the principle remains document-specific: ask counsel and the survey professional to determine the appropriate review for the ownership interest being acquired. Do not assume that a condominium interest and a standalone parcel require identical survey treatment.
If an endorsement is proposed, read its actual language. Restrictions, encroachments, and minerals endorsements address specified risks subject to their terms; they do not erase every underlying restriction or easement. Sample language is not a promise of coverage for a new acquisition.
Before authorizing closing, assemble a concise decision file covering tax-use planning, rental permissions, Schedule A reconciliation, exceptions, access, survey findings, and proposed coverage. Record unresolved matters explicitly, together with the responsible adviser and the family's decision, rather than letting them disappear into correspondence.
After closing, preserve rental and personal-use records separately for each qualifying 12-month period. Include the exchange reporting task: Form 8824 belongs with the federal income-tax return for the year of the exchange. Property selection is only the beginning; disciplined ownership must carry the plan forward.
For a considered South Florida residential search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationSection 1031 applies to real property held for investment or productive business use, not property held primarily for personal use.
The replacement dwelling must be owned for at least 24 months immediately after the exchange. Its rental and personal-use tests apply separately to each of the two post-exchange 12-month periods.
No. In each qualifying 12-month period, the dwelling must actually be rented to another person at fair rental value for at least 14 days.
Personal use in each qualifying 12-month period cannot exceed the greater of 14 days or 10% of the days rented at fair rental value.
No. It addresses the dwelling's investment or business-use qualification; all other Section 1031 requirements must also be satisfied.
Check the proposed insured, policy amount, ownership interest, vesting, and legal description against the intended acquisition.
Requirements identify conditions for issuing coverage. Exceptions identify matters that may remain outside coverage even when a policy is issued.
No. If access crosses another owner's land, confirm a clearly defined legal roadway right or ingress-egress easement rather than relying on the physical route alone.
A survey can disclose physical conditions that public records do not show, including encroachments. Reviewing it alongside title documents helps identify improvements crossing boundaries or occupying easement areas.
Preserve rental and personal-use records separately for each qualifying 12-month period. File Form 8824 with the federal income-tax return for the year of the exchange.