A disciplined buyer’s checklist for evaluating Oceana Bal Harbour’s operating assumptions, from budget variances and contract renewals to staffing coverage and amenity cost allocations.
At Oceana Bal Harbour, listed at 10201 Collins Avenue, Bal Harbour, Florida 33154, a buyer’s financial inquiry should be as considered as the residence itself. Advertised 24-hour concierge service, valet services, and an extensive amenity program make operational continuity central to the ownership proposition.
The question is not simply whether an assessment appears competitive. It is whether the assumptions behind it reconcile with signed obligations, staffing coverage, and actual expenditure. A useful review follows a clear sequence: budget assumptions, contract and payroll evidence, then actual results.
This is a proposed buyer-review framework, not a finding about Oceana’s finances. It focuses attention on what supports the service experience, rather than treating a polished amenity presentation or a low expense line as proof of value.
Oceana’s advertised services include around-the-clock concierge service and staffed security at the gated entryway, alongside multilevel security throughout the property. Valet services and two levels of underground parking add distinct operational categories. These descriptions do not establish headcount, the contractor mix, or the cost of providing coverage.
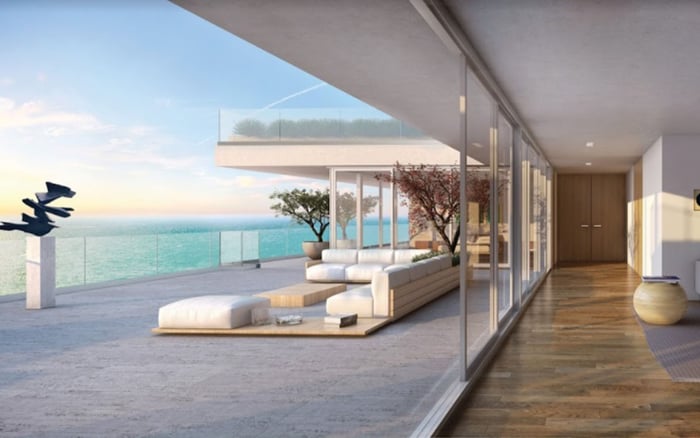
The aquatic amenities include a large relaxation pool, an Olympic-style lap pool, and two oceanfront jetted spas. Other advertised facilities include a full poolside restaurant and bar, an ocean-view fitness center, a yoga, meditation, and Pilates area, two clay tennis courts, and a spa with private lockers and changing rooms.
Together, these amenities suggest a service-intensive operation. They do not establish actual payroll or vendor expenditure. Buyers also considering Rivage Bal Harbour should apply the same distinction: an amenity description defines the service offering; its financial implications require separate documentation.
Begin with the current approved budget, prior budgets, year-to-date budget-to-actual results, and financial statements. Request consistent account mapping so changes in expense classification do not appear to be improvements or deterioration.
For each material variance, ask management to identify the cause and expected duration. A concise review should distinguish:
Timing differences: Expenses budgeted in one period but recognized in another, with the expected recognition date identified.
One-time items: Costs that require explanation but should not automatically become the recurring baseline.
Recurring changes: Higher rates, expanded scope, or continuing labor costs that may affect future periods.
Unspent allowances: Amounts left unused because of vacancies, deferred work, or services not yet delivered, if applicable.
A favorable variance deserves scrutiny too. Ask whether it reflects a sustainable saving or expenditure that has simply not yet occurred. An unfavorable variance likewise needs to be assessed in the context of service scope and timing, not in isolation.
The goal is a written reconciliation from the approved budget to actual results and the expected year-end position. Each explanation should reference supporting documentation rather than rest solely on verbal assurance.
A vendor’s opening price captures only part of the financial commitment. Request executed service agreements and amendments, then record the base price, covered services, renewal date, notice deadline, escalation formula, reimbursable expenses, and any minimum staffing commitment.
Check whether each agreement contains a fixed annual increase, a CPI adjustment, a wage-related adjustment, or fuel and insurance pass-throughs. These are review questions, not established Oceana contract terms. Where an adjustment exists, identify its calculation basis, effective date, and any cap or floor.
Reconcile the contractual calculation with the budget allowance and recent invoices. Ask whether a renewal or increase takes effect partway through the budget year and whether the following year would bear a full year of the higher cost. Identify separately any reimbursable charges outside the headline fee.
For a buyer weighing Fendi Château Residences Surfside alongside Oceana, the same discipline applies: compare documented obligations and service scope, not isolated vendor totals. A lower figure is not necessarily a like-for-like price.
Twenty-four-hour service describes availability, not headcount. Request schedules by department and shift showing how concierge, security, valet, and other relevant functions are covered. Then reconcile those schedules with payroll summaries and contractor invoices.
The review should identify employee versus contractor responsibilities, vacancies, overtime, temporary labor, benefits, and relief coverage. Ask how leave and absences are accommodated and whether the budget assumes positions will remain vacant. Use appropriately aggregated records to examine operating costs without requesting unnecessary personal employee information.
Where a vendor supplies personnel, compare invoiced coverage with contractual commitments. Where association employees and contractors serve related functions, request a clear division of responsibilities to identify possible overlap without presuming duplication.
The question is whether the staffing assumption can consistently deliver the stated service. Neither an advertised service commitment nor a payroll total answers that question alone. The schedule, contractual scope, and actual expenditure must align.
For each major amenity, establish who operates it and who bears its costs. Start with the poolside restaurant and bar: request the operating agreement and evidence of user revenue, management fees, any association subsidy, and common-expense allocations. Its advertised presence does not establish its financial arrangement.
Apply the same logic to the spa, fitness facilities, pools, jetted spas, and clay tennis courts. Ask which maintenance activities fall within a vendor’s base fee and which are charged separately. Where facilities share expenses, request the allocation basis rather than assuming each amenity has a self-contained budget.
This is not an argument for fewer amenities. It is a way to understand what the ownership contribution supports and whether that relationship is transparent. A sophisticated purchase can embrace extensive service while requiring precise accounting.
Before completing the review, request written confirmation of the residence’s current assessment and applicable allocations. Do not use a generic maintenance figure to build a unit-specific ownership budget without confirming its billing period, calculation basis, and current applicability.
If the search extends to The Surf Club Four Seasons Surfside, carry the same evidence checklist into that evaluation without assuming equivalent operating structures. Consistent questions make comparisons more useful; identical assumptions do not.
The strongest conclusion is a documented connection between the promised service, the obligations required to deliver it, and the amounts actually spent. Any unresolved difference should become a specific follow-up question, not an unsupported judgment about the building.
For a considered approach to South Florida luxury ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOceana Bal Harbour is listed at 10201 Collins Avenue, Bal Harbour, Florida 33154.
Reconcile budget assumptions with executed contracts and payroll evidence, then compare them with actual results. This is a proposed review framework, not a finding about the building’s finances.
Request the current approved budget, prior budgets, year-to-date budget-to-actual results, and financial statements. Ask for explanations of material variances and changes in expense classification.
No. Ask whether the difference reflects sustainable savings, timing, vacancies, or work that has not yet occurred.
Check for fixed increases, CPI adjustments, wage-related adjustments, and fuel or insurance pass-throughs. None of these terms should be assumed to apply to Oceana without reviewing executed agreements.
No. It describes advertised service availability, not a verified employee count or staffing model.
Reconcile department-and-shift schedules with payroll summaries and vendor invoices. Review vacancies, overtime, temporary labor, benefits, and the division between employees and contractors.
No. Request operating agreements and evidence of user revenue, management fees, any subsidy, and common-expense allocations to establish the arrangement.
Oceana advertises a large relaxation pool, an Olympic-style lap pool, and two oceanfront jetted spas. Ask how maintenance responsibilities and expenses are allocated across these facilities.
No. Obtain unit-specific written confirmation and verify the billing period, calculation basis, and current applicability before using it in an ownership budget.