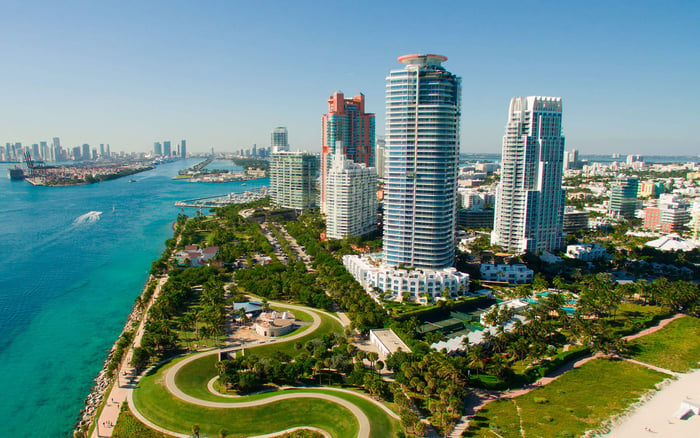
A rental-eligible residence requires more than permission to lease. This buyer’s guide separates exchange-use documentation from management-contract protections, with practical attention to owner authority, vendor charges, and a clean management transition.
For a South Florida buyer, an exchange into a residence can pair investment discipline with exceptional surroundings. The essential distinction is less glamorous: permission to rent is not proof that a property qualifies for Section 1031 treatment. The real property must be held for investment or productive use in a trade or business, rather than personal use.
A management agreement can help organize that purpose, but signing one does not establish eligibility. A stronger file connects the acquisition, rental activity, pricing, occupancy, and owner decisions. Contract protections belong alongside those records, not in place of them.
A buyer considering 2200 Brickell should therefore separate the residence’s appeal from the proposed exchange structure. This article makes no representation about any linked project’s rental permissions, management terms, or exchange eligibility. Those questions require property-specific review.
The dwelling-unit safe harbor sets defined conditions under which qualifying investment or business use will not be challenged. For replacement property, ownership must continue for at least 24 months immediately after the exchange.
During each of the two 12-month periods following the exchange, the dwelling must be rented to another person at a fair rental for at least 14 days. In each period, personal use must not exceed the greater of 14 days or 10% of the days rented at a fair rental.
Build the file around those separate periods, not a blended two-year total. Keep closing documents, executed rental agreements, occupancy dates, payment records, and a calendar distinguishing rental activity from personal use. Have the tax adviser review classifications rather than relying on a reservation calendar alone.
Personal use can include certain family-member stays and below-market occupancy under the applicable rules. Revenue from a stay does not automatically make it qualifying fair-rent occupancy. Falling outside the safe harbor does not automatically disqualify an exchange, but investment use then remains subject to the applicable facts and law.
Fair rental depends on the facts and circumstances when the rental agreement is entered into. Preserve evidence from that moment: the quoted rate, relevant comparisons, lease terms, concessions, and an explanation for any unusual pricing decision. These are practical documentation recommendations, not a prescribed federal checklist.
For a residence under consideration in Miami Beach, such as Setai Residences Miami Beach, ask how the proposed manager would retain this evidence alongside the signed agreement. A polished owner statement is useful, but it should not replace the underlying record of who occupied the property, when, and on what terms.
Request reporting that distinguishes paid rental nights, owner stays, family occupancy, complimentary stays, and vacancies. Those operational categories still require tax review. A manager’s label does not settle the legal treatment.
The safe harbor does not prescribe a management company or rental platform. Evaluate the agreement as an operating arrangement, not a certificate of tax compliance.
Ask counsel to define the manager’s services and reporting obligations in writing. Consider how rental agreements, receipts, occupancy logs, pricing approvals, maintenance records, and owner statements will be retained and delivered. Specify access during the engagement and after termination, including the format of any exported records.
Distinguish authority to market the residence from authority to bind the owner. Ask who may execute leases, grant concessions, approve refunds, or arrange complimentary occupancy. The aim is to make decisions traceable and prevent administrative convenience from obscuring the property’s actual use.
These provisions are suggested negotiating points, not safe-harbor requirements. No particular contract wording substitutes for qualifying ownership and use.
Document owner oversight without creating an expectation of unrestricted personal access. Consider a written approval framework for rates, discounts, lease extensions, maintenance spending, and exceptions to the rental plan. The appropriate thresholds depend on the negotiated arrangement; the exchange rules supply no universal amount.
For a buyer evaluating Jade Signature Sunny Isles Beach, the relevant diligence question is how any proposed management arrangement would handle owner instructions and occupancy requests. The project name itself says nothing about those contractual rights.
Ask for written records of approvals and overrides, including who authorized them and when. If the owner requests a family stay or discounted occupancy, route that decision to the person maintaining the tax-use calendar. Operational approval and tax classification are separate decisions. Both deserve a record.
Review vendor charges separately from the management fee. As a negotiating matter, ask whether charges may include procurement fees, coordination fees, markups, or payments involving affiliated vendors. Do not assume any particular practice applies to a residence or manager.
Where such charges are permitted, consider requesting the underlying invoice, the calculation of any added fee, disclosure of relevant affiliations, and a written approval process for exceptions. Ask how credits and refunds would appear in owner statements and how invoice access would work after the relationship ends.
This is commercial diligence, not a Section 1031 test. Transparent expense records help an owner understand the operation, but a clearly itemized vendor charge does not establish investment use. Keep the contract’s financial controls distinct from the exchange’s ownership and occupancy evidence.
A termination clause should address more than the right to give notice. Consider negotiating the notice procedure, any exit charges, treatment of existing reservations, final accounting, transfer of funds held, and delivery of keys and operating records. The appropriate terms must come from the actual agreement, not an assumed standard notice period.
A buyer considering Alba West Palm Beach can apply the same discipline: ask how a proposed manager would hand over the residence and its documentation without losing the occupancy history.
Changing managers is distinct from changing the property’s actual rental or personal use. The right to terminate an agreement does not answer the tax consequences of converting the residence to personal enjoyment. Have the tax adviser review any proposed use change, and preserve records across the transition.
The dwelling-unit safe harbor does not excuse the other Section 1031 requirements. Identify replacement property within 45 days after transferring the relinquished property. Identification must be written, signed by the taxpayer, and delivered to an appropriate exchange party.
Receive the replacement property by the earlier of 180 days after that transfer or the taxpayer’s return due date, including extensions, for the transfer year. Actual or constructive receipt of proceeds can undermine deferred-exchange treatment; a qualified-intermediary arrangement helps keep proceeds outside the taxpayer’s receipt. Report the exchange on Form 8824 with the federal return for the exchange year.
Maintain two coordinated files: one for exchange execution, another for ownership and operation. Together, they should tell a consistent story without confusing contractual protections with tax qualification.
For a discreet perspective on South Florida residences and buyer diligence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The real property must be held for investment or productive use in a trade or business, rather than personal use.
The replacement dwelling must be owned for at least 24 months immediately after the exchange. Rental and personal-use conditions also apply during each of the two 12-month periods.
The dwelling must be rented to another person at a fair rental for at least 14 days during each of the two 12-month periods following the exchange.
In each 12-month period, personal use must not exceed the greater of 14 days or 10% of the days rented at a fair rental. Certain family stays and below-market occupancy can count as personal use.
No. The dwelling-unit safe harbor specifies ownership, rental-use, fair-rent, and personal-use conditions, not a required manager or rental platform.
Preserve pricing evidence and rental terms from when the agreement is entered into, including relevant comparisons and concessions. Fair rental depends on the facts and circumstances at that time.
They are commercial negotiating points, not requirements of the dwelling-unit safe harbor. Their terms should be evaluated in the actual management agreement.
No. Management termination rights are separate from the tax consequences of changing actual rental or personal use, which should be reviewed with a tax adviser.
Identify replacement property within 45 days after transferring the relinquished property. Receive it by the earlier of 180 days after that transfer or the return due date, including extensions, for the transfer year.
No, but investment use remains subject to the applicable facts and law. Meeting the safe harbor also does not excuse compliance with other Section 1031 requirements.