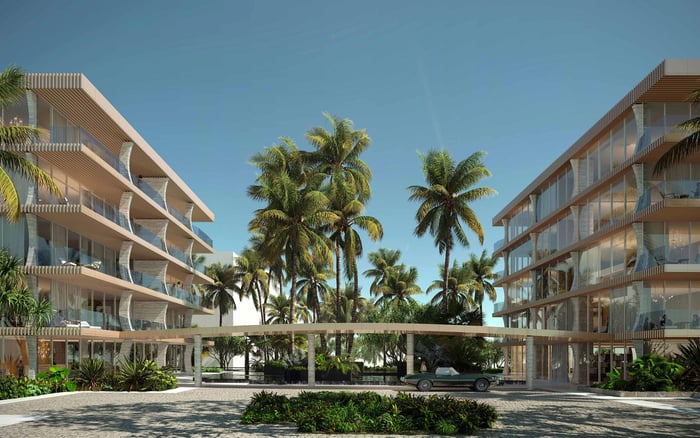
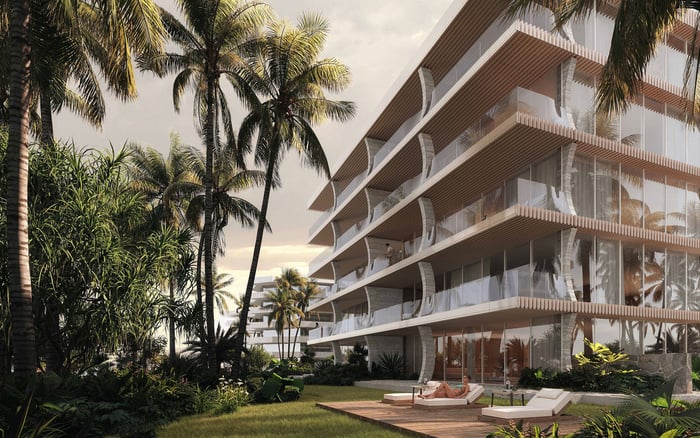
A provisional shortlist of five luxury residential offerings for privacy-minded buyers, with a disciplined look at association budgets, insurance, reserves, and the ownership details that determine financial exposure.
For a luxury condominium buyer, full-service living should mean more than an elegant arrival and well-maintained common spaces. It should also mean knowing which expenses the association carries, which remain personal obligations, and how future building work will be funded. Privacy is a lifestyle preference; financial visibility is a purchasing discipline.
The five offerings below form a provisional lifestyle-and-diligence shortlist, not a verified ranking of reserve strength or assessment risk. Their settings and services warrant consideration, but no position establishes fully funded reserves, favorable insurance deductibles, or protection from future special assessments. Those conclusions require current association records and transaction-specific review.
In Boca Raton, The Residences at Mandarin Oriental Boca Raton illustrates the central distinction: hotel-branded services can be compelling without resolving every question about long-term ownership costs.
1. Mandarin Oriental Residences Boca Raton: Via Mizner, downtown Boca Raton
Located within Via Mizner, Mandarin Oriental offers hotel-branded residential services. The ownership-cost categories outlined here distinguish the association assessment, covering building insurance, common-area maintenance, and building staff, from Via Mizner Golf & City Club initiation and monthly dues, plus property taxes. Buyers should verify the current allocation and terms before relying on this breakdown.
That separation helps buyers structure an ownership budget; it does not demonstrate reserve sufficiency. Reconcile the condominium assessment with current financial statements, insurance terms, reserve contributions, and separate club obligations. The first-place position reflects service appeal and the cost categories presented here, not a finding of lower assessment risk.
2. La Clara: 1515 South Flagler Drive, West Palm Beach
La Clara offers a full-service residential setting on the Intracoastal waterfront. For buyers drawn to West Palm Beach, its South Flagler Drive address places the water at the center of the ownership proposition.
The financial review should be equally location-specific. Current reserve funding, master-policy deductibles, and waterfront-maintenance responsibilities remain essential purchase-level questions. The distinction is not simply whether insurance appears in the monthly assessment, but what the policy covers and which liabilities remain with the association or individual owner.
3. SeaGlass: Boutique coastal living on Jupiter Island
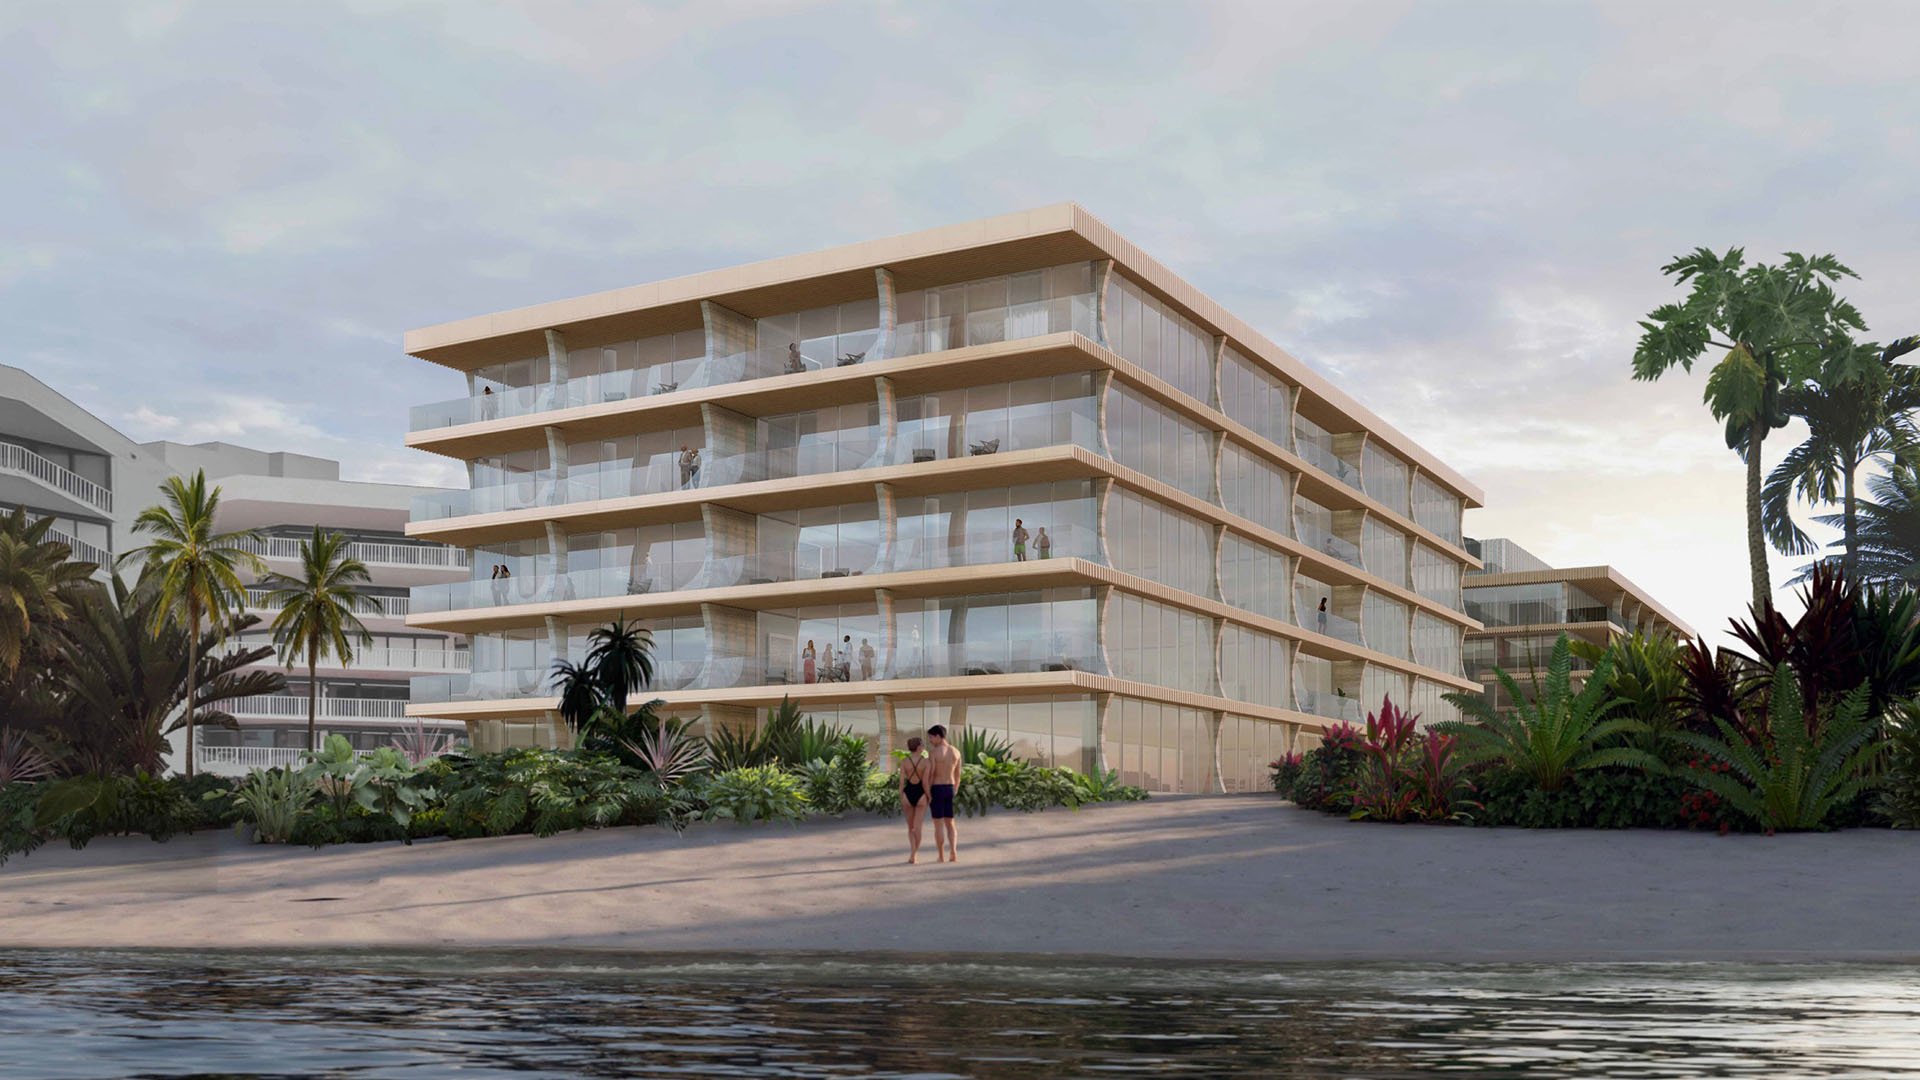
SeaGlass is a boutique luxury condominium in a low-density coastal setting. Its appeal to privacy-focused buyers rests on its residential scale and setting, not a demonstrated financial advantage over larger properties.
Coastal insurance and building-envelope exposure deserve particular scrutiny. Ask how maintenance obligations are defined, what work is anticipated, and how the reserve plan addresses it. A more intimate residential environment is not evidence of lighter capital obligations or reduced exposure to special assessments.
4. The Residences at The Boca Raton: private resort-campus setting
The offering is described as private residences within The Boca Raton resort grounds, with hotel-service and beach-club access. For buyers who prioritize a resort-connected lifestyle, that combination merits consideration alongside conventional full-service condominium options.
Before making a direct comparison, confirm that the specific offering is a purchasable condominium and establish its legal ownership structure. Its inclusion here is conditional on that verification, not confirmation of condominium ownership. Access rights, service obligations, and separate membership charges also require confirmation. Resort affiliation alone does not establish which benefits attach to ownership or which costs fall outside an association budget.
5. 1000 Ocean: Boca Raton Inlet waterfront
1000 Ocean combines ocean and Intracoastal frontage with full-service building operations and optional resort membership. Its inlet location offers a distinctive waterfront setting for buyers seeking service without assuming that resort membership is part of the condominium assessment.
That setting also calls for careful insurance and capital-maintenance review. Examine waterfront obligations, including applicable seawall responsibilities, alongside reserve planning and policy terms. Keep optional resort costs separate from the core ownership budget to distinguish the service offering from the building's financial obligations.
Condominium dues typically support master insurance, common-area maintenance, staffing, and reserves. A single monthly figure, however, does not reveal how much funds daily operations and how much accumulates for future work. Request the allocation rather than inferring financial strength from the size of the payment.
Regular assessments fund common expenses within the annual budget. Special assessments address expenses outside that budget. A meaningful review connects the operating budget, reserve study, current reserve balances, and anticipated maintenance rather than treating each document as an isolated disclosure.
When considering Alina Residences Boca Raton alongside the shortlist, apply the same document standard. The comparison should rest on verified obligations and funding, not an assumption that a different residential identity produces more predictable costs.
Building insurance within association dues is not a complete personal insurance budget. Owners should budget separately for unit insurance and applicable flood coverage. Reviewing the master policy with an insurance adviser can clarify coverage boundaries and deductible exposure before those questions become urgent.
Waterfront ownership calculations should also account for seawall maintenance where applicable and higher property-insurance premiums associated with coastal exposure. Confirm responsibility for each relevant waterfront component rather than assuming every obligation is shared in the same way.
For a West Palm Beach comparison involving Forté on Flagler West Palm Beach, ask the same policy and maintenance questions. No project name or waterfront address substitutes for current coverage terms and a clear allocation of responsibility.
Request declarations, bylaws, budgets, financial statements, the reserve study, and current reserve balances. Review insurance, assessment records, litigation, and maintenance responsibilities together. Board minutes covering the previous 12-36 months can identify matters that warrant follow-up before committing.
Check the resale or estoppel certificate for current assessments, delinquencies, and pending special assessments. Reconcile those disclosures with the budget and meeting records. If an obligation remains unclear, obtain an explanation before treating the monthly fee as the complete carrying cost.
The strongest choice is not necessarily the lowest assessment or the most elaborate service offering. It is the residence whose privacy, services, legal rights, and financial obligations fit the buyer's expectations. Reserve strength must be demonstrated, insurance transparency must be specific, and surprise-assessment exposure must be evaluated rather than promised away.
For a discreet conversation about your Palm Beach County residential priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It is a provisional lifestyle-and-diligence shortlist, not a verified comparison of reserve balances, funding levels, or assessment risk.
Its provisional position reflects hotel-branded residential service and the ownership-cost categories outlined in the article. Those categories do not establish stronger reserves or lower assessment risk.
The cost categories include condominium assessments, Via Mizner Golf & City Club initiation and monthly dues, and property taxes. Buyers should confirm the current terms of each.
La Clara is at 1515 South Flagler Drive in West Palm Beach, on the Intracoastal waterfront.
SeaGlass offers a boutique, low-density coastal setting on Jupiter Island. Its insurance and building-envelope obligations still require careful review.
Only after confirming that the specific offering is a purchasable condominium and verifying its legal ownership structure. Service rights, beach-club access, and separate membership charges also need confirmation.
Resort membership is described as optional. Buyers should distinguish its costs from condominium assessments and other ownership expenses.
No. Owners should budget separately for unit insurance and applicable flood coverage, and review the master policy's coverage boundaries and deductibles.
Request the reserve study, current reserve balances, budgets, and financial statements. Board minutes covering the previous 12–36 months help place those figures in context.
Review the resale or estoppel certificate for current assessments, delinquencies, and pending special assessments. Reconcile those disclosures with board minutes and financial records.