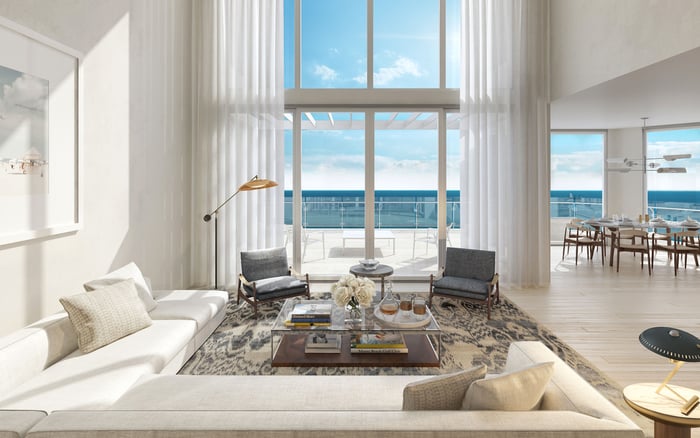
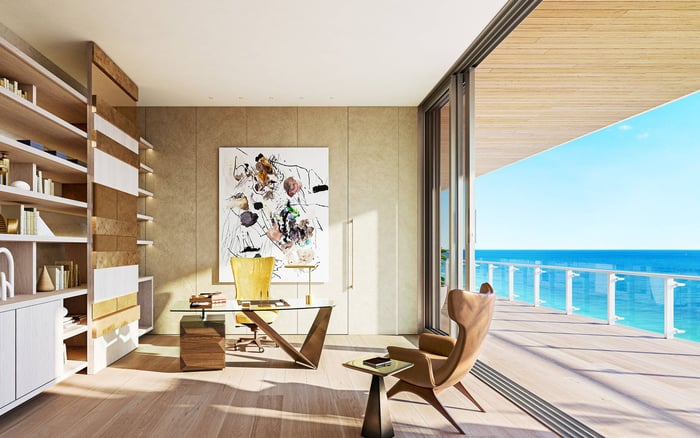
A multigenerational move to South Florida calls for more than the right address. Prioritize schools and healthcare, adaptable living arrangements, insurance, taxes, and everyday independence before selecting a residence.
Relocating teenagers and retired parents to South Florida is not simply a search for more bedrooms. It is a decision about how several generations will live independently, share time, and manage changing needs. The most compelling residence supports the school morning, the specialist appointment, and the quiet evening with equal ease.
For a luxury buyer, that means defining the household's requirements before selecting the architecture. Privacy, predictable expenses, and practical access deserve the same attention as outlook and finishes. These five decisions belong in sequence: establish the location, define the living arrangement, test risk and cost, then confirm everyday independence.
1. Choose the school-and-healthcare location: essential services first
Begin with Miami-Dade, Broward, or Palm Beach County, then narrow the search to exact addresses. Compare school options alongside journeys to hospitals, specialists, and pharmacies. A city's reputation is no substitute for checking the routes and services your household will actually use.
Florida schooling options include traditional public, magnet, charter, and private schools, as well as scholarship programs. Confirm the applicable assignment or admissions requirements directly before committing. For retired parents, establish whether preferred providers can accommodate their needs. The first decision is where both generations' essential routines can work-not which destination wins on image.
2. Define the living arrangement: privacy and adaptable access
Decide whether parents want shared living space, a dedicated suite, or a separate nearby residence. Ask teenagers what privacy means to them, too. Evaluate distinct sleeping areas, study space, and comfortable gathering rooms as household requirements, not assumed benefits of a larger floor plan.
Assess step-free access, entry-level sleeping and bathing where relevant, and room for future assistance. In a condominium, examine the complete journey from arrival to the residence, including elevator access. Review the actual layout rather than treating a luxury designation as evidence of accessibility. The aim is flexibility without making either generation feel like a guest.
3. Establish insurance affordability and storm readiness: examine the exact property
Review homeowners and flood coverage before committing to a purchase. Standard homeowners insurance typically excludes flood damage, so separate flood coverage deserves its own consideration. Confirm the proposed policies' coverage, exclusions, and costs rather than relying on a general neighborhood estimate.
Pair that review with a household emergency plan. Check property-specific flood exposure and evacuation guidance, identify multiple evacuation routes consistent with that guidance, and arrange emergency alerts. Prepare essential supplies, medications, protected documents, and photographs of household contents. Assign responsibility for helping each family member so storm preparation does not depend on one person's availability.
4. Calculate post-move taxes and recurring costs: budget for your ownership
Florida's homestead exemption reduces the taxable value of an eligible primary residence, but eligibility must be established. Do not assume the seller's tax position will become yours. A homestead exemption does not automatically follow an owner to another home; a new application is required.
After the first homesteaded year, Save Our Homes generally limits annual assessed-value increases to the lower of 3% or the Consumer Price Index change. It does not cap the total property-tax bill. Eligible owners moving between Florida homesteads may transfer some or all of their accumulated assessment benefit. Establish the new homestead within three years of January 1 of the abandonment year, and confirm the generally applicable March 1 filing deadline for homestead and portability applications. Include insurance, association charges where applicable, maintenance, and transportation in the household budget.
5. Plan everyday transportation: independence with a backup
Map school, medical, shopping, and social trips before choosing the neighborhood. Decide who drives, who needs assistance, and what happens when the usual driver is unavailable. A teenager's afternoon activity and a parent's medical appointment should not routinely compete for the same car or caregiver.
Test journeys at the times the household expects to travel rather than relying on an appealing map distance. Verify alternative transportation arrangements and consider how groceries, prescriptions, and appointments would be managed during a disruption. Keep everyday backup plans distinct from evacuation planning, while ensuring both account for roads that could become flooded.
Once those priorities are settled, compare residences against one written checklist. In Coconut Grove, a buyer considering Four Seasons Residences Coconut Grove should first establish the exact school and medical journeys, then examine circulation and the separation of private spaces within the proposed residence. The project name alone does not resolve either question.
Apply the same discipline in Coral Gables when considering The Village at Coral Gables. Request the relevant plans and evaluate the entrance, sleeping arrangements, bathrooms, and space for assistance against your family's requirements. Assess each residence individually; confirm its suitability rather than infer it from the setting.
The useful comparison is not simply between neighborhoods. It is between complete daily arrangements: the home, the journeys, the service providers, and the people responsible for making them work.
For a Fort Lauderdale search that includes Andare Residences Fort Lauderdale, build a weekly calendar before judging convenience. Plot school commitments, medical visits, shopping, and leisure, then verify the practical routes. Do not assume a particular travel time or level of accessibility without checking.
The same approach applies to Alba West Palm Beach in West Palm Beach. Evaluate the exact residence, anticipated carrying costs, and transport arrangements together. Lifestyle preferences matter, but they should complement confirmed everyday needs rather than replace them.
Bring both generations into the final review. Ask teenagers to identify the routines they most want to preserve, and ask parents where independence matters most. Distinguish nonnegotiable requirements from preferences that can be accommodated later.
Before proceeding, assemble the address-specific school checks, medical arrangements, floor-plan review, insurance proposals, tax assumptions, and transport plan. Have the appropriate professionals confirm unresolved questions. A beautiful residence becomes a convincing long-term choice when the household can explain how it will function on an ordinary weekday, not just during a viewing.
For a discreet conversation about a multigenerational South Florida home search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationChoose a location that can accommodate both school and healthcare needs. Check exact-address school options and practical journeys to medical providers before selecting a residence.
Florida options include traditional public, magnet, charter, and private schools, as well as scholarship programs. Confirm assignment, eligibility, or admissions requirements for the options under consideration.
Assess privacy, step-free access, sleeping and bathing arrangements, and room for future assistance. Verify the actual residence rather than assuming luxury finishes indicate accessibility.
Decide based on preferences for privacy, shared time, and assistance. Compare a shared home, dedicated suite, and separate nearby residence against the household's requirements.
Standard homeowners insurance typically excludes flood damage. Review separate flood coverage and the exact property's exposure before committing to a purchase.
Include essential supplies, medications, protected documents, emergency alerts, and evacuation routes consistent with local guidance. Assign responsibility for anyone who may need assistance.
No, a new application is required, and eligibility for the new primary residence must be established.
No, after the first homesteaded year, it generally limits annual assessed-value increases to the lower of 3% or the Consumer Price Index change, not the total tax bill.
Eligible owners must establish the new homestead within three years of January 1 of the year the previous homestead was abandoned. Portability is generally requested with the new homestead application, with a March 1 filing deadline.
Map school, medical, shopping, and social journeys, then test routes at relevant times. Confirm who handles each trip and what backup arrangements are available.