For yacht owners, the residence and the berth require coordinated but separate scrutiny. A disciplined acquisition file connects jumbo financing, structural reserves, litigation, shared expenses and marina rights before either commitment becomes irreversible.
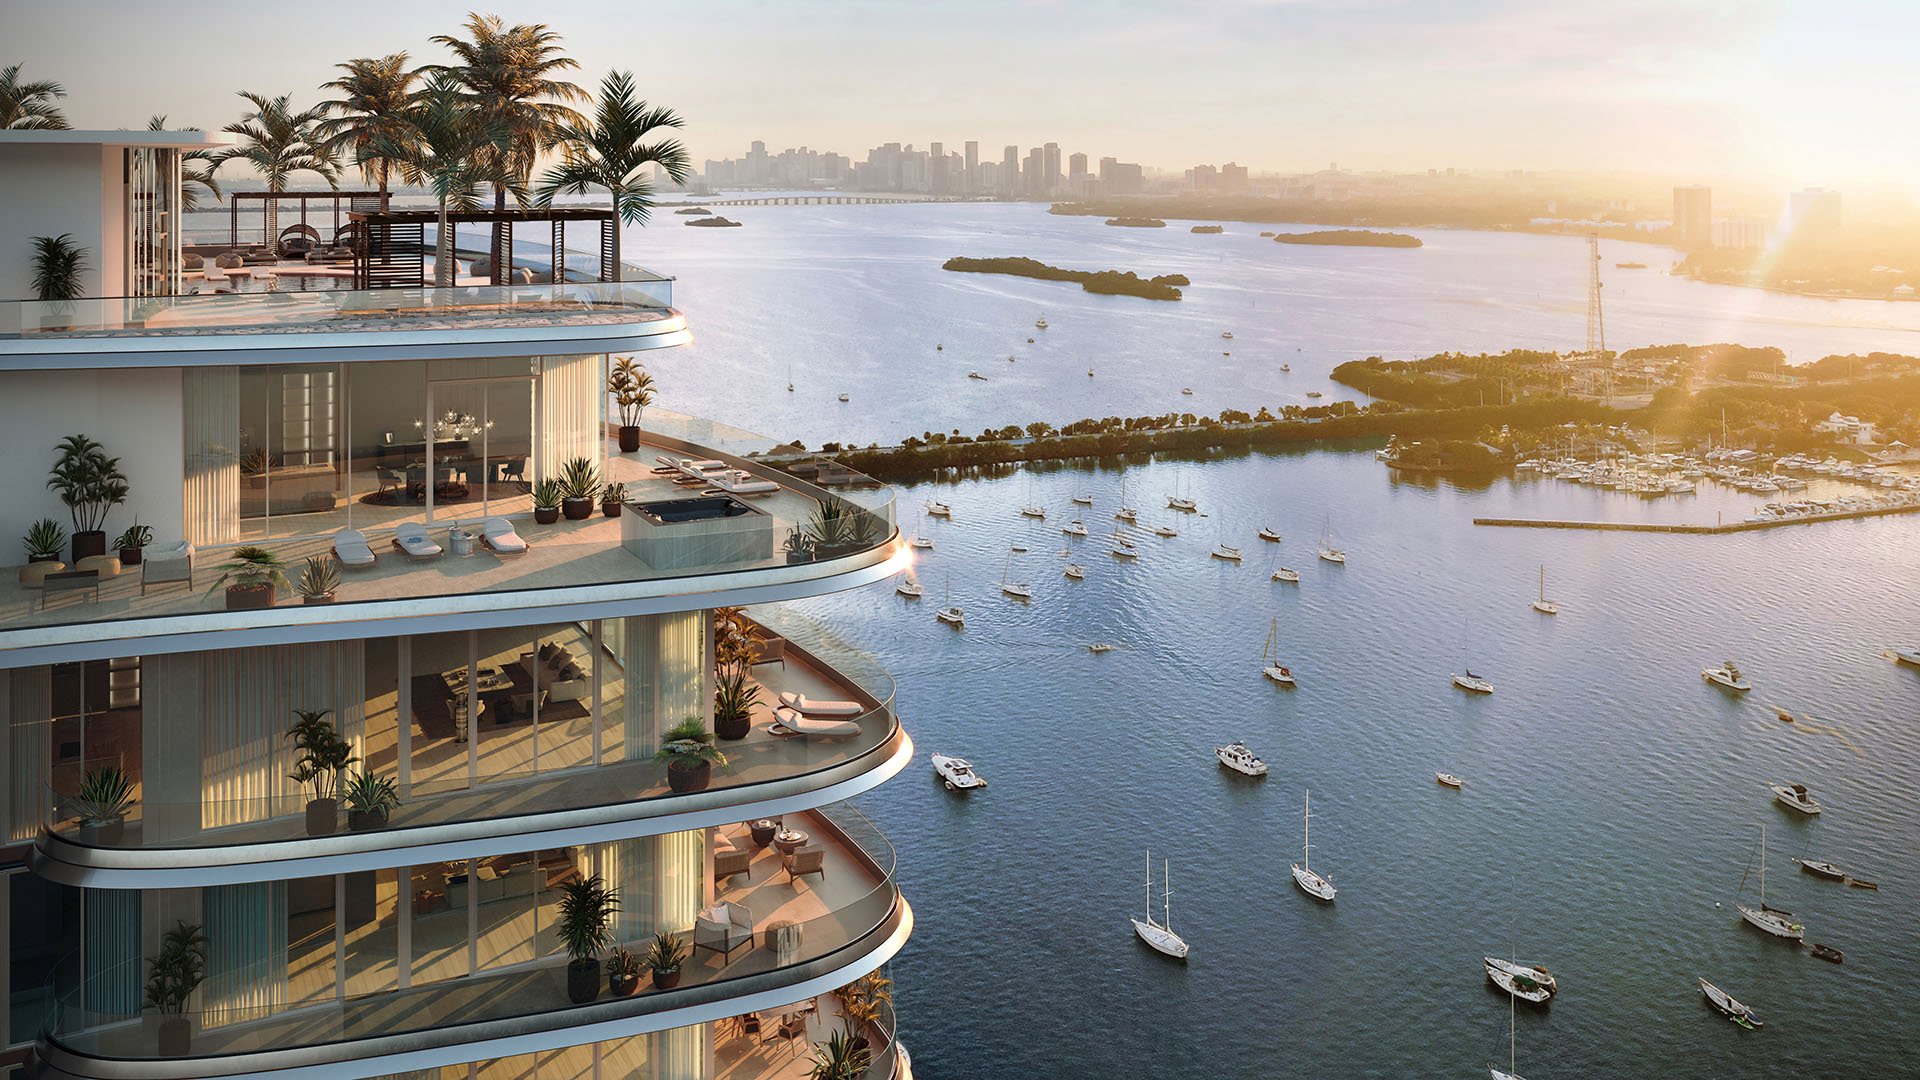
For a yacht owner, a South Florida residence promises a rhythm between home and water. The acquisition deserves an equally deliberate structure: one file for the condominium, another for the berth. A waterfront address does not establish that a slip accompanies the purchase, transfers with it or remains available on acceptable terms.
Align three decisions before commitments become difficult to unwind: whether the residence meets the buyer’s standards, whether the lender accepts the condominium project, and whether documented marina rights support the intended use. Attractive architecture cannot answer the latter two questions.
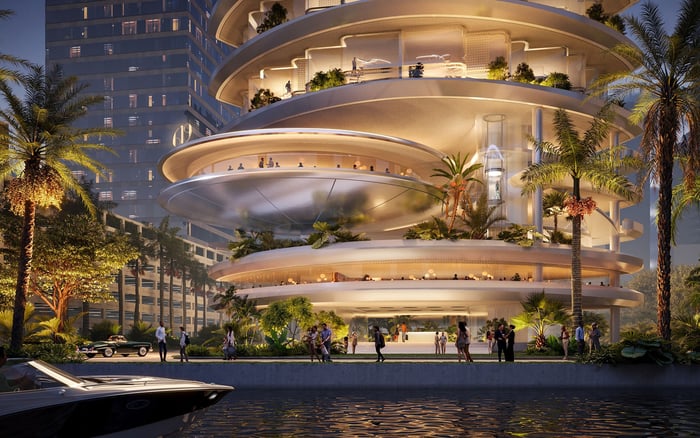
When considering St. Regis® Residences Bahia Mar Fort Lauderdale in a Fort Lauderdale search, keep the purchase agreement and any proposed dockage agreement on separate review tracks. The project reference is not a representation of slip availability, transfer rights or financing eligibility.
Do not mistake a borrower-level financing discussion for confirmation that the condominium itself is acceptable. Ask the proposed jumbo lender for its project-review requirements in writing, including the required association documents and its treatment of reserves, litigation, commercial space and ownership concentration.
Build the submission around the declaration and amendments, governing documents, current budget, financial records, reserve schedules, relevant inspection findings and association meeting minutes. Ask which documents need updating before closing and who will resolve outstanding project questions.
There is no universal eligibility cutoff to apply here. Assess commercial-space percentages, single-owner holdings, rental concentration and litigation against the selected lender’s actual criteria-not an assumed industry rule.
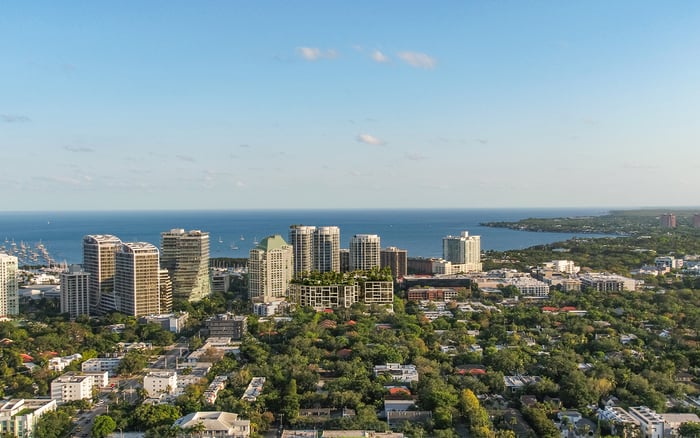
For a Brickell purchase under consideration at Una Residences Brickell, follow the same sequence before treating financing as settled. Ask counsel to coordinate negotiated financing protections with the time required for project review.
Review milestone inspections and Structural Integrity Reserve Studies, or SIRS, as distinct parts of the acquisition file: building condition and funding for future major component repairs and replacement. Do not treat either review as a substitute for the other.
Have counsel confirm whether the association is subject to these requirements, which components must be covered, and the applicable study, inspection and funding deadlines.
Read the inspection findings alongside the study, current reserve balances, adopted budget and meeting minutes. The existence of a study does not establish that the association is making the contemplated contributions or addressing identified work.
Ask counsel to confirm whether required reserves may be waived, reduced or used for other purposes. Older deadlines and funding assumptions should not determine a present acquisition decision without confirmation.
Reserve adequacy depends on obligations, timing and contributions-not simply an impressive account balance. “Fully funded” should not be read as requiring every component’s entire future replacement cost to sit in cash immediately.
Ask the financial reviewer to reconcile four elements: estimated repair costs, anticipated timing, available component reserves and scheduled contributions. Then identify any gap between the study’s funding path and the association’s actual budget and deposits.
Where funds are insufficient, inspection findings and repair obligations can create pressure for higher contributions or special assessments. Request documentation of approved assessments and discussions of potential additional work. Distinguish adopted obligations from proposals still under consideration.
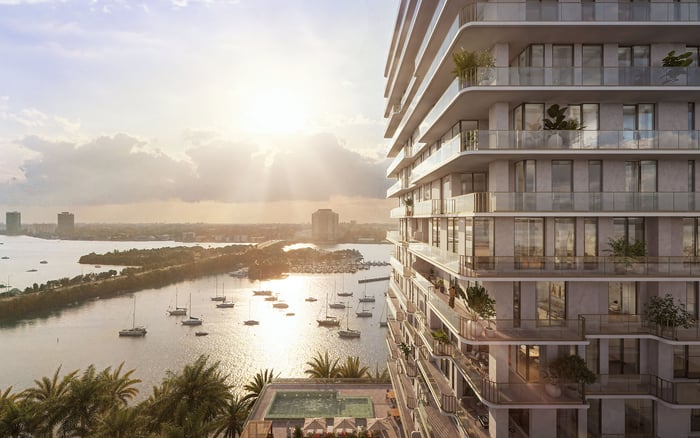
For a buyer evaluating Vita at Grove Isle in a Coconut Grove search, the discipline is the same: compare the intended ownership horizon with the documented capital calendar, without presuming any project-specific shortfall.
Request association litigation disclosures and relevant minutes, then have counsel examine court records where appropriate. Focus on structural, water-intrusion, seawall, dock and insurance disputes, without making assumptions about any named property.
For each identified matter, ask what relief is sought, which entity bears the exposure, what insurance position has been documented and whether associated work remains unresolved. Separate allegations from findings, and estimated costs from established obligations.
A case label alone is not a financing conclusion. Send the relevant materials to the lender and obtain its determination rather than assuming all litigation is acceptable or disqualifying. Counsel’s review should also connect potential liabilities to the buyer’s negotiated assessment and closing provisions.
In a mixed-use property, establish the residential association’s responsibilities through the declaration and shared-expense provisions. Do not assume commercial and residential costs are separated merely because entrances or uses differ.
Trace the allocation of maintenance and capital obligations for shared facilities. Ask who controls spending decisions, how charges are allocated and whether the residential budget reflects the documented responsibilities. The question is not simply how much commercial space exists, but what obligations attach to it.
Ownership and rental concentration require a separate inquiry. Request current ownership and rental information sufficient for counsel and the lender to evaluate concentration under their respective review standards. Concentration alone is not proof of underfunding or poor governance. Do not turn a percentage into a conclusion without examining the underlying records and applicable lending criteria.
Obtain the dockage agreement and ownership documents. Have counsel identify the nature of the offered right, transfer conditions, renewal and termination provisions, storm-closure terms, insurance obligations and shared-maintenance charges. Confirm, rather than assume, that the arrangement supports the buyer’s intended vessel and use.
A building’s SIRS is not proof of adequate funding for docks, seawalls, pilings or marina electrical systems. Separately identify the responsible entity, applicable maintenance budget and documented capital obligations for that infrastructure.
For buyers comparing Onda Bay Harbor with other residential options, any proposed boating arrangement deserves this independent review. Proximity to water is not a contractual right to occupy a berth.
Before closing, assemble a concise schedule of unresolved lender conditions, reserve questions, litigation exposure, shared expenses and marina approvals. Assign each item to the professional or counterparty responsible for answering it, with a deadline aligned to the negotiated contracts.
Ask counsel whether closing conditions and available termination protections adequately address the buyer’s dependence on confirmed marina rights. Prepare a combined ownership budget that distinguishes condominium charges, documented assessments, dockage costs, insurance obligations and shared-maintenance exposure. Keep unapproved possibilities separate from committed expenditure.
The result should be confidence grounded in documents: a residence chosen for its quality and a boating arrangement confirmed on its own terms.
Explore South Florida residences with MILLION as you refine a coordinated home-and-marina acquisition plan.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume it does. Review the purchase documents and any separate dockage agreement to confirm availability, transfer conditions and the nature of the offered right.
Request written project-review requirements and the documents needed to assess the condominium. Ask specifically how the lender evaluates reserves, litigation, commercial space and ownership concentration.
A milestone inspection addresses building condition, while a Structural Integrity Reserve Study evaluates funding for future major component repairs and replacement. Review them together rather than treating either as a substitute.
Have counsel confirm the current study interval and applicable deadlines for the particular association. Do not rely on an older study’s schedule without checking current requirements.
Not necessarily. Evaluate the study’s funding schedule, repair timing, available reserves and actual association contributions together.
Review the SIRS, reserve schedules, current budget, financial records, inspection findings and meeting minutes. Reconcile planned contributions with actual funding and documented repair obligations.
Do not assume an automatic outcome. Counsel should examine the dispute and potential exposure, and the selected lender should determine its treatment under its project-review criteria.
Review the declaration and shared-expense provisions to identify residential responsibilities and spending control. Confirm the lender’s criteria rather than applying an assumed commercial-space cutoff.
Concentration alone does not establish poor governance or underfunding. Examine ownership and rental information alongside financial records and the selected lender’s requirements.
Do not assume it does. Identify the entity responsible for docks, seawalls, pilings and marina electrical systems, then review the applicable maintenance budget and capital obligations.