For siblings acquiring a seasonal South Florida residence, rental flexibility belongs in the closing strategy, not the assumptions. Align association restrictions, local rules, financing, insurance, and a written co-ownership agreement before committing to the purchase.
A shared South Florida residence promises something valuable: a familiar setting for family holidays, winter visits, and time together. For siblings, however, the purchase requires more than agreement on bedrooms and views. The central closing question is whether the property can accommodate their personal-use calendar and intended leasing without conflicting with association documents, local requirements, financing, or insurance.
Rental flexibility is not a single permission but a set of conditions that must work together. An association may permit leasing on terms that make the siblings’ preferred schedule impractical. A lender may evaluate the same plan differently from the family.
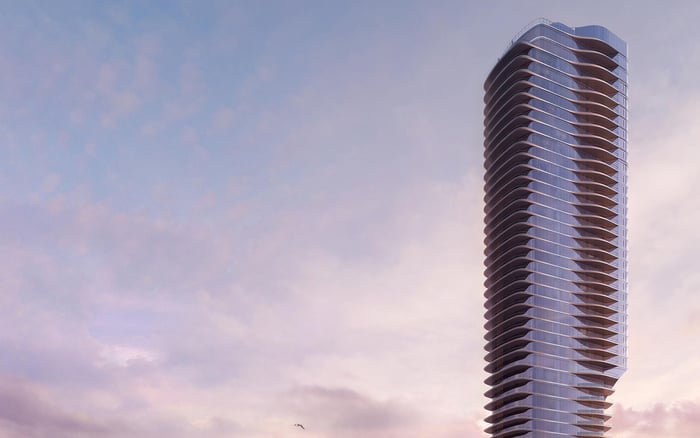
For siblings considering The Residences at 1428 Brickell, the practical starting point is a written use plan: who will occupy the residence, when, and whether rental income is optional or necessary. That plan should guide diligence, not follow it.
Florida condominium rental restrictions depend on governing documents and valid amendments. Buyers should not assume a statewide rental cap, minimum term, or ownership waiting period.
Under Florida Statutes §718.110(13), amendments prohibiting rentals, changing rental duration, or limiting rental frequency generally apply to consenting owners and owners acquiring title after the amendment takes effect. Siblings purchasing together should evaluate restrictions as incoming owners, not assume they inherit a seller’s protection against an earlier amendment.
That distinction matters when a seller describes the residence’s rental history. Past practice is no substitute for reviewing the provisions that will apply after closing.
Nor should the statute be treated as blanket protection against tenant screening, registration, approval procedures, or every ownership waiting period. Have counsel analyze the specific provision and its applicability before relying on an exception.
Request current governing documents and amendments, then seek written clarification of the operational details. The review should establish:
Minimum and maximum lease terms, plus annual lease limits.
Any ownership waiting period before leasing may begin.
Rental caps and whether capacity is available to the proposed buyers.
Application fees, deposits, required submissions, and approval deadlines.
Renewal procedures and any distinction between guests and tenants.
Next, test the siblings’ actual calendar against those rules. A permissible lease duration does not establish how often the unit can be rented. An acceptable tenant does not eliminate a waiting period.
In Miami Beach, a family evaluating The Perigon Miami Beach should request project-specific documents rather than infer rental flexibility from location or presentation. The same principle applies throughout the market; no particular rental policy is assumed here.
Set the co-ownership agreement’s permitted lease term no shorter than the strictest applicable minimum. Internal consent cannot override an association restriction, local requirement, or loan condition.
Tenant approval deserves its own timeline. Verify whether approval must precede lease signing or occupancy, what constitutes a complete application, and whether renewals require fresh approval.
Do not assume silence means consent. Establish whether the documents expressly provide approval by silence, and have counsel assess the provision before relying on it.
Designate which sibling assembles the application, communicates with management, signs the lease, and confirms approval before access is provided. The agreement should also explain what happens when one sibling favors an applicant and the other objects.
These measures help prevent a commitment to a tenancy that cannot proceed on the intended dates. Approval timing belongs alongside minimum terms when assessing whether seasonal leasing is workable.
The Miami-Dade vacation-rental framework defines short-term vacation rentals as dwellings rented wholly or partly to transient occupants for less than 30 days or one calendar month, whichever is less. The definition includes condominium, cooperative, and apartment units-not only detached houses.
A lease of 30 days or longer may fall outside that definition. That alone does not establish permission to rent.
Where this framework applies, overnight occupancy is generally limited to two people per bedroom plus two additional people, capped at 12 and excluding children under three. In certain residential designations, the responsible party must reside at the property for more than six months annually, potentially conflicting with seasonal-only ownership.
Confirm the property’s jurisdiction and applicable provisions rather than extending these requirements across South Florida. Separately, seasonal leasing may trigger residential landlord-tenant obligations under Florida Statutes Chapter 83, Part II.
Principal-residence, second-home, and investment classifications can produce materially different financing reviews. Disclose the proposed arrangement accurately: shared family occupancy, anticipated rentals, and any management agreement.
For certain conventional second-home financing, an agreement giving a management firm control over the borrower’s occupancy is incompatible with eligibility. Projected rent is not automatically qualifying income, either. Investment-property lease income may be usable only under specified circumstances. Ask the lender what it will accept before building the purchase budget around that income.
Borrower eligibility and project eligibility are separate questions. Certain conventional programs exclude condominium or cooperative hotel units and projects with mandatory memberships requiring association members to pay dues to third-party recreational organizations. Those standards should not be generalized to every loan program or inferred from a project’s name.
Insurance also deserves early coordination. Contents, rent-loss, or tenant coverage may be considered during occupancy reverification when reviewing actual use. Describe the same seasonal and rental plan to the insurer and lender, and resolve inconsistencies before closing.
Even when leasing is permitted, shared ownership needs its own operating rules. For a Coconut Grove search that includes Park Grove Coconut Grove, the family agreement deserves attention alongside residence selection, without assuming any particular project policy.
Have counsel address personal-use scheduling, holiday priority, guest versus tenant occupancy, authority to approve and sign leases, management duties, income allocation, and reserves. Include deadlock procedures, buyouts, and sale arrangements.
Distinguish rental income the siblings hope to receive from funds they can commit without it. That makes a waiting period or approval delay something the family has planned for, rather than an immediate source of dispute.
Seek suitable document-review, financing, insurance, and rental-eligibility contingencies. Before those protections expire, ask the relevant advisers to resolve open questions about permitted use, approval timing, loan classification, and coverage.
The objective is not maximum rental freedom at any cost. It is a residence whose documented rules support the family’s intended ownership experience. If that alignment is absent, revise the use plan or reconsider the purchase before closing.
Explore South Florida residences with MILLION and make verified use rights part of your selection criteria.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo uniform statewide waiting period should be assumed. Review the association’s governing documents and valid amendments for the provisions applicable to the purchase.
They should not assume so. Amendments covered by §718.110(13) generally apply to owners acquiring title after the amendment takes effect, as well as consenting owners.
No. Screening, registration, approval procedures, and ownership waiting periods require analysis of the specific provision rather than reliance on blanket protection.
No. It may fall outside the cited Miami-Dade short-term-rental definition, but association requirements, applicable local rules, and loan conditions still need review.
Confirm minimum and maximum terms, annual lease limits, ownership waiting periods, rental-cap availability, fees, deposits, and approval deadlines. Check renewal requirements as well.
No. Verify whether the governing documents expressly provide approval by silence and obtain advice on the provision before relying on it.
No. Rental income is subject to the applicable loan program’s requirements, and lenders may accept investment-property lease income only under specified circumstances.
Yes. For certain conventional second-home financing, an agreement giving a management firm control over borrower occupancy is incompatible with eligibility.
Address use schedules, guests and tenants, leasing authority, management responsibilities, income allocation, and reserves. Include procedures for deadlocks, buyouts, and sale.
Yes. Disclose the actual seasonal and rental plan to both before closing, since occupancy classification and insurance coverage need to reflect the intended arrangement.