A private cabana can make waterfront living more effortless, but its value depends on the rights conveyed, the full carrying cost and how often you will actually use it. Here is how to evaluate the purchase before committing.
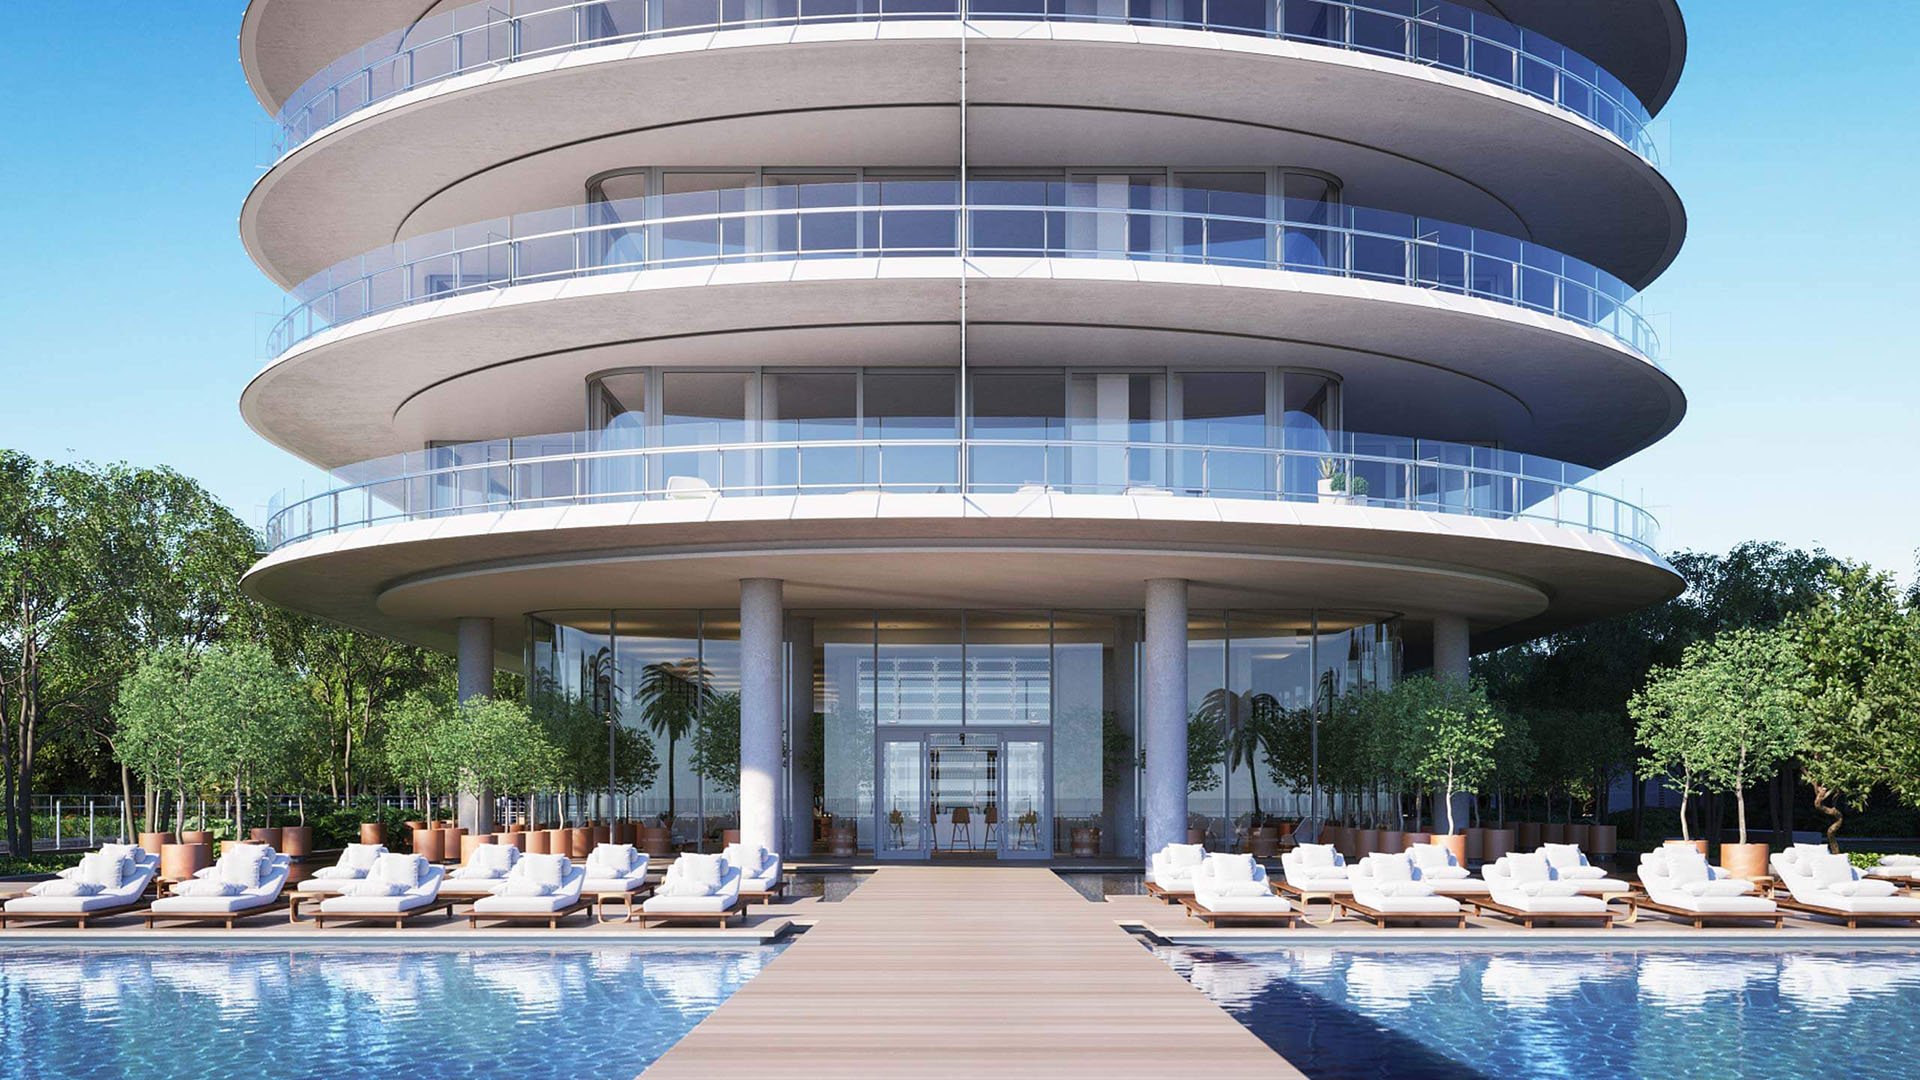
A cabana is an appealing addition to a South Florida condominium: a place to settle into the day without repeatedly returning upstairs. Yet the purchase decision turns less on the romance of poolside living than on the precise rights attached to the space. The same word can describe a separately marketed property, a private amenity associated with a residence or a shared facility available to residents.
The answer is conditional. Buy when the cabana materially improves your routine, its ownership structure is clear and its total cost is proportionate to that use. Pass when the appeal rests primarily on presumed scarcity, future appreciation or the suggestion that every waterfront residence needs one.
Before negotiating, establish whether you are acquiring a separately deeded condominium parcel, an assigned right of use or access to a common amenity. Ask your attorney to reconcile the purchase contract with the declaration, amendments and any documents governing the cabana. Marketing language alone does not establish ownership or transferability.
Miami Beach offers a useful contrast in formats. At Beach House 8, each residence is described as having an 8-by-6-foot private poolside cabana with chaise lounges and a minibar. This describes a residence-associated amenity, not a standalone purchase offering, and should not be confused with a much larger space marketed separately.
At Eighty Seven Park Surfside, the amenities include swimming pools, poolside cabanas and towel service. Those features do not, by themselves, establish individual ownership or transfer rights. The buyer's task is to distinguish an attractive setting from an asset that can legally be acquired and conveyed.
At Armani Casa Sunny Isles Beach, a 600-square-foot private corner beach cabana was offered for an additional $1.05 million. It was available with the residence or separately, but only to owners within the development. Separate purchase, in other words, did not mean unrestricted buyer eligibility.
At the same Collins Avenue address, Cabana 20 was offered for $799,000. Its stated area was 2,271 square feet, a figure requiring independent confirmation before any size-based comparison. Ask exactly what the measurement includes rather than treating every advertised square foot as equivalent usable space.
These asking-price snapshots are neither confirmed current offerings nor closed-sale evidence. They demonstrate that cabana asking prices can be substantial-not market value, likely appreciation or what a future purchaser will pay. Nor should a residence's headline asking price be confused with an additional cabana charge.
The alternative to buying is not necessarily giving up the cabana experience. In Coconut Grove, the amenities at Residences at Vizcaya include a bayside lap pool with private cabanas for residents. That does not establish separate deeds or cabana sale prices, but it illustrates why buyers should examine what access already accompanies a home.
If your broader search includes Four Seasons Residences Coconut Grove, apply the same document-led inquiry without assuming its amenity arrangements match another building's. Compare the rights actually offered with each residence, not merely the terminology used during a tour.
For some buyers, existing resident access may meet the need. For others, a specifically reserved space could justify a premium. Before choosing, clarify reservation procedures, guest access, service arrangements and any limits on exclusive use. These are questions to resolve, not privileges to presume.
Cabana 20's advertised association dues were $150 monthly, or $1,800 annually. That figure excluded property taxes and other ownership expenses. A modest monthly fee should be the beginning of the calculation, not the conclusion.
Estimated annual taxes at the asking price were approximately $13,175, while the existing owner's annual tax bill was identified as approximately $38,000. Those figures describe different things and require independent verification. Neither should be treated as your future obligation without reviewing the parcel and obtaining appropriate advice.
Florida condominium law provides for separate assessment of each condominium parcel for ad valorem taxes and special assessments. First establish whether the cabana is such a parcel. Then verify its tax treatment rather than assuming its expenses are absorbed into the residence's bill.
Build an ownership budget covering applicable taxes, association charges, insurance obligations, utilities, maintenance and potential assessments. Confirm which costs belong to you and which, if any, are covered elsewhere. Establish financing availability directly rather than assuming it mirrors the arrangements for the main residence.
The strongest case for buying is repeated personal enjoyment. Consider the days you actually spend by the water, not the schedule you imagine during a particularly beautiful viewing. A frequent user and an occasional seasonal visitor can reasonably reach different conclusions about the same asking price.
Walk through the experience at the hours you expect to use it. Consider shade, privacy, circulation and proximity to the pool or beach. Verify permitted activities, guest rules, storage permissions and service hours before assigning value to entertaining or convenience.
A useful private calculation is annual carrying cost divided by expected days of use. Keep acquisition capital separate so a modest operating budget does not obscure the amount committed. This is a personal-value exercise, not a prediction of investment performance.
An owner-only purchase rule limits the eligible resale audience to owners within that development. The Armani/Casa example makes the distinction clear. It does not establish how quickly a cabana will sell or whether its price will rise or fall.
Have counsel confirm whether the cabana can be sold independently, whether ownership of a residence must continue and what happens if you sell your condominium first. Ask about required approvals and any restrictions on transferring the cabana with the home. Do not assume it can be rented, financed separately or sold to an outside purchaser.
The decision becomes clearer once three elements align: secure rights, verified costs and compelling personal use. If one remains unresolved, pause. A cabana should make ownership more effortless, not introduce an obligation you understand only after closing.
For a considered approach to your South Florida condominium search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationConsider buying if you expect frequent personal use, understand the rights conveyed and have verified the full ownership cost. Do not rely on presumed appreciation or rental income to justify the purchase.
No. A cabana may be separately owned, associated with a residence or part of a resident amenity; the governing documents must establish the arrangement.
One Armani/Casa listing offered a 600-square-foot cabana for an additional $1.05 million, while another advertised Cabana 20 for $799,000. These were asking-price snapshots, not verified current offers or closed sales.
Eligibility depends on the building and the particular rights offered. The $1.05 million Armani/Casa cabana was available separately but only to owners within the development.
Florida law provides for separate tax assessment of each condominium parcel. Establish whether the cabana is a separate parcel and verify its tax treatment before purchasing.
No. Cabana 20's advertised $150 monthly dues excluded property taxes and other ownership expenses, so buyers should verify all applicable charges and obligations.
Cabana 20's listing estimated approximately $13,175 in annual taxes at the asking price while identifying approximately $38,000 as the existing owner's annual bill. Neither figure should be assumed to represent a purchaser's future obligation.
No. An amenity description can establish that cabanas are offered without establishing individual deeds, exclusive-use rights or transferability.
The available facts do not establish a measurable resale premium or appreciation rate. Owner-only eligibility also limits the potential cabana buyer audience.
Ask counsel to review the contract, declaration, amendments and documents governing ownership, permitted use and transfer. Clarify what happens to the cabana if you sell the residence first.