For seasonal buyers considering Shore Club and The Perigon, financial clarity begins with expense allocations, reserve funding and capital planning, not the advertised monthly fee alone.
The most valuable luxury for a seasonal Miami Beach owner may be predictability: arriving at a residence that feels effortless, with a clear understanding of the financial commitments behind that ease. At Shore Club and The Perigon, the useful comparison is not simply which monthly fee appears lower. It is how clearly each ownership structure accounts for service costs, future capital needs and the owner's share of both.
A seasonal purchase deserves a full-year financial model. Separate the acquisition commitment, recurring association charges, privately paid expenses and liquidity reserved for unexpected costs. Then consider the months of personal use. Underwriting only the occupied season risks confusing the lifestyle calendar with the ownership commitment.
Neither project should be ranked as having stronger reserves, lower assessment exposure or more predictable fees without verified budgets and supporting documents. The decision rests on the quality of the financial explanation, not a presumed winner.
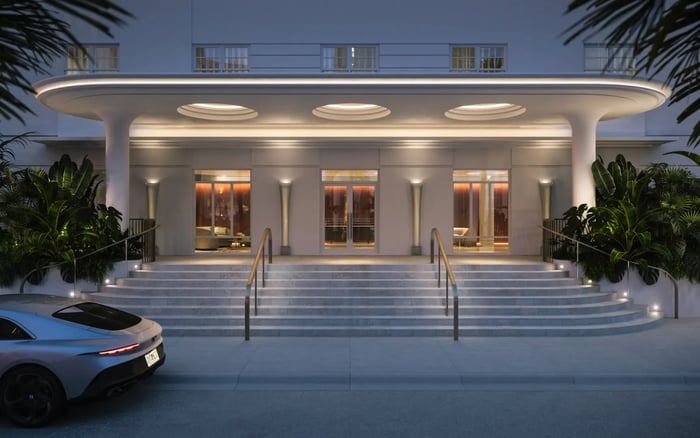
At 1901 Collins Avenue, Shore Club Private Collections Miami Beach is described as a 49-residence project associated with Witkoff, Monroe Capital and Auberge Resorts Collection. Its positioning pairs boutique residential privacy with five-star hotel service. For the seasonal buyer, that combination raises a precise question: which services are covered by the association budget, and which are billed separately?
Residences are advertised from approximately $6 million, subject to confirmation of current pricing and availability. That entry point says little about the eventual annual carrying cost. Request an itemized explanation of association coverage, optional services and any expense-sharing arrangements that apply to the residence.
An indicative dues estimate of $2.50-$3.50 per square foot monthly offers a starting scenario, not a verified association budget or binding fee. Applied to a hypothetical 3,500-square-foot residence, it yields $8,750-$12,250 monthly in association dues alone. Property taxes, owner insurance, utilities and other separately billed expenses remain outside that calculation.
Next, reconcile the estimate with the applicable budget and allocation method. Ask which assumptions drive the range and what could change before closing. Do not treat the lower end as a promised ownership cost.
For The Perigon Miami Beach, the declaration's schedule of units and percentage ownership is the starting point for determining an owner's allocated share of common expenses. A residence's size or purchase price is no substitute for reviewing that schedule.
Ask the reviewing attorney to identify the specific residence's allocation and explain which expenses that percentage governs. Then request a reconciliation between the allocation and the proposed or applicable annual budget. This turns an attractive monthly figure into a number that can be understood and checked.
Fewer owners can mean larger individual expense and reserve contributions, but the outcome depends on the declaration and the costs being shared. Exclusivity is not evidence of either financial efficiency or excessive expense. It is a reason to examine the allocation carefully.
For a buyer comparing residences of different sizes, the key distinction is between the overall association budget and the share assigned to each home. Both deserve review before drawing conclusions about value.
Reserve funds are association money set aside for major future repairs and capital improvements. Their purpose is distinct from the daily service experience. A polished arrival and attentive service do not establish whether future work has been identified, costed and funded.
Request the reserve-funding schedule and any supporting study or capital forecast available for review. Ask how contributions were established, which components they address and when the assumptions will next be revisited. Where future balances are projected, distinguish money already held from contributions expected later.
The same discipline applies to a broader Miami Beach search. If Setai Residences Miami Beach is also on a buyer's shortlist, compare the scope of included services and reserve contributions before comparing headline dues. This is a framework for comparison, not a conclusion about any property's finances.
A larger monthly contribution does not automatically signal poor value, nor does a smaller one establish efficiency. The relevant question is what the contribution funds-and what remains outside it.
Capital diligence should distinguish routine operations from major future work. Request any approved capital-project plans, details of anticipated major projects and information about current or contemplated special assessments. These questions do not imply that either building has a repair problem or pending assessment.
For each identified project, seek three answers: what is included, when expenditure is expected and how it will be funded. Ask whether figures are preliminary allowances or approved amounts, and whether the owner's potential share can be calculated under the governing documents.
Review association insurance alongside the capital discussion. Ask about coverage, exclusions and deductibles, and have an insurance adviser clarify what the owner's separate policy should address. Consider financial condition, reserve funding and insurance together rather than as isolated checklist items.
For seasonal use, scheduling also matters. Ask how owners receive notices of planned work and how access would be coordinated during an absence. Operational clarity is part of an effortless second home.
Shore Club's advertised completion target is 2027-an estimate, not a guaranteed delivery date. Its reported deposit schedule is 20% at contract, 10% after 90 days, 10% at top-off and 60% at closing. Confirm the applicable terms in the purchase agreement and keep acquisition liquidity separate from the ongoing ownership model.
At The Perigon, rental assumptions require their own document review. Clarify any six-month provision in the governing restrictions and check City of Miami Beach requirements separately. Do not translate a marketing description into an assumed right to lease.
A conservative seasonal model should work without unconfirmed rental income. If leasing is important, have counsel establish the permitted duration, frequency, approvals and applicable municipal requirements before treating potential revenue as an offset.
Before committing, assemble a residence-specific financial picture: expense allocation, association coverage, reserve contributions, capital plans, insurance and separately paid costs. Mark estimates as estimates and identify which figures are contractual, budgeted or still subject to confirmation.
Fee predictability is not a promise that costs will never change. It is a clear understanding of today's obligations, the assumptions behind tomorrow's contributions and the decisions that could alter both.
For a discreet discussion of seasonal ownership in Miami Beach, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNeither can be ranked as more predictable without verified budgets, reserve schedules and expense allocations. Compare the residence-specific obligations rather than headline fees alone.
The indicative estimate is $2.50–$3.50 per square foot monthly. It is not a verified association budget or binding fee.
For a hypothetical residence of that size, the estimate produces $8,750–$12,250 monthly in association dues. It excludes property taxes, owner insurance, utilities and other separately billed expenses.
Review the declaration's schedule of units and percentage ownership. The residence's applicable allocation should then be reconciled with the association budget.
Reserves are association money set aside for major future repairs and capital improvements. Review their funding separately from the amenities and daily services.
No. Fewer owners can mean larger individual contributions, although actual costs depend on expense allocations and what is shared.
No. Asking about capital plans and special assessments is financial diligence, not evidence of an existing repair problem or pending assessment.
The advertised target is 2027. It is an estimate, not a guaranteed delivery date.
The reported schedule is 20% at contract, 10% after 90 days, 10% at top-off and 60% at closing. Confirm the applicable obligations in the purchase agreement.
No. Clarify any six-month provision in the governing documents and check City of Miami Beach requirements separately before assuming rental income.