For London buyers relocating to Brickell, a successful first year begins with coordinating sale proceeds, verified liquidity and purchase deadlines. A disciplined sequence can preserve both negotiating flexibility and the reserves needed after closing.
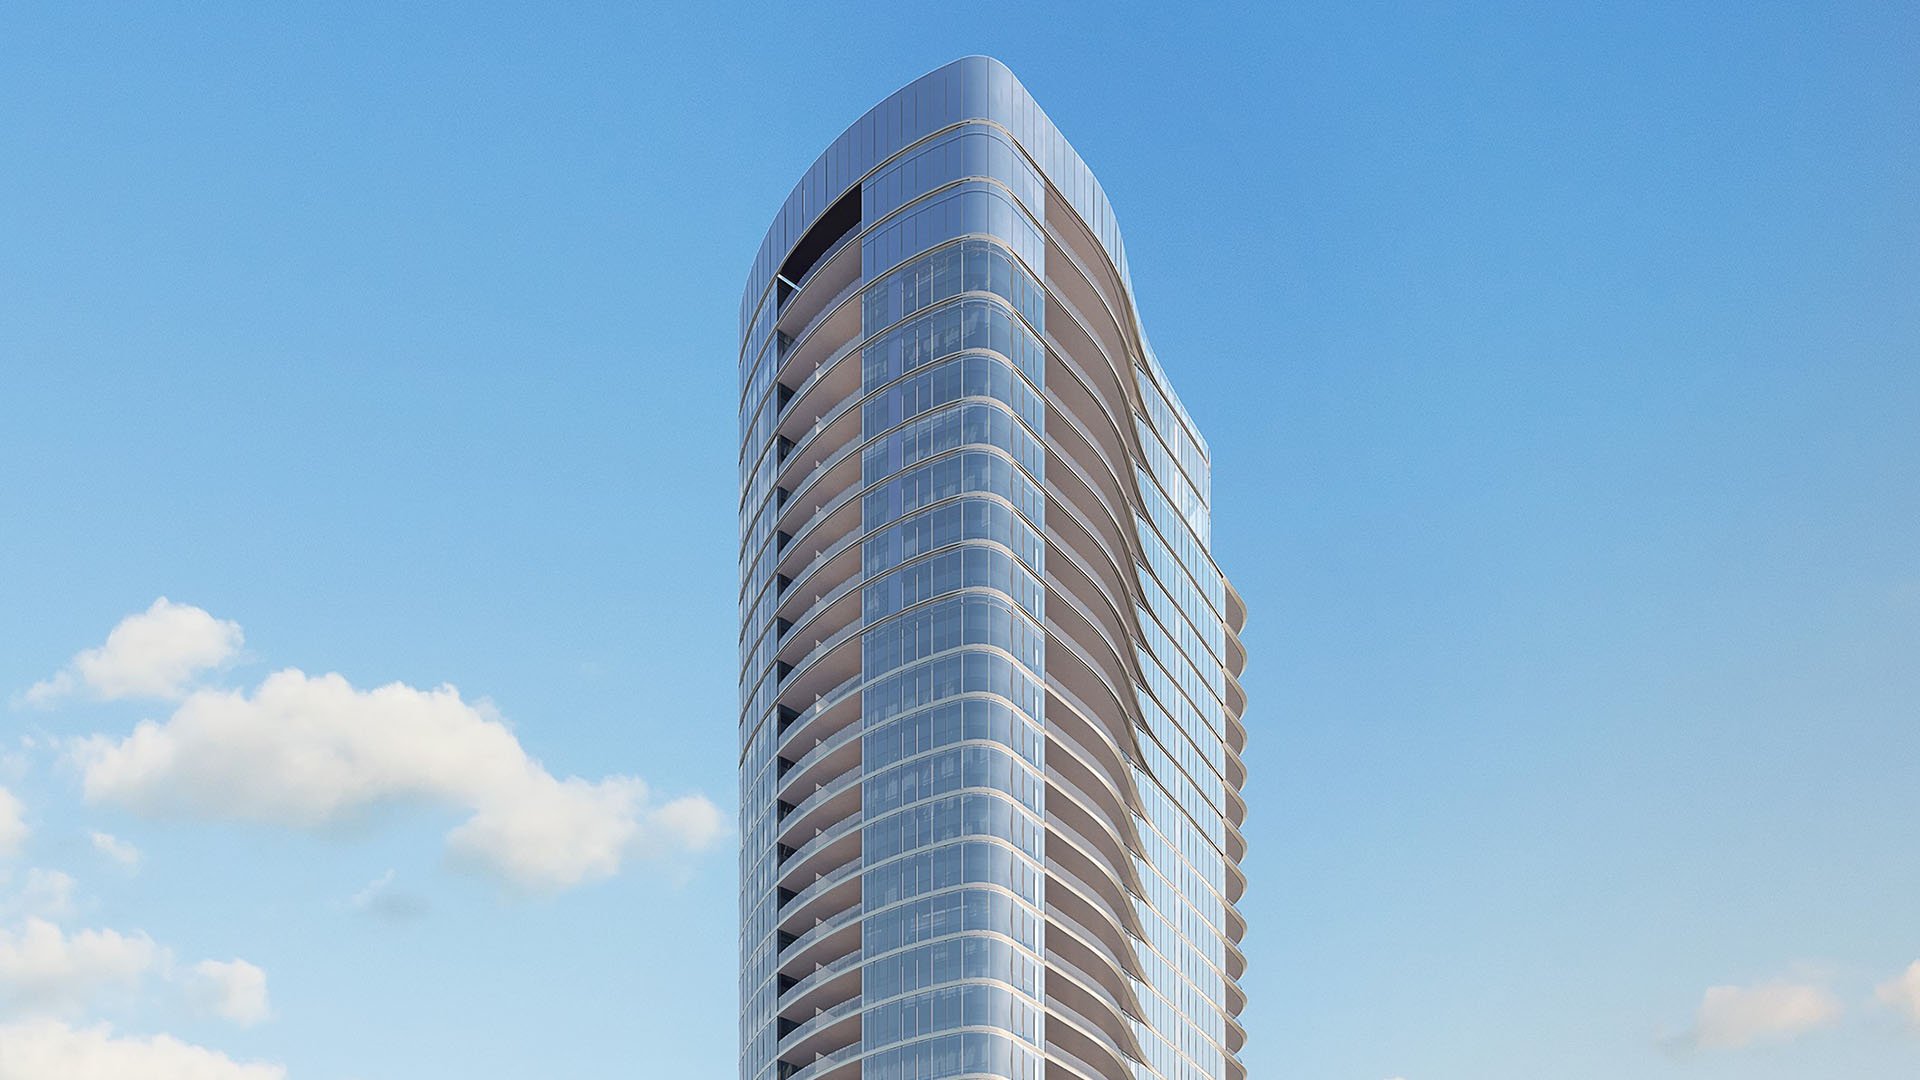
A London-to-Brickell relocation is easier to imagine through a residence than through a cash-flow schedule. Yet the quality of the first year may depend less on the view than on whether capital arrives when it is needed. The essential distinction is simple: expected London sale proceeds are not the same as accessible purchase funds.
Build the acquisition around three milestones: London exchange, London completion and Brickell closing. Ask the professionals handling each transaction to confirm what must happen at each stage, what remains conditional and when money becomes usable. An anticipated completion date should not become a promise to a Miami seller.
For a buyer considering Una Residences Brickell, the first financial question is not simply affordability. It is whether the purchase can proceed on its own timetable without exhausting the capital reserved for the move.
Three planning approaches deserve consideration. Selling first makes the purchase budget easier to establish once net proceeds are available, but may require interim accommodation. Buying first separates the Miami decision from the London sale only if independent liquidity or a confirmed financing arrangement supports it. Coordinating both transactions closely limits the planned overlap but leaves less room for delay.
None is inherently superior. The appropriate sequence depends on which commitment the household can carry if the other transaction is delayed. Before choosing an approach, test a delayed London completion, a slower financing process and a purchase requiring more cash than initially budgeted.
Maintain separate lines for net London proceeds, bridge availability, currency conversion, purchase deposits, closing costs and first-year reserves. Label each amount as available, conditional or expected. Keep the gross London sale price out of the spendable-cash column; obtain a transaction-specific estimate of deductions before setting the Brickell budget.
Ask the closing team and any lender to establish a realistic timetable for the specific Brickell purchase. The proposed closing date should reflect the transaction and the readiness of its funding, rather than the most optimistic scenario. Confirm the applicable financing route and documentation requirements with the lender rather than assuming a classification based on the relocation alone.
When assessing 2200 Brickell, request the timing and payment requirements for the specific residence under consideration. Do not apply a generic resale closing window to every purchase structure. The relevant question is when each contractual payment falls due, not merely when the household hopes to arrive.
Evaluate bridge funding as a specific financing arrangement, not a reassuring placeholder between two dates. Before relying on it, ask the proposed lender to confirm eligibility, required security, draw conditions, availability dates, costs, repayment terms and the consequences of a later London completion.
Distinguish an initial discussion from an arrangement that can fund the purchase when required. Ask the closing team how borrowed purchase funds should be documented and how any outstanding conditions affect the offer. A financing expectation should not be described as verified cash.
Then test the repayment plan. If repayment depends on London proceeds, establish how a delay would affect both the facility and the household's remaining reserves. Have the relevant advisers review the proposed structure and cross-border implications. Bridge pricing, eligibility and UK-US tax treatment require individual advice, not universal assumptions.
Prepare evidence of liquid capital available to complete the purchase, rather than relying on evidence that a valuable London property is being marketed or is expected to sell. Ask the transaction team what bank letter or statement will satisfy the requirements for the offer.
Confirm the seller's expectations for the form and recency of documentation before submitting an offer. Refresh the evidence as required if the search or negotiation extends beyond its useful date.
If The Residences at 1428 Brickell is on the shortlist, align the evidence with the proposed payment obligations. Ask the transaction team how account ownership, currency and any transfer steps should be presented.
For a foreign-national mortgage application, ask the lender which documents are needed, including whether to prepare passports and immigration details, overseas financial statements, income evidence, source-of-wealth explanations, banking references, or translated or certified documents. Preparing the requested file early can reveal documentation issues before a purchase deadline becomes pressing.
Do not assume that a seller will accept a delayed closing or a sale-dependent offer. Evaluate the terms available for the specific residence rather than building the relocation schedule around presumed negotiating leverage.
Ask advisers to examine the building's reserves and structural compliance alongside the apartment itself before treating a lower asking price as a liquidity advantage.
A shortlist that includes Cipriani Residences Brickell should compare more than headline prices. Review the applicable deposit obligations, remaining payments and purchase terms for each opportunity. Different acquisition structures can produce very different first-year cash requirements, even when the intended budgets are similar.
The closing balance is not the relocation budget. Preserve a separate reserve for the household's expected first-year ownership and settling-in expenses, using property-specific figures and professional estimates rather than a generic percentage. If interim accommodation or overlapping commitments are part of the sequence, account for them explicitly in that reserve plan.
Keep sterling proceeds and dollar obligations on separate lines until conversion arrangements are established. Ask the banking or currency adviser to clarify execution timing, costs and any proposed hedging terms. Do not build the purchase around an assumed favorable exchange-rate move.
Review the schedule at each milestone. At London exchange, update the conditions still outstanding. At completion, reconcile actual net proceeds and transfer readiness. Before Brickell closing, confirm the remaining purchase balance, evidence of funds and protected reserves. The objective is not the fastest possible move, but a purchase that leaves the household financially comfortable once the keys are delivered.
For a discreet discussion of your Brickell residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCoordinate London exchange, London completion and Brickell closing. Confirm the conditions and cash requirements at each milestone with the professionals handling the transactions.
Expected proceeds are not equivalent to liquid funds available to complete a purchase. Ask the transaction team what evidence of accessible capital is required.
Ask the closing team to establish a realistic window for the specific purchase. Base the proposed date on transaction requirements and the readiness of funds.
Confirm the applicable financing route, documentation requirements and timetable with the lender. Avoid committing to a closing date based on an unconfirmed financing expectation.
Confirm the seller's recency requirements before submitting the offer. Refresh the evidence as required if the search or negotiation continues.
Confirm eligibility, security, draw conditions, availability, costs and repayment terms with the proposed lender. Test how a delayed London completion would affect repayment and remaining reserves.
Ask whether the lender needs passport and immigration details, overseas financial statements, income evidence, source-of-wealth explanations or banking references. Confirm whether translations or certification are required.
No; evaluate the terms available for the specific residence. Do not base the relocation schedule on presumed negotiating leverage.
Track them separately until conversion arrangements are established. Ask the banking or currency adviser to clarify execution timing, costs and any proposed hedging terms.
Yes, keep the planned reserve distinct from deposits, the closing balance and closing costs. Use property-specific estimates and include interim accommodation or overlapping commitments where relevant.