For Dallas buyers relocating to Palm Beach Gardens, the first year should balance lifestyle with resale flexibility. Property-specific liquidity, association approvals, ownership costs and discreet showing arrangements deserve attention before the purchase closes.
A move from Dallas to Palm Beach Gardens is both a lifestyle decision and a commitment of capital. The residence should suit the household today while leaving a workable exit if business obligations, family priorities or preferences change during the first year. Exit planning is not pessimism. It is part of buying well.
For a Palm Beach relocation, four questions deserve attention before an offer: how comparable homes trade, what a subsequent purchaser must complete, how ownership costs are structured and how showings could be managed discreetly. These questions belong alongside architecture, setting and everyday comfort.
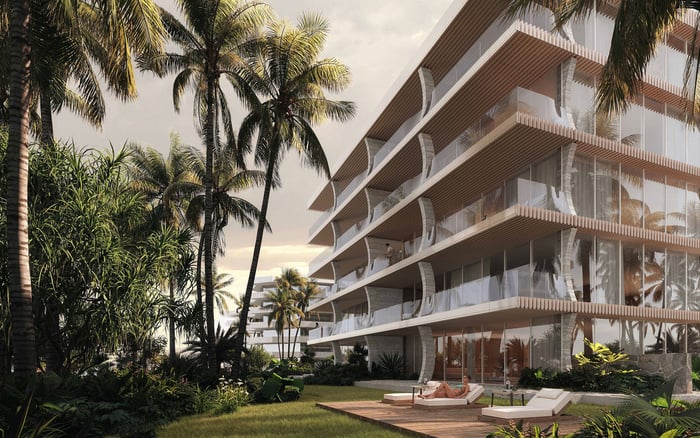
A buyer considering The Ritz-Carlton Residences® Palm Beach Gardens should request property-specific resale and association information rather than apply another community’s procedures. The same discipline should guide every candidate on the shortlist.
Before relying on a marketing-time figure, ask which period, property types and price range it covers. Averages and medians answer different questions, and neither should replace a review of closely comparable homes.
For a Dallas buyer, the question is not whether one city is universally more liquid than the other. Instead, ask an adviser to examine local properties with similar pricing, condition, ownership structure and community obligations. Review comparable sales alongside competing listings to understand the intended residence’s position.
Keep marketing exposure separate from the path to closing. Days on market do not establish when proceeds will become available. If a first-year change is plausible, model carrying costs through both the listing period and the contractual closing process, with room for delay.
Future buyer approval refers here to the requirements a subsequent purchaser may face, not a claim that a new citywide rule has been enacted. Review the applicable governing documents rather than assume one address’s procedures apply at another.
For a home in PGA National or another Palm Beach Gardens community, ask whether association approval is required for a resale and which associations are involved. Request the current transfer checklist, application forms, fees and any relevant contract addenda before relying on a proposed timeline.
Have counsel identify any application deadline, approval contingency or personal-appearance requirement in the applicable documents. A future seller should coordinate those requirements with the proposed closing date rather than leave approval as a final administrative task.
Confirm whether the process involves financial information, background screening, references or interviews; none should be assumed universal. Have counsel review the provisions that affect both the purchase and eventual exit.
Do not infer a club-membership obligation from a gated entrance or golf setting. Ask whether membership is mandatory, optional or unavailable with the property. Where membership is required, confirm initiation costs and annual dues separately from HOA charges before making an offer.
Consider the future buyer’s ownership costs as part of today’s decision. Ask for a clear account of applicable dues, assessments and membership obligations so an eventual listing can present those costs accurately. Do not assume another purchaser will view those obligations as you do.
If the search extends to West Palm Beach and Alba West Palm Beach, retain the same document-first approach. Compare verified ownership obligations address by address. Do not assume that a condominium and a golf-community home share approval procedures, membership arrangements or resale conditions.
Showing privacy is easier to manage when the owner and listing adviser establish expectations in advance. One sensible approach is to request proof of funds or mortgage preapproval before confirming in-person tours. This is a recommended screening practice, not a marketwide mandate or a guarantee of discretion.
Consider an appointment system to log and manage visits and a designated contact to coordinate tours. At a property with a staffed gate, coordinate appointments with the guardhouse so arrival procedures support the showing plan.
Agree on who confirms appointments, who accompanies visitors and how access instructions are shared. Consider showing windows that preserve household routines while giving qualified purchasers a reasonable opportunity to visit. Plan privacy and market exposure together rather than let restrictions develop ad hoc.
Keep this showing protocol separate from association approval. Financial qualification for a tour does not establish that a purchaser has satisfied the community’s transfer requirements.
Before purchase, request governing documents, budgets, reserve information, insurance documents, meeting minutes, applicable engineering documents and resale or estoppel materials. These form the foundation for understanding both ownership and eventual transfer obligations.
During the opening months, build an organized property file. Retain association correspondence, payment records and approvals for work. Ask counsel to review any unpaid assessments, violations, unresolved architectural issues or outstanding association balances for their potential effect on a later closing. Review them early rather than discover them after a contract is signed.
Before renovating, establish whether exterior changes require architectural approval. Check the rules for proposed paint colors, fences or roofing before committing to work. A first-year improvement should not become an unresolved compliance issue when the household decides to sell.
Later in the year, revisit comparable listings and the household’s likely holding period. If selling becomes a realistic option, refresh the document checklist and approval timetable before choosing a launch date. This is preparation, not a recommendation to market a home prematurely.
The strongest purchase decision considers lifestyle and transaction planning together. Ask whether the residence suits daily life, whether its obligations are understood and whether a future sale can be prepared without avoidable administrative surprises.
For households also considering Forté on Flagler West Palm Beach, use that framework to compare alternatives, not to assume equivalent liquidity. Each property needs its own comparable sales, governing documents and ownership-cost review.
The first year should be spent settling in, not reconstructing an approval trail or discovering costs that should have been understood before closing. A carefully documented purchase leaves more room to enjoy the home and greater clarity if plans change.
Explore your relocation options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThis article does not establish a city-to-city liquidity comparison. Evaluate the intended property against closely comparable local homes.
Check the reporting period, property types, price range and whether the measure is an average or median. Use the figures alongside close comparables, not as a closing guarantee.
No. Marketing exposure and the contractual closing process are separate, so exit planning should allow for both.
The article does not establish any new citywide requirement. Future approval refers to the association requirements a subsequent purchaser may face at a particular property.
Request the current governing documents and transfer checklist, including any application forms, fees and contract addenda. Confirm which associations are involved and whether resale approval is required.
Have counsel identify any application deadlines, approval contingencies and personal-appearance requirements. Coordinate applicable requirements with the proposed closing date.
Ask whether membership is mandatory, optional or unavailable with the property. Confirm any initiation costs and annual dues separately from HOA charges.
Recommended practices include financial prequalification, logged appointments and guardhouse coordination where applicable. These are planning choices, not universal association mandates.
Request governing documents, budgets, reserve information, insurance documents, meeting minutes, applicable engineering documents and resale or estoppel materials before purchase.
Confirm whether the proposed work requires architectural approval and retain any approvals received. Ask counsel to review unresolved compliance issues before a later sale.